Thursday, September 24, 2026
Home Blog Page 107

A 105-Year Journey of Struggle: The Code of China’s Development and a New Chapter in China-Africa Cooperation

0

On July 1st, the Communist Party of China (CPC) marked the 105th anniversary of its founding. For the Chinese people, it is an important occasion to reflect on the nation’s journey of struggle and achievement while looking ahead to the bright prospects. For our African friends who are interested in China’s development, it also offers an important opportunity to gain a deeper understanding of the key to China’s development.

          Over the past 105 years, the CPC has grown from a small group of just over 50 members into the world’s largest governing party with a membership of more than 100 million and tremendous global influence. Under its leadership, the Chinese people founded the People’s Republic of China, a state where the people run the country, and achieved a historic transformation in living standards—from basic subsistence to moderate prosperity, and then to moderate prosperity in all respects. The Party has also led the Chinese people through an industrialization process that took only a few decades to accomplish what developed countries achieved over centuries, creating the twin miracles of rapid economic growth and long-term social stability.

          Chinese President Xi Jinping pointed out that the fundamental reason why the CPC has been able to continuously forge glories over 105 years of struggle, and why history and the people have chosen the Party, lies in its unparalleled fine qualities.

          These fine qualities are reflected primarily in six aspects:

          First, the Party remains steadfast in pursuing truth and always steers the right course. It has consistently integrated the basic tenets of Marxism with China’s specific realities and with its fine traditional culture, while continuously adapting its theories to guide new practices.

          Second, the Party is deeply rooted in the people and always rests on a solid foundation. It is dedicated to serving the public good and exercising governance for the people, and remains committed to its fundamental purpose of serving the people wholeheartedly.

          Third, the Party bravely shoulders its historic mission and always holds the strategic initiative. It combines long-term objectives with phased goals and defines its central tasks in light of the evolving principal contradiction facing Chinese society.

          Fourth, the Party keeps pace with the trend of development and always stands at the forefront of the times. It always proactively identifies, responds to, and steers changes, advancing with the course of history and growing with the progress of the times.

          Fifth, the Party dares to struggle and excels in it, and always maintains full confidence in victory. It remains confident of ultimate success and never wavers or retreats in pursuing the interests of the people, the country and the nation, or in upholding its ideals and convictions.

          Sixth, the Party focuses on self-strengthening and always brims with vigor and vitality. It gives high priority to self-improvement and self-governance, continuously reinforcing its capacity and resilience through self-reform.

          These fine qualities hold the key to the CPC’s enduring success. They also constitute an important source of China’s development achievements and offer valuable insights into the country’s continued progress.

          The CPC is committed not only to pursuing happiness for the Chinese people and rejuvenation for the Chinese nation. It is also dedicated to human progress and world harmony. The Party has always stood on the right side of history and on the side of human civilization and progress. Chinese modernization has opened up a new path to modernization and created a new form of human advancement, offering developing countries broader options for pursuing modernization suited to their own national conditions.

          China has actively promoted the building of a community with a shared future for mankind and put forward the Global Development Initiative, the Global Security Initiative, Global Civilization Initiative, and the Global governance Initiative, contributing Chinese wisdom, Chinese solutions and Chinese strength to addressing common challenges facing humanity, while bringing greater stability and positive energy to a world undergoing profound transformation and turbulence.

          China-Africa friendship and cooperation stand as a vivid testament to this vision. The year 2026 marks the 70th anniversary of the establishment of diplomatic relations between China and African countries, and has also been designated the China-Africa Year of People-to-People Exchanges.

          Over the past seven decades, China and Africa have remained committed to the principles of sincerity, real results, amity and good faith, as well as the approach of pursuing the greater good and shared interests, forging a path of mutually beneficial cooperation. Bilateral trade reached US$348 billion in 2025, and China has remained Africa’s largest trading partner for 17 consecutive years. From the Mombasa–Nairobi Standard Gauge Railway and cross-border telecommunications networks to the promotion of Juncao technology and numerous “small yet beautiful” projects such as water wells and rural water supply systems, China-Africa cooperation has delivered tangible benefits to the lives of African people.

          On May 1st, China started granting zero-tariff treatment on 100 percent of tariff lines to all 53 African countries with which it has diplomatic relations, further opening its market and sharing development opportunities with Africa. More recently, following the outbreak of a new Ebola epidemic, China promptly provided emergency humanitarian assistance to the affected countries and the African Union, once again demonstrating the true meaning of the all-weather China-Africa community with a shared future for the new era.

          At present, under the leadership of the CPC, the Chinese people are steadily advancing toward the goals of basically realizing socialist modernization by 2035 and building China into a great modern socialist country in all respects by the middle of the century. On this new journey, China-Africa cooperation enjoys even broader prospects. China will continue to support Africa in implementing Agenda 2063 and deepen cooperation in such areas as industrialization, agricultural modernization, infrastructure development, green energy, the digital economy, public health and youth development, helping Africa achieve independent and sustainable development. China will also continue to work with Africa and other developing countries to promote greater representation and a stronger voice for the Global South in international affairs, and to make the international order more just and equitable.

          History has shown that solidarity is the key to overcoming challenges, while independence is essential to shaping one’s own future. The CPC’s 105 years of struggle have also demonstrated that any country can achieve development and national rejuvenation by staying true to its founding mission, remaining firmly rooted in its people, and pursuing a development path suited to its own national conditions.

          China and Africa share similar historical experiences and common aspirations for development. More than ever, we should stand together, firmly keep our future in our own hands, and work to deliver even greater outcomes through the all-weather China-Africa community with a shared future for the new era—bringing greater benefits to our peoples and making new contributions to the progress of humanity.

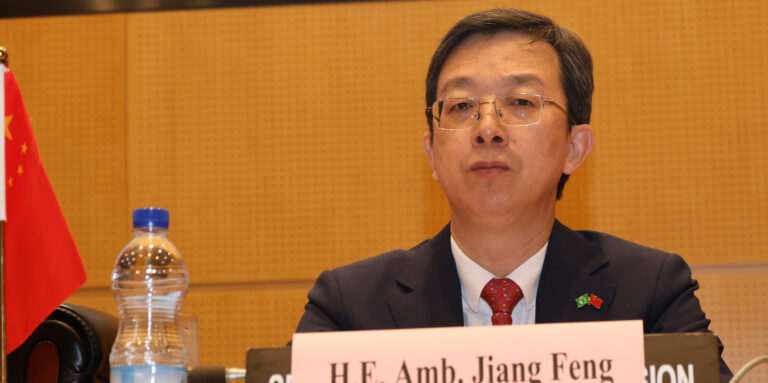
Ambassador JIANG Feng is Head of Mission of China to the AU and Representative of China to the UNECA

Role of ethics and technology in building efficient and trustworthy tax system

0

An effective tax system is the backbone of government finance and national development. However, the success of a tax system should not be measured solely by the amount of revenue collected. Equally important is the efficiency with which taxes are collected and the degree to which taxpayers perceive the system as fair and transparent.

A widely used indicator of tax administration efficiency is the Cost of Collection Ratio (CCR), which measures the amount spent by a tax authority to collect tax revenue. Many tax administrations face challenges related to the potential for undue influence or corruption in the assessment process. As governments embrace digital transformation, technology and artificial intelligence (AI) are increasingly used to reduce administrative costs, improve compliance, and minimize direct interactions between taxpayers and tax officials—thereby limiting opportunities for unethical practices.

The cost of tax collection refers to the total expenditure incurred by a tax authority in administering, assessing, and collecting taxes. These costs include employee salaries, office operations, taxpayer education, audits, and IT systems.

Tax professionals calculate the Cost of Collection Ratio (CCR) as (Total Tax Administration Costs divided by Total Tax Revenue Collected) × 100.

Based on the calculation, internationally approved rates indicate that a CCR below 1% is considered as highly efficient, while 1–2% is efficient. Be that as it may ratios between 2–3% are acceptable for developing countries facing several administrative challenges. Ratios exceeding 5% often signal inefficiencies requiring further investigation.

However, a low ratio alone does not indicate an effective tax system. A tax authority that cuts enforcement may reduce costs in the short term while losing substantial revenue due to increased evasion. Therefore, the objective should be an optimal balance between administrative costs, revenue generation, and taxpayer compliance.

In this regard one thing to be considered is the challenge of discretionary power in tax assessment. In many tax administrations, individual assessors possess significant authority in determining taxable income, evaluating deductions, imposing penalties, and selecting audits. While professional judgment is sometimes necessary, excessive discretion can undermine confidence in the tax system.

When taxpayers believe their liabilities depend more on individual officials than on objective legal standards, opportunities arise for informal negotiations, favoritism, and corruption. Such situations reduce public trust and discourage voluntary compliance.

The challenge for modern tax administration is to reduce unnecessary human discretion while preserving fairness and professional oversight. As has been indicated in Ethiopia’s Tax Administration Proclamation No. 983/2016, tax officers are required to be honest and fair, to avoid conflicts of interest, and maintain taxpayer confidentiality.

All in all, strengthening ethical frameworks is essential. Tax officials should be guided by principles of integrity, impartiality, and professional competence. Regular ethics training and strict disciplinary measures help maintain public confidence.

Professional capacity is equally important. Tax assessors should receive ongoing training in taxation, accounting, information systems, and taxpayer rights. Staff rotation policies can also reduce the risk of long-term relationships developing between officials and taxpayers. Independent internal audit units should regularly review assessments to ensure compliance with established procedures.

Reducing assessor influence in particular requires investment—in training, digital infrastructure, cybersecurity, and institutional reforms. Although these investments may increase administrative costs in the short term, international experience demonstrates that they often produce significant long-term benefits: improved compliance, limited personal contacts, higher revenue collection, and lower administrative burdens.

Spending on modernization, in this regard should not be viewed as a cost but as an investment in better governance. Because, the transformative role of information technology and AI is immense.

IT has become one of the most effective tools for reducing direct contact between taxpayers and tax officials. Electronic registration systems eliminate manual procedures and improve record accuracy. Online filing platforms and electronic payment systems reduce cash-related transactions and create transparent transaction records.

Integrated databases enable tax authorities to verify information using data from banks, customs, employers, business licensing agencies, and land registries. Such systems reduce dependence on subjective judgments and improve assessment accuracy. By standardizing procedures and creating electronic audit trails, technology helps ensure consistent treatment of taxpayers.

AI represents the next stage in tax administration reform. AI systems can analyze large volumes of data, identify unusual patterns, and support evidence-based decision-making. They can select audit cases through risk-based models, detect doubtful transactions, identify potential fraud, and compare taxpayer declarations with industry benchmarks and third-party information. AI-powered virtual assistants can provide taxpayers with consistent information, reducing dependence on individual officers.

Despite those advantages, AI is not a complete substitute for human judgment. Effective implementation requires strong governance, reliable data, cyber-security safeguards, and legal protections for taxpayer privacy.

Several countries provide useful examples of how technology and institutional reforms can improve tax administration efficiency.

For example, in the United Kingdom, HM Revenue and Customs has implemented extensive digital services through its “Making Tax Digital” initiative, reducing direct interactions between taxpayers and officials.

In Japan, the National Tax Agency emphasizes professionalism, taxpayer education, and electronic filing, contributing to strong voluntary compliance.

While the Ghana Revenue Authority’s digital reforms have significantly reduced opportunities for informal negotiations, the South African Revenue Service, widely regarded as one of Africa’s most advanced tax administrations, uses automated assessments and sophisticated data analytics to minimize manual intervention.

With this background, the author of this article believes that improving tax administration efficiency in Ethiopia requires a comprehensive reform strategy combining ethical standards, professional development, technological modernization, and institutional accountability.

Short-term priorities should include strengthening ethics programs, improving staff training, implementing staff rotation policies, and enhancing internal oversight mechanisms.

Medium-term reforms should focus on expanding electronic filing, electronic payment platforms, integrated taxpayer databases, and risk-based audit selection methods.

Long-term objectives should include the adoption of AI, automated assessments, predictive analytics, and advanced data-matching technologies.

In general, the future of effective tax administration lies in reducing dependence on individual discretion and increasing reliance on transparent rules, professional standards, accurate data, and modern technology. While investments in reform may initially increase administrative costs, international experience demonstrates that such expenditures ultimately improve efficiency, increase revenue, strengthen public trust, and reduce opportunities for dishonesty.

A successful tax system is not simply one that collects more revenue. It is the one that collects revenue fairly, efficiently, transparently, and at a reasonable cost to both government and taxpayers. In the digital age, IT and AI provide powerful tools for achieving these objectives.

ficient and Trustworthy Tax System

An effective tax system is the backbone of government finance and national development. However, the success of a tax system should not be measured solely by the amount of revenue collected. Equally important is the efficiency with which taxes are collected and the degree to which taxpayers perceive the system as fair and transparent.

A widely used indicator of tax administration efficiency is the Cost of Collection Ratio (CCR), which measures the amount spent by a tax authority to collect tax revenue. Many tax administrations face challenges related to the potential for undue influence or corruption in the assessment process. As governments embrace digital transformation, technology and artificial intelligence (AI) are increasingly used to reduce administrative costs, improve compliance, and minimize direct interactions between taxpayers and tax officials—thereby limiting opportunities for unethical practices.

The cost of tax collection refers to the total expenditure incurred by a tax authority in administering, assessing, and collecting taxes. These costs include employee salaries, office operations, taxpayer education, audits, and IT systems.

Tax professionals calculate the Cost of Collection Ratio (CCR) as (Total Tax Administration Costs divided by Total Tax Revenue Collected) × 100.

Based on the calculation, internationally approved rates indicate that a CCR below 1% is considered as highly efficient, while 1–2% is efficient. Be that as it may ratios between 2–3% are acceptable for developing countries facing several administrative challenges. Ratios exceeding 5% often signal inefficiencies requiring further investigation.

However, a low ratio alone does not indicate an effective tax system. A tax authority that cuts enforcement may reduce costs in the short term while losing substantial revenue due to increased evasion. Therefore, the objective should be an optimal balance between administrative costs, revenue generation, and taxpayer compliance.

In this regard one thing to be considered is the challenge of discretionary power in tax assessment. In many tax administrations, individual assessors possess significant authority in determining taxable income, evaluating deductions, imposing penalties, and selecting audits. While professional judgment is sometimes necessary, excessive discretion can undermine confidence in the tax system.

When taxpayers believe their liabilities depend more on individual officials than on objective legal standards, opportunities arise for informal negotiations, favoritism, and corruption. Such situations reduce public trust and discourage voluntary compliance.

The challenge for modern tax administration is to reduce unnecessary human discretion while preserving fairness and professional oversight. As has been indicated in Ethiopia’s Tax Administration Proclamation No. 983/2016, tax officers are required to be honest and fair, to avoid conflicts of interest, and maintain taxpayer confidentiality.

All in all, strengthening ethical frameworks is essential. Tax officials should be guided by principles of integrity, impartiality, and professional competence. Regular ethics training and strict disciplinary measures help maintain public confidence.

Professional capacity is equally important. Tax assessors should receive ongoing training in taxation, accounting, information systems, and taxpayer rights. Staff rotation policies can also reduce the risk of long-term relationships developing between officials and taxpayers. Independent internal audit units should regularly review assessments to ensure compliance with established procedures.

Reducing assessor influence in particular requires investment—in training, digital infrastructure, cybersecurity, and institutional reforms. Although these investments may increase administrative costs in the short term, international experience demonstrates that they often produce significant long-term benefits: improved compliance, limited personal contacts, higher revenue collection, and lower administrative burdens.

Spending on modernization, in this regard should not be viewed as a cost but as an investment in better governance. Because, the transformative role of information technology and AI is immense.

IT has become one of the most effective tools for reducing direct contact between taxpayers and tax officials. Electronic registration systems eliminate manual procedures and improve record accuracy. Online filing platforms and electronic payment systems reduce cash-related transactions and create transparent transaction records.

Integrated databases enable tax authorities to verify information using data from banks, customs, employers, business licensing agencies, and land registries. Such systems reduce dependence on subjective judgments and improve assessment accuracy. By standardizing procedures and creating electronic audit trails, technology helps ensure consistent treatment of taxpayers.

AI represents the next stage in tax administration reform. AI systems can analyze large volumes of data, identify unusual patterns, and support evidence-based decision-making. They can select audit cases through risk-based models, detect doubtful transactions, identify potential fraud, and compare taxpayer declarations with industry benchmarks and third-party information. AI-powered virtual assistants can provide taxpayers with consistent information, reducing dependence on individual officers.

Despite those advantages, AI is not a complete substitute for human judgment. Effective implementation requires strong governance, reliable data, cyber-security safeguards, and legal protections for taxpayer privacy.

Several countries provide useful examples of how technology and institutional reforms can improve tax administration efficiency.

For example, in the United Kingdom, HM Revenue and Customs has implemented extensive digital services through its “Making Tax Digital” initiative, reducing direct interactions between taxpayers and officials.

In Japan, the National Tax Agency emphasizes professionalism, taxpayer education, and electronic filing, contributing to strong voluntary compliance.

While the Ghana Revenue Authority’s digital reforms have significantly reduced opportunities for informal negotiations, the South African Revenue Service, widely regarded as one of Africa’s most advanced tax administrations, uses automated assessments and sophisticated data analytics to minimize manual intervention.

With this background, the author of this article believes that improving tax administration efficiency in Ethiopia requires a comprehensive reform strategy combining ethical standards, professional development, technological modernization, and institutional accountability.

Short-term priorities should include strengthening ethics programs, improving staff training, implementing staff rotation policies, and enhancing internal oversight mechanisms.

Medium-term reforms should focus on expanding electronic filing, electronic payment platforms, integrated taxpayer databases, and risk-based audit selection methods.

Long-term objectives should include the adoption of AI, automated assessments, predictive analytics, and advanced data-matching technologies.

In general, the future of effective tax administration lies in reducing dependence on individual discretion and increasing reliance on transparent rules, professional standards, accurate data, and modern technology. While investments in reform may initially increase administrative costs, international experience demonstrates that such expenditures ultimately improve efficiency, increase revenue, strengthen public trust, and reduce opportunities for dishonesty.

A successful tax system is not simply one that collects more revenue. It is the one that collects revenue fairly, efficiently, transparently, and at a reasonable cost to both government and taxpayers. In the digital age, IT and AI provide powerful tools for achieving these objectives.
Solomon Tolosa

0

2. Education: (የት/ት ደረጃ)Level 4 Engineering

3. Company name: (የመስሪያ ቤቱ ስም)Mama’s Machinery

4. Title: (የስራ ድርሻህ)Manager.

5.Founded in: (መቼ ተመሰረተ)2023

6. What it does: (ምንድነው የሚሰራው)Manufacturing simple and various types of machinery

7. Headquarters: (ዋና መስሪያ ቤት)Addis Ababa

8. Start-up capital: (በምን ያህል ገንዘብ ስራዉን ጀመርሽ/ክ)110,000 birr

9. Current capital: (የአሁን ካፒታል)growing

10. Number of employees: (የሰራተኞች ቁጥር)5

11. Reason for starting the business: (ለስራው መጀመር ምክንያት)To  provide affordable, locally-made machinery

12. Biggest perk of ownership: (የባለቤትነት ጥቅም)The freedom to innovate

13. Biggest strength: (ጥንካሬህ/ሽ)Technical problem-solving skills

14. Biggest challenge: (ተግዳሮት)Shortage of working space

15. Plan: (እቅድ)Expanding my workshop to other parts of the country1. First career path: (የመጀመሪያ ስራ)None2. Most interested in meeting: (ማግኘት የምትፈልጊ/ገው ሰው)Successful local industrialists3. Most admired person: (የምታደንቂ/ቀው ሰው)Engineer Bejai Naiker4. Stress reducer: (ጭንቀትን የሚያቀልልሽ/ለህ)Listening to spiritual songs5. Favorite book: (የመፅሐፍ ምርጫ)None6. Favorite pastime: (ማድረግ የሚያስደስትህ)Dismantling and learning about old mechanical parts7. Favorite destination to travel to: (ከኢትዮጵያ ውጪ መሄድ የምትፈልጊ/ገዉ ስፍራ)Germany8. Favorite automobile: (የመኪና ምርጫ)BMW

Gold and coffee deepen dominance as Ethiopia’s export basket remains narrow

0

Despite achieving record export earnings in the 2025/26 fiscal year, Ethiopia’s export sector remains heavily concentrated in just two commodities — gold and coffee — underscoring the country’s continued struggle to diversify its foreign exchange sources.

The fiscal year, which ended on Tuesday, is expected to generate more than 11 billion dollars in export revenue, surpassing the government’s 9.8 billion dollar target and rising sharply from 8.3 billion dollars in the previous fiscal year.

However, the record performance was overwhelmingly driven by gold and coffee, which together generated 8.6 billion dollars, accounting for 78.2 percent of the country’s total export earnings. Their combined share increased from 73.5 percent a year earlier, indicating that Ethiopia’s export base has become even more concentrated despite years of policy efforts to diversify exports.

Gold remained the country’s largest foreign exchange earner, generating nearly 5.5 billion dollars, or about half of total export receipts. The figure represents a 62 percent increase from 3.4 billion dollars in the previous fiscal year.

Prime Minister Abiy Ahmed described the achievement as unprecedented, noting that Ethiopia exported 5.5 billion dollars worth of gold in a single fiscal year, exceeding the cumulative 3.7 billion dollars generated during the 27 years before his administration took office in 2018.

Coffee retained its position as the second-largest export commodity, earning 3.1 billion dollars, up 19 percent from 2.6 billion dollars in 2024/25.

The figures illustrate that Ethiopia’s export growth continues to depend largely on primary commodities, leaving the economy vulnerable to fluctuations in global commodity prices, production levels and external demand. While the government has repeatedly identified export diversification as a strategic priority, non-traditional export sectors continue to contribute only a modest share of total foreign exchange earnings.

Officials attributed the surge in gold exports to macroeconomic reforms introduced in July 2024, saying the measures reduced contraband trade and encouraged producers to export through official channels.

Meanwhile, the government hopes manufacturing will gradually reduce the country’s dependence on commodity exports. Prime Minister Abiy said Ethiopia aims to increase manufacturing exports to 1 billion dollars in the new fiscal year, up from 370 million dollars in 2024/25, as part of broader efforts to expand the country’s export base.

Manufacturing Shows Momentum

Beyond export targets, the government reported robust growth across the industrial sector during the 2025/26 fiscal year, reinforcing its ambition to make manufacturing a larger contributor to economic growth and foreign exchange earnings.

Prime Minister Abiy told lawmakers that Ethiopia has intensified its import substitution program, which he said has now reached an estimated 5 billion dollars in value by replacing imported industrial products with locally manufactured goods.

According to the prime minister, the manufacturing sector expanded by 20.3 percent during the fiscal year, while mining registered an even stronger 24 percent growth, supported by higher gold production and exports.

The construction materials industry also posted notable gains. Cement production increased by 26 percent, while electricity consumption by manufacturers rose by 16 percent, reflecting growing industrial activity. Abiy also highlighted improved output in the steel, glass and ceramic tile industries as evidence of expanding domestic manufacturing capacity.

Looking ahead, the government projects the industrial sector will grow by 12.7 percent during the 2026/27 fiscal year, driven by continued investment, industrial park expansion and policies aimed at boosting domestic production and exports.

Services, Investment and Remittances

The services sector remained another major pillar of the economy, recording 9.8 percent growth during the fiscal year.

Ethiopian Airlines continued to anchor the sector, transporting approximately 17 million international passengers and 4 million domestic passengers, further strengthening its role as one of Africa’s leading aviation hubs.

According to the government’s presentation, the services sector generated approximately 9.5 billion dollars in foreign exchange earnings during the year.

Ethiopia also attracted 4 billion dollars in foreign direct investment (FDI), while remittance inflows reached 7.9 billion dollars, reflecting continued confidence among investors and the Ethiopian diaspora despite global economic uncertainty.

In addition, the country secured about 5 billion dollars in grants and external loans to finance development programs and infrastructure projects.

Overall, Ethiopia received an estimated 38 billion dollars in total foreign capital inflows during the fiscal year, an 18.4 percent increase compared with the previous year.

The government estimates the economy expanded by 10.2 percent during the 2025/26 fiscal year, supported by broad-based growth across agriculture, industry and services.

Inflation featured prominently in the prime minister’s annual address to Parliament.

Abiy acknowledged that Ethiopia’s steady progress in bringing inflation under control had been interrupted by external developments, particularly geopolitical tensions in the Middle East.

He said the conflict involving Iran, the United States and Israel disrupted international markets, reversing the country’s gradual decline in inflation and pushing price growth back into double-digit territory. Nevertheless, the government expects inflationary pressures to ease as external conditions stabilize and ongoing macroeconomic reforms take further effect.

Politics

On regional security, Prime Minister Abiy accused Eritrea of attempting to reignite conflict in northern Ethiopia by encouraging renewed hostilities in the Tigray region.

Addressing Parliament, he said the Ethiopian government remains committed to preserving peace despite growing military tensions along the northern frontier.

“The Ethiopian government prefers peace,” Abiy told lawmakers. “However, the Eritrean government is working to create conditions for war to re-emerge in the Tigray region.”

He urged leaders of the Tigray People’s Liberation Front (TPLF) to learn from previous conflicts and avoid actions that could undermine the fragile peace established under the Pretoria Peace Agreement.

Abiy said Ethiopia’s military preparedness is intended to deter external threats rather than initiate conflict.

“Our military readiness is directed against external actors seeking to use the TPLF and other forces to destabilize the country,” he said.

The prime minister also alleged that the TPLF has become involved in Sudan’s ongoing civil war between the Sudan Armed Forces (SAF), led by Lieutenant General Abdel Fattah al-Burhan, and the Rapid Support Forces (RSF).

According to Abiy, young people from Ethiopia’s Tigray region have been compelled to participate in the conflict alongside forces aligned with the SAF. The allegations have not been independently verified.

Meanwhile, international organizations and foreign governments have continued to warn about the deteriorating security situation in northern Ethiopia, cautioning that renewed fighting could trigger another humanitarian crisis. They have called on all parties to resolve their differences through dialogue and uphold the commitments made under the Pretoria Peace Agreement.

Human Rights Watch (HRW) has also expressed concern over alleged forced recruitment by Tigrayan forces. In a recent report, the rights organization said Tigrayan fighters and local officials have allegedly recruited civilians, including children as young as 15, since at least April 2026.

According to HRW, former combatants, men and boys were reportedly taken from homes, workplaces, streets and artisanal gold-mining sites across the Tigray region. The organization said its findings were based on interviews conducted in June with 18 witnesses, relatives of those recruited, and individuals who said they had escaped or evaded recruitment.

The allegations have added to growing international concern over the security and humanitarian situation in northern Ethiopia as diplomatic efforts continue to focus on preventing renewed conflict and preserving the gains achieved under the Pretoria Peace Agreement.