Thursday, October 15, 2026
Home Blog Page 40

NBE’s transition to interest rate-based policy framework: Pitfalls and limitations

0

After a regular Monetary Policy Committee meeting in July 2026, the National Bank of Ethiopia (NBE) issued a press release to announce its “successful transition” from money-focused to interest rate-based monetary policy regime – Action Plan #1 in its Strategic Plan for 2023-26. “Full implementation” of indirect monetary instruments was also declared. And as this means retiring direct control via credit policy, the credit ceiling imposed on commercial banks since August 2023 in an attempt to reduce inflationary pressures was lifted. But since the NBE wanted to retain a tight policy stance and “restore inflation to single-digit levels over the medium term,” it raised its target for the policy rate, aka the national bank rate, by 100 basis points from 15 to 16% – notwithstanding the question mark over whether this rate was initially set to be consistent with inflation and growth goals. Nonetheless, while the policy regime change is undoubtedly historic, important questions are left unsettled, especially that of whether monetary policy shocks can now percolate quickly and effectively throughout the financial system and the economy.  

First of all, what exactly is the NBE’s new operational framework? The short-term interest rate in the interbank money market is the NBE’s operating target. In other words, the so-called national bank rate is just a target for the interbank rate. And having exited its habitual accommodative policy stance, the central bank has now adopted a corridor-type system for conducting monetary policy. To this end, the NBE has set up standing lending (discount) and deposit facilities. And so, it stands ready to lend overnight any amount banks want at 300 basis points above the announced target policy rate, while it is willing to hold their deposits of excess reserves at 300 basis points below the said target. Then the implied penalty-and-incentive mechanism, combined with banks’ rational behavior, is expected – or rather hoped – to stabilize the average, overnight interbank rate near its target set in the middle of the “corridor” formed by the two standing facilities. If not, the NBE would adjust the supply of reserves primarily through market operations so as to steer the interbank rate toward the chosen target.

As is well known, there are pros and cons of a corridor operational system. The potential benefits include enabling the NBE to set overnight, interbank interest rates irrespective of the demand for reserves and encouraging tight liquidity management on the part of banks as well as greater interbank market activity. But the newly adopted system has two important disadvantages. First, because a match between the NBE’s supply of reserves and a demand that becomes increasingly volatile and difficult to predict with expansion of nonbank finance and electronic/digital payment systems is unlikely, the interbank rate is bound to fluctuate around its target, probably requiring more frequent market operations. Second, a corridor system – in which central banks create a “structural shortage” of bank reserves to a level where the target policy rate clears the overnight interbank market (thus eliminating the excess reserves that rendered our interbank market inactive during the monetary targeting regime) – raises the risk of intermittent liquidity shortages in the banking system, which may obstruct monetary transmission.

Additionally, whether the NBE has chosen an optimal width for the interest rate corridor is up for debate. Major central banks have traditionally had a corridor 200 basis points wide. By contrast, the NBE has preferred a much wider corridor with 600 basis points. Clearly, this allows too large a deviation from the target overnight policy rate, meaning less precise implementation of a desired monetary policy stance. 

Turning to the announced shift from direct to indirect policy instruments, which should be used with a view to achieving the NBE’s operational target, it naturally follows a move to implement a basic interbank money market free from interest rate controls, an organized securities exchange, and regular open market operations. However, what constitutes an indirect instrument is sometimes in the eye of the beholder, and the NBE’s take is as yet unknown. For example, does the NBE envisage it to comprise statutory liquid asset requirements of commercial banks? If it does, and that were to force banks to hold more Treasury bills as part of their liquid asset holdings, what we would get in effect is not a monetary instrument but rather a selective credit instrument that is used to channel credit to the government, distorting the pattern of credit allocation and determination of interest rates. 

In addition, a transition from direct to indirect control of monetary policy is supposed to denote increased reliance on market forces, and away from directives. And whether the NBE can and will indeed rely on market-based indirect instruments, rather than on statutory indirect instruments (such as reserve requirements), is an open question. The scope for conventional open market operations remains limited until there is a sufficiently deep secondary market. Still, the NBE can and does, in fact, conduct “open market-type operations” in the primary market, using an auction system. But what is expected here under a corridor system is that the NBE sells more or less government securities (Treasury bills) than those maturing so as to effect the liquidity provision change necessary to hit the target interest rate. The practical question is: Can the NBE realistically set the volume of government-bill sales and determine the allocation of proceeds based solely on monetary criteria when the federal government, weighing in with its deficit financing needs, actually has a constitutional right to “formulate and execute” monetary policy?

So it is important to acknowledge that, until markets are fully developed, statutory measures might indeed be required to absorb or inject liquidity and thereby achieve monetary control. But in that case the NBE should stay away from pretence or equivocation, and instead provide a transparent explanation.

Speaking of which, the NBE has announced that it will implement extra, selective reserve requirements based on individual banks’ loan-to-deposit ratio. But nobody knows when and how this will be administered. And banks are understandably hysterical at the prospect of applying this tool as it may require substantial portfolio adjustments for them. The stated trigger clause “in case credit expansion poses pressure on inflation path” is too vague and open-ended to stimulate confidence in the instrument. Beyond this, non-interest-bearing reserve requirements are known to increase banks’ effective cost of funds, and the required reserve ratio is currently high at 10%. If the NBE is really intending to raise them further, it should surely consider remunerating them, or they will have distortive effects à la direct controls, and even more so when applied unequally.

Most importantly, perhaps, the idea that the NBE can tweak the money supply and interest rates by varying reserve requirements across banks is far-fetched. So why create a gratuitous liquidity management problem for banks, against the very advantage of a corridor-style framework, which is strengthening banks’ liquidity management? In fact, tinkering and trial-and-error fiddling with reserve requirements can also inflame interest rate volatility in the interbank market.

Ultimately, of course, the effectiveness of the NBE’s interest rate policy and its instruments will be measured by the strength and speed of the transmission of monetary policy to economic activity and inflation. And the medium-term prospects here are bleak. First, there is little chance that setting a target for the NBE’s policy rate affects interest rates “throughout” the economy. Even at a conceptual level, the transmission of policy rates to bank rates under a corridor system is far from assured. The transmission to interbank and loan rates can be weak when the interbank market is not very efficient. And our banks have typically been unconcerned about the policy rate while setting their lending rates. As for the transmission to bank deposit rates, it may well depend on banks’ liquidity positions. But the average savings-deposit rate remains stuck at around 8%, in a way reminiscent of collusion in the banking industry. Add in the fact that the real deposit rate is almost always negative, and the link with financial savings is effectively broken.

Let us suppose for the sake of argument that the NBE really does manage to hit the target interest rate and thereby affect the availability and cost of credit within the banking sector. The pass-through to the volume of bank lending is still uncertain, not least because it depends on banks’ own risk appetite. And the pass-through of borrowing costs onto aggregate demand is even more uncertain, partly because our consumption spending is less credit-dependent and thus less interest rate-sensitive. For example, few of our households take out mortgage, car or credit card loans. As far as business is concerned, a percentage point rise in bank lending rate is highly unlikely to restrain a largely interest-unresponsive credit demand from the private sector, which has become accustomed to borrowing at a staggering average rate of 15.8% and even much higher in effective terms. Besides, other asset price channels for monetary policy effects such as foreign exchange and equities (stocks) are not yet active.

In short, even though the NBE has raised its target policy rate from 15 to 16% in a supposedly counterbalancing act, expecting disinflation through weaker demand for goods and services, and thereby increased unemployment, is patently unrealistic. This, in turn, means that if and when disinflation occurs (I mean, no inflation lasts forever, right?), there will be non-monetary factors to take most of the credit.      

So the moral of this story is that the NBE’s maiden corridor operational framework, for all its symbolism of modernity, will not be substantively relevant to the real economy for years at best. For the truth is that the employed corridor system means less precise control over the interbank interest rate, and robust or widespread transmission of the signals provided by changes in the target policy rate requires many years of financial, economic and institutional transformation.

But make no mistake: nobody can really begrudge the NBE revising its policy framework in the right direction and developing its institutional standing – because it needs it for the day when, at long last, monetary policy really matters for ultimate economic outcomes.
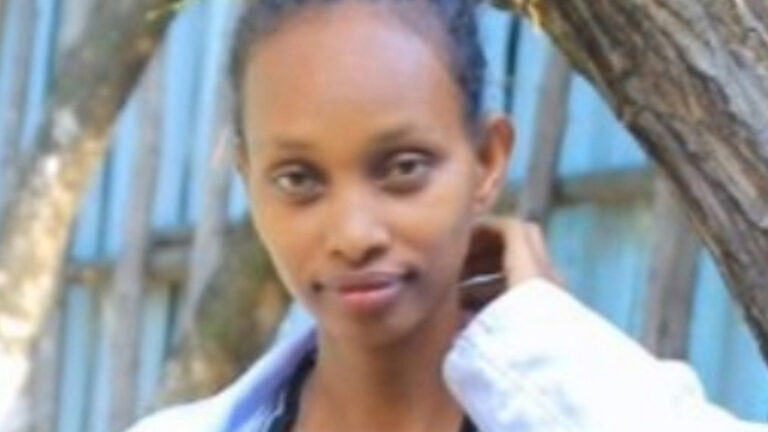
Redit Alemu

0
  1. Education: (የት/ት ደረጃ)
  2. BA in Marketing
  3. 3. Company name: (የመስሪያ ቤቱ ስም)
  4. Re Advertising and Printing
  5. 4. Title: (የስራ ድርሻህ)
  6. Co-Founder
  7. 5. Founded in: (መቼ ተመሰረተ)
  8. 2025
  9. 6. What it does: (ምንድነው የሚሰራው)

Providing professional advertising and printing services
7. Headquarters: (ዋና መስሪያ ቤት)  

   Hawassa
8. Start-up capital: (በምን ያህል ገንዘብ ስራዉን ጀመርሽ/ክ)
158,000 birr
9. Current capital: (የአሁን ካፒታል )

    Growing

10. Number of employees: (የሰራተኞች ቁጥር)

      2

11. Reason for starting the business: (ለስራው መጀመር ምክንያት)

    To bridge the gap in quality branding

12. Biggest perk of ownership: (የባለቤትነት ጥቅም) 
Bringing creative ideas to life
13. Biggest strength: (ጥንካሬህ/ሽ) 

Strong customer handling skills
14. Biggest challenge: (ተግዳሮት)

   Shortage of advanced printing machinery

15. Plan: (እቅድ)

To expand our printing facility

16. First career path: (የመጀመሪያ ስራ)
Sales

17. Most interested in meeting: (ማግኘት የምትፈልጊ/ገው ሰው)
None
18. Most admired person: (የምታደንቂ/ቀው ሰው) 

Entrepreneurs Gashaw Kassu

19. Stress reducer: (ጭንቀትን የሚያቀልልሽ/ለህ)

Listening to gospel music
20. Favorite book: (የመፅሐፍ ምርጫ)

   Bible

21. Favorite pastime: (ማድረግ የሚያስደስትህ)

Reading inspirational books

22. Favorite destination to travel to: (ከኢትዮጵያ ውጪ መሄድ የምትፈልጊ/ገዉ ስፍራ) Canada

23. Favorite automobile: (የመኪና ምርጫ)

  Toyota RAV4

Can Ethiopia get mortgage refinancing right? Lessons from Kenya, Tanzania and Egypt

0

On September 3, 2026, the National Bank of Ethiopia and the International Finance Corporation signed a cooperation agreement to establish the country’s first Mortgage Refinancing Company (MRC), with an initial capital injection of Br 100 billion and IFC contributing US$ 200 million. Ethiopia is not the first country to bet on a mortgage refinancing company and will not be the last to discover that liquidity alone doesn’t build a mortgage market. A few African countries, including Kenya, Tanzania, and Egypt, have each invested in mortgage refinance systems for over a decade, creating valuable learning opportunities for the latecomer Ethiopia. Lessons from these countries show that establishing a refinancing company is a bet, not a guarantee, and depends on macroeconomic and political stability, a well-developed primary mortgage and bond market, and affordability design as key ingredients for the success of Ethiopia’s MRC.

The Egyptian Mortgage Refinancing Company (EMRC) case teaches Ethiopia that a refinancing company can’t outperform the financial and political system it sits inside. In its three-year operation from 2008 to 2011, EMRC enabled an increase in mortgage origination by Primary Mortgage Lenders (PML), initiated policy and regulatory reforms (e.g., mortgage laws), strengthened public agencies including the central bank, and increased the participation of mortgage finance companies. However, its performance was considered unsatisfactory when measured against the set goals: overall growth of the mortgage market and issuance of mortgage-backed securities within two years of its operation.  An independent evaluation reported that in its early days, EMRC faced significant challenges that hindered its proper functioning, notably weak macroeconomic conditions, an underdeveloped bond market with no institutional investors capable of buying its bonds, and the Arab Spring’s political turmoil, which disrupted every part of the financial system at once. The lesson for Ethiopia is that MRC’s success is not self-contained. It requires enabling conditions, including macroeconomic and political stability, and a well-functioning domestic bond market, with institutional investors ready to absorb its bonds. This creates a clear exit path to capital market funding within a short period of its operation. Otherwise, it risks using initial funds intended only as a bridge to get started as a permanent solution and stalling, as EMRC did in its early days of operation.

The Tanzanian case illustrates what can’t be assumed: liquidity availability doesn’t matter if banks become reluctant to use the facility. After the Tanzanian Mortgage Refinance Company (TMRC) began operating, it was found that conservative Tanzanian banks were unwilling to hold mortgage loans even for a short period (i.e., until it became eligible for refinancing) due to fears of maturity mismatch, interest rate fluctuation, and opportunity cost of tying up funds that could otherwise be used for more profitable short-term lending. To address the commercial incentive problem and encourage more banks to enter the market, the TMRC was restructured in 2012 to incorporate pre-financing alongside refinancing, with a 5% concessionary discount loan for PML before those banks had accumulated a mortgage portfolio large enough to qualify for refinancing, giving them a reason to originate mortgages in the first place rather than waiting for a large, risk-bearing portfolio to build up first.  This attracted Tanzanian banks to engage in mortgage origination and enabled them to accumulate sufficient mortgage portfolios for refinancing eligibility. TMRC also took additional measures to ensure its long-term sustainability by issuing bonds that attracted both domestic and international institutional investors, including the IFC. At the same time, it worked to make mortgages more affordable for low- and middle-income groups through a partnership with Habitat for Humanity. These structural adjustments enabled the growth of the mortgage market in Tanzania, with mortgage providers increasing from just three in 2010 to 31 in 2025, thereby opening competition and leading to a gradual decline in interest rates and extension of maturity periods from a maximum of 7 years to up to 25 years. The lesson for Ethiopia is that Ethiopian banks may be no more willing to hold mortgage risks than their Tanzanian counterparts. Hence, the proposed refinancing company should sharply reduce the mandatory holding period to meet basic eligibility criteria for refinancing or offer an immediate refinancing option for well-performing mortgage loans. The pre-financing arrangement implemented in Tanzania, whereby direct concessionary lending to banks occurs before the establishment of a refinancing company, offers a valuable lesson in this regard, as it enables Ethiopian banks to accumulate a sufficient mortgage portfolio to be eligible for later refinancing.

The Kenyan Mortgage Refinancing Company’s (KMRC) lesson is one the other two cases cannot offer, as it shows what happens when affordability is designed in from the start, rather than left to catch up after the backend has already been fixed, as in Egypt and Tanzania. KMRC was designed with two products: one targeting affordable housing loans capped between KShs 3-4 million and a 7% interest rate, and the other market-based mortgage loans. For the affordable segment, it provides concessional loans to PML, which will then be transferred to borrowers, making mortgages affordable for middle- and low-income groups. In addition, SACCOs, which are the major players in low-income segment housing finance, are also included in the refinancing scheme, enabling mortgage access for marginalized groups. The KMRC also went further to establish the Kenyan Mortgage Guarantee Trust (KMGT), offering partial guarantees to lenders serving informally employed borrowers, a group conventional underwriting routinely excludes. Despite these measures, the uptake of PML was minimal, primarily due to a shortage of housing supply, mortgage costs, and lack of consumer awareness, a reminder that even well-designed affordability rules cannot substitute for adequate housing stock. The KMRC case teaches Ethiopia a valuable lesson in incorporating affordability as an eligibility criterion early on with income-capped or rate-discounted approaches and deliberate inclusion of SACCOs and MFIs.  It also highlights the importance of affordable housing supply, enhancing developer finance, and raising awareness about the MRC’s products, among other key lessons.

In sum, Ethiopia is not choosing whether to build a mortgage refinancing company, as that decision is already made. What remains open is whether it gets the sequencing right: a stable enough financial system for Egypt’s mistake not to repeat itself, a bank incentive structure that Tanzania had to learn the hard way, and an affordability mandate that Kenya proved is possible to design in from day one. Getting any one of these wrong would not sink the institution outright, but getting all three right, together and early, is what would separate Ethiopia’s outcome from a decade-old regional pattern of underperformance. These key measures are in addition to the holistic readjustment needed across the value chain, including construction and developer financing, property valuation infrastructure, a strong credit information system, targeted support to specialized mortgage banks that took the risk and started operating and accelerating the formulation of a mortgage regulatory framework that hindered the the operation of existing specialized mortgage banks and constrained the entry of new ones.

The background noise of inflation

0

These days, it is almost impossible to avoid conversations about falling revenues, rising living costs and soaring inflation. You hear them in grocery queues, on public transport and in workplaces. Wherever people gather, the cost of living has become the background noise of daily life.

The most important point to remember is that the financial pressure many people are experiencing is not necessarily the result of personal failure. It is part of a wider economic reality. When people complain that their income is falling while the cost of living is rising, they are describing the same painful reality: their purchasing power is shrinking.

Some may use these concerns to express frustration or mobilise public opinion. That is understandable. Government intervention can also be justified when prices rise suddenly and sharply. Governments have a responsibility to prevent abuse, curb excessive price increases, protect consumers and preserve social stability.

However, even when official inflation figures begin to decline after government action, the situation experienced by households may not improve immediately. Lower inflation does not mean prices return to their previous levels. It only means that prices are rising more slowly than before.

Prices are often sticky. Once they rise, they tend to remain high. Households and businesses must then manage permanently higher costs, even when inflation moderates. This is why people may continue to feel the effects of inflation long after official figures show an improvement.

Our minds also remember earlier prices. Every time we pay more for food, transport, rent, medicine or school supplies, we compare the new price with what we used to pay. Each transaction can therefore feel like a loss. This price-level shock affects nearly everyone, from low-income households to large companies.

Inflation does not only change prices; it changes behaviour. When income does not keep pace with expenses, households begin to reduce non-essential spending. People switch to cheaper brands, postpone major purchases, reduce entertainment spending and focus on necessities.

This is a rational response to financial pressure. But when many households reduce spending at the same time, the effect spreads through the economy. Businesses experience lower sales, revenues fall, and employers may respond by slowing recruitment, cutting bonuses, reducing salary increases or, in more severe cases, laying off workers.

Everything is connected. When consumers spend less, businesses earn less. When businesses earn less, workers face greater uncertainty. This creates a cycle in which anxiety about the future encourages further reductions in spending.

The gap between slow-moving incomes and permanently higher prices creates deep financial and psychological stress. It is normal for people to feel tired, worried or frustrated when they are being squeezed from multiple directions. Recognising that reality is important. But recognition alone is not enough. The next step is to change behaviour.

In a high-inflation environment, relying on willpower is rarely sufficient. What people need are systems that make better financial decisions easier and more consistent. As the saying goes, it is not only your salary that determines your financial security; your spending habits matter as well.

The first step is to rebuild the household budget. An old financial plan may no longer work when food, rent, transport and other essentials have become more expensive. Families should review their expenses honestly, identify unnecessary costs and set new priorities.

This does not mean eliminating every small pleasure from life. It means distinguishing between needs and wants, particularly during a period of financial uncertainty. Creating even a small cash cushion can provide important peace of mind when income is irregular, business revenue is declining or jobs are uncertain.

It is also important to review fixed costs. Housing, transportation and food are usually the largest expenses in a household budget. Finding practical ways to reduce these costs can have a much greater impact than becoming overly focused on every small daily purchase.

For example, households may consider sharing transport where possible, planning grocery purchases, reducing food waste, comparing prices before buying, and avoiding unnecessary debt. Small leaks may appear harmless, but they can become serious over time. As the saying goes, a continuous small leak can eventually sink a great ship.

At the same time, inflation makes it important to explore ways of increasing income. Waiting for a salary increase may not be enough when prices rise faster than wages. People should consider how their existing skills could generate additional income through freelance work, consulting, small businesses, teaching, digital services or other side opportunities.

The objective is not to exhaust oneself by working endlessly. It is to create a measure of resilience. A second income stream, even if modest, can help households cope with emergencies and prevent them from relying heavily on expensive borrowing.

Saving should also become more systematic. Setting aside a fixed percentage of income immediately after receiving a salary or payment can help establish discipline. Even a small amount placed in a savings or investment account can make a difference when unexpected expenses arise.

High-pressure economic periods also create ideal conditions for fraudsters. When people are worried about money, they are more likely to be attracted by offers that promise quick profits, huge discounts or easy solutions.

Consumers should be cautious of “VIP-only” deals, “last chance” promotions, fake sales, limited-time offers and pressure to pay immediately. Such tactics are often designed to bypass careful thinking and push people into impulsive decisions.

Scams now spread easily through social media, messaging applications, SMS campaigns and online advertisements. They may appear professional and legitimate, making them difficult to distinguish from genuine businesses. During holiday seasons and the New Year period, these tactics often become more common.

Before making a major non-essential purchase, it is wise to pause. Give yourself a day or two to think. Compare prices, verify the seller, ask whether the purchase is truly necessary and avoid making decisions based on sudden emotion or fear of missing out.

There is an Ethiopian proverb that offers comfort during difficult times: “Kale fetari amuatesh gagri.” It roughly means, “Since the Creator has not abandoned us, do not lose courage.”

The proverb does not suggest that people should ignore hardship. Rather, it encourages resilience, patience and wise action when circumstances are beyond one’s control.

Inflation requires neither carelessness nor panic. It requires discipline, awareness and practical judgment. Depending entirely on government intervention may offer temporary relief, but it cannot replace sound financial management at the household and business level.

The background noise of inflation may not disappear quickly. Prices may remain high, incomes may take time to improve, and the gap between what people remember paying and what they pay today may continue to cause frustration.

But this is not a personal failure. It is the structure of an economic shock.

The durable response is deliberate behavioural change: build saving habits, control unnecessary expenses, reduce high-cost debt, develop useful skills, search for additional income and treat overly attractive offers with caution.

Do not lose courage. A sensible budget, disciplined spending habits and careful financial decisions can help households weather difficult times. The economic pressure may continue, but a wise approach can help individuals and families cross the valley more safely.