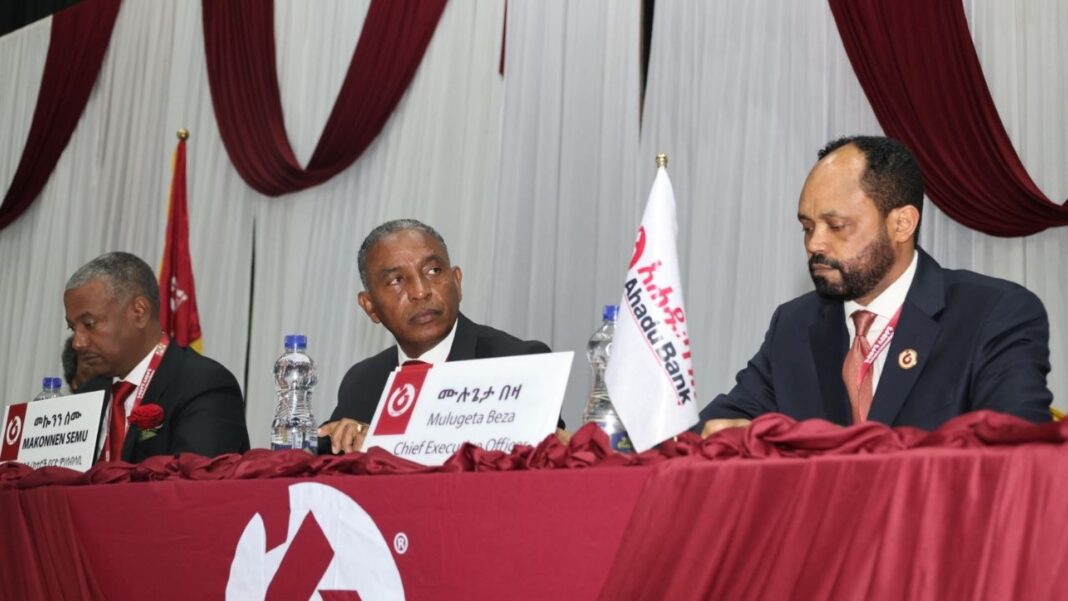
Ahadu Bank has reported a pre-tax profit of 1.07 billion birr for the financial year ended June 30, 2026, as its total revenue reached 3.19 billion birr, reflecting growth in its banking operations and income from both interest and non-interest sources.
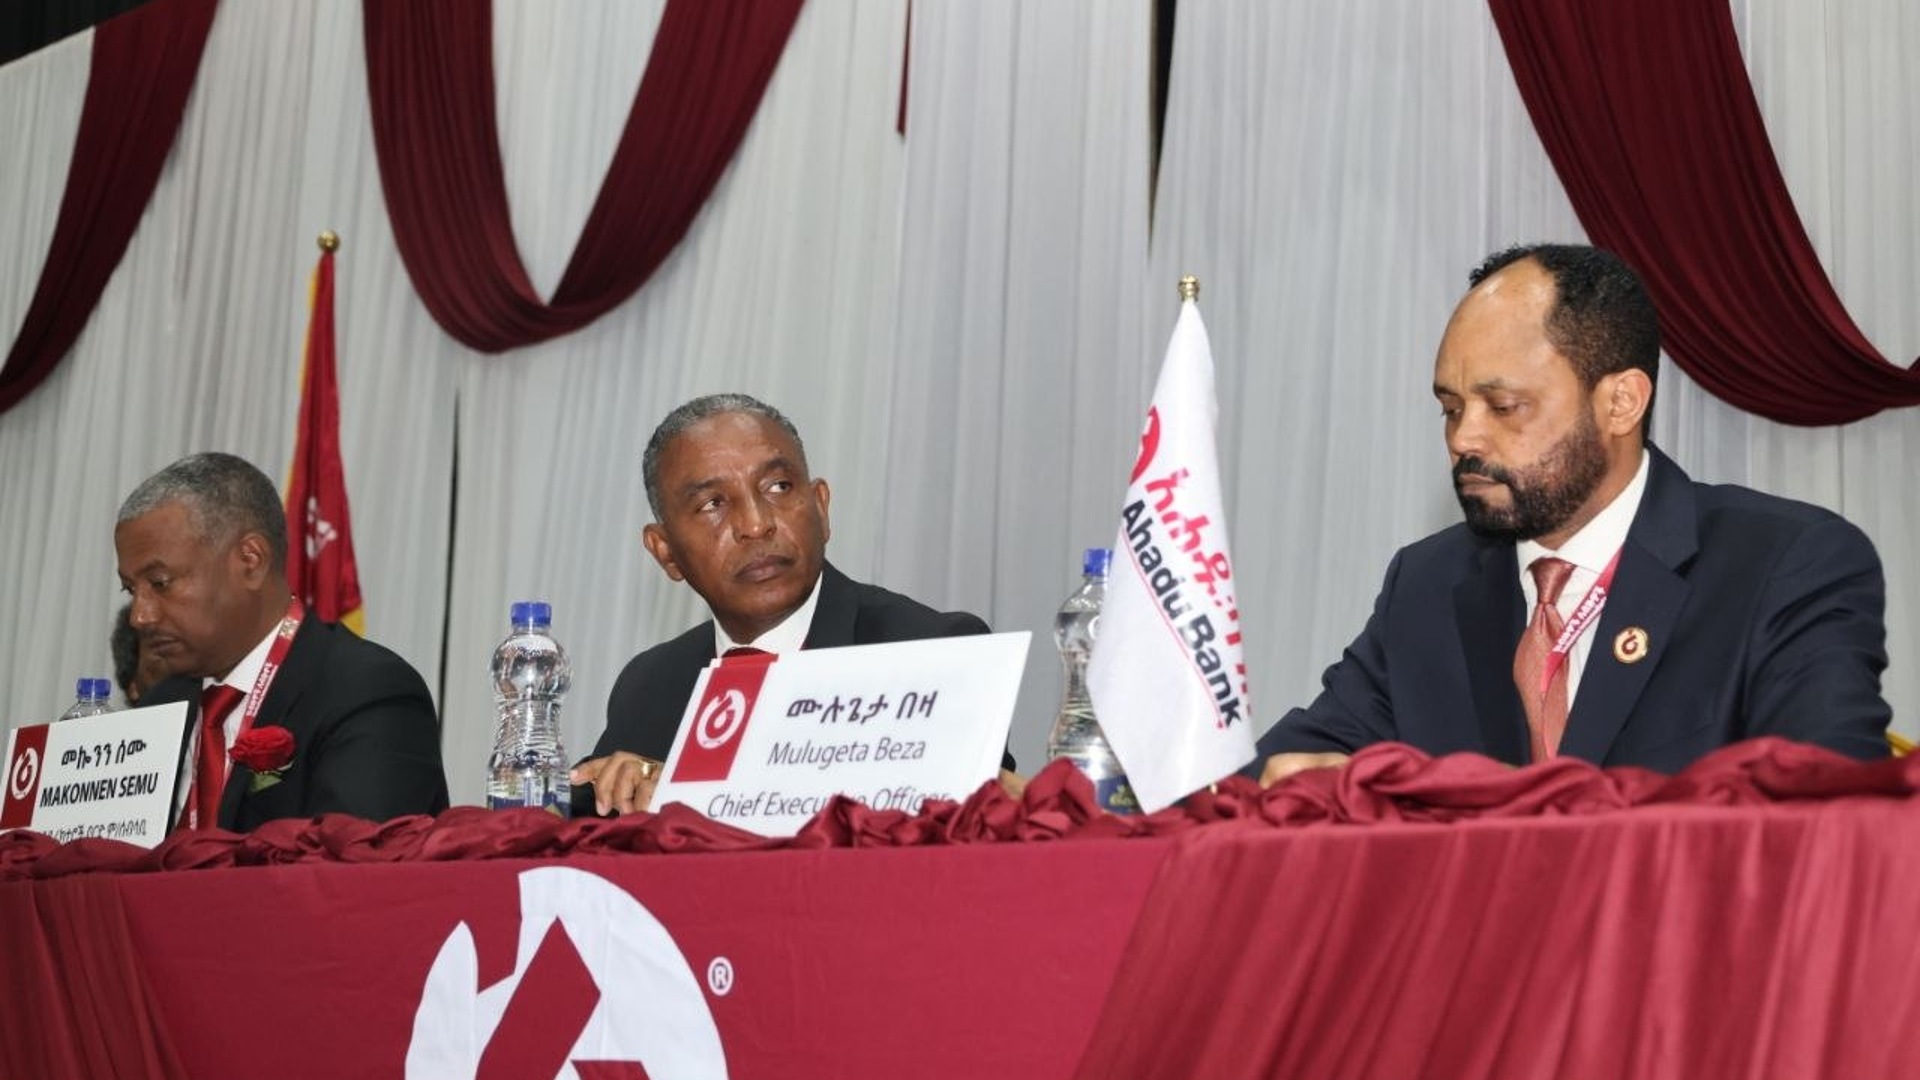
The financial performance was disclosed during the bank’s Fifth Ordinary and Third Extraordinary General Meetings of Shareholders, where management presented its annual performance report for the concluded financial year.
According to the report, interest income accounted for 50.4 percent of the bank’s total revenue, while the remaining 49.6 percent came from non-interest income sources. The nearly balanced revenue composition indicates that the bank generated a substantial share of its earnings from services and other activities beyond traditional lending operations.
However, the bank’s operating expenses also increased during the reporting period. Ahadu Bank incurred total expenses of 2.03 billion birr, representing a 28.3 percent increase, or an additional 469.6 million birr, compared with the previous financial year.
Salaries and employee benefits accounted for the largest share of expenses at 38.6 percent, followed by interest paid on customer deposits at 31.8 percent. Administrative expenses represented the remaining 29.7 percent.
The bank’s total deposits reached 10.47 billion birr by the end of the financial year. Of the total deposits, regular savings accounted for 54.4 percent, demand deposits represented 34.3 percent, while fixed-term deposits contributed 11.3 percent.
Ahadu Bank also reported that it had attracted more than 305,000 new customers during the year, attributing the increase to the expansion of its branch network and the introduction of alternative savings products.
Meanwhile, the bank’s total assets stood at 14.32 billion birr at the end of the reporting period. Liabilities accounted for 11.99 billion birr, or 83.7 percent of total assets, while shareholders’ equity reached approximately 2.34 billion birr.
The bank said it was working to strengthen its capital position through participation in the securities market, as financial institutions face increasing pressure to expand their capital base and improve their capacity to support lending and business growth.