Saturday, September 26, 2026
Home Blog Page 156

Prosperity gospel, false prophets and the money scam

Religion has historically functioned as a source of moral guidance, spiritual meaning, and social cohesion. Across centuries, faith institutions have offered comfort to the poor, challenged injustice, and shaped ethical values within society. Yet religion has also repeatedly been exploited by individuals who weaponise belief for personal gain. In contemporary Christianity, the rise of the Prosperity Gospel and the emergence of self-styled “Prophets” have transformed sections of the Church into highly profitable enterprises where faith is increasingly commercialised. Behind promises of miracles, healing, and financial breakthrough lies an uncomfortable reality. For many false prophets, religion has become one of the most successful money-making scams of the modern era.

The Prosperity Gospel is built upon a simple but powerful theological claim in which God rewards faithful believers with material wealth, good health, and personal success. Poverty and suffering, by contrast, are often portrayed as signs of weak faith, spiritual failure, or demonic attack. Popularised through Pentecostal and charismatic movements, this doctrine has gained enormous influence in the United States, Africa, Latin America, and beyond. The current trend in Ethiopia is indeed alarming. Its appeal is particularly strong in economically fragile societies where unemployment, inequality, corruption, and social insecurity leave millions desperate for hope.

At first glance, the prosperity message appears empowering. It encourages optimism, discipline, ambition, and belief in the possibility of transformation. For many struggling individuals, hearing that their circumstances can change through faith provides psychological relief and emotional motivation. However, beneath the rhetoric of empowerment lies a deeply problematic theology that often turns religion into a transactional marketplace.

In many prosperity churches, faith operates according to economic logic. Congregants are instructed to “sow seeds” by giving money to the church or prophet with the expectation that God will multiply their offering in return. Donations are framed not merely as acts of generosity but as spiritual investments guaranteed to produce divine profit. The more one gives, believers are told, the greater the blessing. In this system, God becomes less a moral or spiritual figure and more a supernatural financier dispensing rewards to paying customers.

The consequences are alarming. Vulnerable individuals often donate beyond their financial capacity because they fear missing divine favour or delaying their miracle. Some believers surrender savings, salaries, pensions, or property in pursuit of promised breakthroughs that never materialise. Meanwhile, many prosperity preachers accumulate extraordinary wealth through tithes, offerings, television ministries, books, conferences, and branded religious merchandise. Luxury cars, private jets, designer clothing, and multimillion-dollar mansions are frequently displayed as visible proof of God’s blessing.

The contradiction is striking. Religious leaders who preach sacrifice, humility, and devotion often live lifestyles indistinguishable from corporate elites or entertainment celebrities. Yet followers are encouraged to interpret this wealth not as exploitation but as evidence of spiritual authority. The prophet’s success becomes the product being sold. “If you follow me,” the message implies, “you too can access divine prosperity.”

This is where the issue of “False Prophecy” becomes central. Historically, False Prophets have been defined not merely by inaccurate predictions but by their manipulation of people for power, influence, or wealth. In many contemporary prosperity movements, charismatic leaders cultivate unquestionable authority by presenting themselves as uniquely chosen by God. Through dramatic miracles, emotional performances, prophetic declarations, and carefully managed media personas, they create environments where scepticism is discouraged and obedience is rewarded.

Critically, many so-called miracles are difficult to verify. Reports of staged healings, fake testimonies, paid actors, and manufactured prophecies have emerged across different countries and ministries. Someone with ample time and patience, can easily witness such practice in one of the very many so-called Prosperity Protestant Churches here in Addis Ababa. Some prophets sell “anointed” products such as miracle water, holy oil, stickers, wristbands, or private consultations (Gust House Prayer time in hotel rooms) for substantial fees. Others promise supernatural cures for illness, infertility, unemployment, overseas visas, or financial hardship. Such practices exploit desperation while masking commercial transactions in spiritual language.

The rise of Celebrity Prophets cannot be separated from broader economic and cultural conditions. Contemporary society increasingly celebrates wealth, visibility, and entrepreneurial success. Social media platforms reward spectacle and emotional engagement, while neoliberal economic systems encourage individuals to treat themselves as personal brands. Prosperity Prophets operate effectively within this environment because they merge religion with entertainment, marketing, and aspirational consumer culture.

In many ways, the Prosperity Gospel mirrors capitalism itself. Success is individualised, failure is personalised, and systemic inequality is ignored. Rather than challenging poverty as a structural issue linked to corruption, exploitation, or unequal economic systems, prosperity theology often places responsibility entirely on the individual believer’s faith. If blessings do not arrive, the problem is rarely the prophet or the system; it is supposedly the believer’s lack of faith.

This narrative is particularly dangerous because it shifts attention away from social justice. Instead of confronting political corruption, unemployment, or inequality, prosperity preaching frequently encourages passive spiritual dependence. Congregants are taught to wait for miracles rather than demand institutional accountability or economic reform. Religion becomes an escape from material hardship rather than a force for social transformation.

The irony is that many core Christian teachings directly challenge this obsession with wealth. The biblical tradition repeatedly warns against greed, exploitation, and the worship of money. Jesus Christ criticised religious hypocrisy and condemned those who turned sacred spaces into centres of commerce. His teachings consistently prioritised compassion, humility, and care for the poor over material accumulation. Early Christian communities emphasised communal sharing and solidarity, not conspicuous consumption.

This does not mean religious institutions should reject money altogether. Churches require financial resources to operate, support communities, and sustain charitable work. The ethical issue emerges when spiritual authority becomes a mechanism for financial manipulation or personal enrichment. Accountability, transparency, and ethical leadership are therefore essential within religious institutions. Without them, faith communities become vulnerable to exploitation disguised as divine revelation.

Supporters of prosperity theology often argue that critics focus excessively on abuses while ignoring positive outcomes. Many prosperity churches provide emotional support, social belonging, and practical assistance to members. Some genuinely encourage entrepreneurship, education, and personal discipline. For individuals living in contexts of hopelessness, the language of possibility can be transformative.

Yet positive intentions cannot excuse systemic exploitation. When religion promises guaranteed wealth in exchange for money, it risks becoming indistinguishable from a commercial scam. The danger lies not only in financial loss but in spiritual disillusionment. Many believers who invest emotionally and financially in false promises are left devastated when miracles fail to occur. Some lose faith entirely, while others remain trapped in cycles of guilt, shame, and dependency.

Ultimately, the prosperity gospel reveals a profound crisis within modern religious culture. It reflects societies where success is measured primarily by wealth and visibility, and where spirituality itself can be commodified for profit. False prophets thrive because they offer certainty in uncertain times, hope in desperate circumstances, and emotional spectacle in an increasingly anxious world.

However, religion loses moral credibility when it becomes a business model built upon the exploitation of vulnerable people. Faith should challenge greed, not sanctify it. It should comfort the oppressed, not enrich the powerful at their expense. The true danger of false prophets is not merely that they deceive individuals, but that they distort the ethical foundations of religion itself.

In an era where prophets increasingly resemble corporate executives and churches operate like commercial brands, believers must ask difficult questions about accountability, truth, and power. The challenge facing modern Christianity is not whether wealth and faith can coexist, but whether religion can resist becoming another marketplace where salvation is bought, miracles are sold, and desperation is transformed into profit.
Africa can break the debt trap by trading more with itself

0

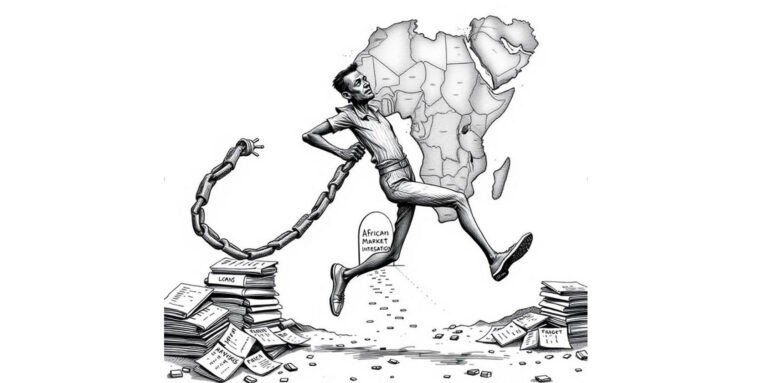
Africa’s debt crisis will not be solved by borrowing alone, nor by waiting for rescue from outside the continent. The more durable answer is to grow the continent’s own markets, strengthen production, and expand intra-African trade so that African economies can generate more of the revenue they need at home.

For decades, many African countries have relied on external financing to cover budget gaps, fund infrastructure, and stabilize currencies. That model has left governments vulnerable to exchange-rate shocks, rising global interest rates, and sudden changes in investor sentiment. When debt service rises, social spending, development programs, and public investment are usually the first to suffer. The result is a cycle in which countries borrow to survive, then borrow again to repay the last round.

Breaking that cycle requires a shift in strategy. Africa must stop treating itself mainly as a collection of small national markets and start behaving like one large economic space. The African Continental Free Trade Area is the clearest path toward that goal. If it is implemented seriously, it can create scale, deepen industrialization, and keep more value within the continent. But trade agreements alone are not enough. Governments must remove the practical barriers that still make it easier to trade with Europe, Asia, or the Gulf than with a neighboring African country.

The first barrier is infrastructure. Goods cannot move cheaply across Africa if roads are poor, rail links are weak, ports are congested, and border posts remain slow and unpredictable. A trader in Kigali should not face more difficulty shipping to Nairobi than to Rotterdam. The same applies to a manufacturer in Accra trying to sell in Abidjan or a farmer in Ethiopia trying to access regional markets. Better logistics is not a luxury; it is the foundation of trade-led growth.

The second barrier is regulation. African businesses still face a patchwork of customs rules, product standards, permit systems, and payment procedures. These frictions raise costs and discourage cross-border commerce. Governments should harmonize standards, simplify customs procedures, and digitize clearance systems so that goods can move faster and more transparently. Regional trade should not depend on political speeches; it should depend on predictable systems that firms can trust.

The third barrier is finance. African trade needs African money. One reason intra-African trade remains underdeveloped is that many transactions are still settled in foreign currencies, exposing firms to exchange-rate risk and higher costs. Regional payment systems, local-currency settlement arrangements, and stronger correspondent banking links can reduce those burdens. If an importer in Uganda can pay a supplier in Tanzania more easily in regional currency, trade becomes simpler and cheaper. That is how markets deepen.

Africa also needs to build more regional value chains. Too many countries export raw materials and import finished goods at a premium. That pattern drains foreign exchange and leaves economies exposed to price swings. Instead, countries should specialize within the continent: one producing inputs, another processing them, another assembling finished goods, and others providing logistics and services. This is how trade becomes a ladder out of debt rather than another reason to borrow.

At the same time, governments must support small and medium-sized enterprises, which are the backbone of any meaningful regional trade system. Large firms can navigate high compliance costs and distant markets, but smaller businesses often cannot. If Africa wants trade to reduce debt pressure, SMEs need access to trade finance, market information, insurance, and export support. Without them, intra-African trade will remain a policy slogan rather than an economic engine.

There is also a political dimension. African leaders must resist the temptation to measure success by how much external financing they attract. The better measure is how much domestic wealth they mobilize and how much regional trade they enable. A continent that consumes what it produces, processes more of what it exports, and circulates capital within its own markets will be less dependent on lenders and more resilient in a volatile world.

Debt will not disappear overnight. Many countries will still need external financing for some time. But the terms of dependence can change. If Africa trades more with itself, it will earn more in local value, build more industrial capacity, and reduce the foreign exchange drain that makes debt so dangerous. Intra-African trade is not just a commercial agenda. It is a debt strategy, a development strategy, and a sovereignty strategy.

The continent’s future will not be secured by borrowing its way forward. It will be secured by building an economy that can stand on its own feet, with African goods, African markets, and African confidence at the center.

How Africa can escape the debt trap

0

The narrative that Africa faces a persistent debt crisis has become entrenched. In fact, despite representing nearly one-fifth of the world’s population, the continent accounts for less than 3% of global sovereign debt. By contrast, the European Union and the United States account for a much larger share (nearly 16% and more than 34%, respectively). Moreover, Africa’s average debt-to-GDP ratio, at 67%, is markedly lower than those of Europe (88.5%), the US (122.6%), and Japan (236.7%).

Nonetheless, many countries on the least-indebted and most capital-starved continent remain stuck in a debt trap. On May 12–13, Senegal will host an international conference to address the country’s escalating debt crisis and, crucially, one of its main drivers: the structural asymmetries embedded in the global financial system. This flawed architecture has obstructed Africa’s access to affordable, long-term capital and prevented the continent from diversifying its sources of economic growth and trade, transforming debt from a manageable development instrument into a self-perpetuating cycle of vulnerability.

In particular, the shift toward costly, short-term, market-based borrowing amid declining concessional lending has trapped African countries in cycles of indebtedness and external dependence. Constrained by fragmented monetary landscapes and underdeveloped domestic financial markets, African countries are forced to borrow in foreign currencies, mainly the US dollar. This leads to currency mismatches and exposes these countries to disorderly capital outflows and exchange-rate and interest-rate risks, especially monetary-policy shifts by the US Federal Reserve and other major central banks.

The balance-of-payments constraint associated with dollar funding creates a negative feedback loop. Exogenous economic shocks trigger capital flight to safe havens, sudden stops in financial inflows, and currency depreciation, all of which exacerbate the debt burden. Policymakers enact fiscal austerity, leading to a further slowdown in economic growth and revenues that make it even harder to service debt in the future.

Credit-ratings agencies such as S&P, Fitch, and Moody’s deepen the debt trap by assigning most African countries lower ratings, which substantially elevate their borrowing costs and limit their market access. Sovereign bonds issued by African countries typically yield 8–15%, in sharp contrast to yields of 1–5% in Europe and North America. These spreads impose high macroeconomic costs. According to the United Nations Development Programme, credit-ratings agencies’ subjective evaluations have cost African countries an estimated $74.5 billion.

These additional costs help create a debt overhang. Interest payments now account for more than 20% of government revenue in several African countries—including around 40% in Nigeria and over 70% in Egypt—thereby imposing significant opportunity costs on development. Resources that could be allocated to infrastructure, industrial policy, human-capital development, and technological upgrading are instead redirected to debt servicing.

In short, Africa is paying so much not because of the amount of debt it has accumulated, but because of how that debt is structured and perceived. For African countries, it costs more to borrow less, setting unrealistic return-on-investment expectations that further undermine debt sustainability. As a result, a growing number of African countries have pursued rollovers and refinancing options, such as issuing new eurobonds, to settle maturing obligations—falling deeper into the debt trap.

This has accelerated the shift in recent decades from long-term concessional loans to short-term commercial debt. Private creditors now hold more than 40% of Africa’s external public debt, up from 17% in 2000. Loans with shorter maturities compress repayment timelines, increase refinancing risks, and are misaligned with Africa’s long-term development objectives. They also raise the risk of maturity clustering. This year, for example, African countries face a record $90 billion debt wall driven by maturing eurobonds. Difficult tradeoffs will likely be necessary.

At the same time, Africa faces other economic constraints. The continent loses more than $50 billion annually in illicit financial outflows through trade misinvoicing, abusive transfer pricing, and tax avoidance. The global financial system enables these leakages with secrecy jurisdictions and limited multilateral cooperation on international taxation.

Moreover, the erosion of human capital and a chronic infrastructure deficit in an austerity-prone operating environment leave many African economies vulnerable to commodity shocks that drive external liabilities higher. When balance-of-payments crises invariably materialize, African governments are compelled to borrow in foreign currencies and implement adjustment programs that prioritize short-term fiscal consolidation over long-term development. (These programs’ procyclical austerity measures can help stabilize public finances but often weaken state capacity and lower potential economic growth). Over time, this leads to repeated cycles of borrowing, crisis, and adjustment—the very definition of a debt trap.

To break the cycle of dependency and accelerate development, policymakers must redesign the global financial architecture. Aligning debt maturities with longer-term development objectives requires improving access to concessional financing, which can be achieved by strengthening development-finance institutions’ capital base. At the regional level, policymakers must fast-track monetary integration and the development of deeper domestic capital markets to support long-term borrowing in local currencies and address structural mismatches between currency denomination and revenue generation.

It is also crucial to reform credit-ratings agencies’ methodologies to achieve parity in access to affordable development finance, and to reduce the incidence of procyclical policies. This will not only rebuild these institutions’ credibility but also foster economic growth and sustainable development. Lastly, the international community should regard fiscal consolidation and debt sustainability as being in service of a broader goal: to promote Africa’s economic development.

Africa is not heavily indebted; it is a victim of deep-seated inequalities, underpinned by an international financial architecture that prevents structural economic transformation and perpetuates debt crises. If the world is to harness Africa’s demographic dividends and unlock its growth potential, both of which are essential to maintaining financial stability worldwide, the institutions, rules, and norms of global governance must become more balanced and development-oriented.

Federal Police uncover counterfeit tissue network, seek more time to probe suspect

0

The Federal Police Crime Investigation Bureau says it has uncovered a large-scale counterfeit distribution network that allegedly harmed market stability, reduced tax revenue and put public health at risk through the sale of substandard products.

Investigators appearing before the Federal First Instance Court, Arada Division First-Instance Criminal Bench, requested a 14-day remand extension to continue their probe into the main suspect, Seyid Mohammednur Umer. Police said the case involves trademark infringement and a wider criminal network that was targeting both the economy and consumers.

According to court documents, the alleged operation ran counter to the government’s recent macroeconomic reforms, which are aimed at stabilizing markets, curbing inflation and improving consumer welfare. Police said the network also deprived the state of significant tax revenue and distorted fair competition in the market.

In their application to the court, investigators said the suspect had used the “VIVa” tissue trademark, registered under International Class 16 by Pure Wood Pulp & Paper Packaging PLC with the Ethiopian Intellectual Property Authority, without the owner’s consent.

Police said they received tip-offs indicating that the suspect had been illegally copying Viva Tissue packaging since 2024 and flooding the market with counterfeit products. They said the alleged operation was not limited to Addis Ababa, but extended to regional towns through a covert network of representatives and accomplices.

Beyond the economic damage, police warned that the counterfeit tissue posed serious health risks to consumers. They said the fake product was reportedly made from substandard waste materials and hazardous chemical additives, unlike the genuine product, which is manufactured under quality controls.

Police told the court that the suspect could destroy evidence, alter facts or intimidate witnesses if released while the investigation continues. They therefore asked for more time to collect testimonial and documentary evidence.

However, during the court session on 5 June 2026, the bench granted a seven-day remand extension instead of the 14 days requested. The case was adjourned to 11 June 2026 for a progress update on the investigation.
