Tuesday, October 20, 2026
Home Blog Page 162

Why this energy shock is different

0

The Gulf ceasefire lasted barely three weeks. After Iranian attacks on three commercial ships in the Strait of Hormuz, the United States struck more than 80 targets, revoked Iran’s oil-sanctions waiver, and declared the memorandum of understanding “over.” Yet the market response was telling: Brent crude rose to around $79 per barrel—a meaningful jump, but far below April’s $120 peak, when the strait was closed outright. That gap between renewed war and restrained prices confronts policymakers with a key question: Is this the road back to blockade, or a violent renegotiation of the terms of passage?

Five months into the war, the severity of the underlying shock is not in doubt. This is not 2022, when Russia’s invasion of Ukraine rerouted supply, and the world absorbed a costly but manageable adjustment. Today’s shock is destroying supply rather than rerouting it, with lost oil output already exceeding that of the 1973–74 OPEC embargo. Once liquefied natural gas, fertilizer inputs, and freight are included, the global energy bill is at least twice the crude price quoted on trading screens.

There are two starkly different readings of Iran’s intentions. According to the first, Iran is seeking full control of the strait. That path leads to a larger conflict, another blockade, and a return to the price dynamics of March, when oil prices spiked. Alternatively, Iran is behaving less like a blockader than a toll collector, maximizing the revenue it can extract from traffic through the strait. Sporadic attacks on shipping then keep the risk premium alive without choking off the flow; oil prices remain elevated and choppy rather than soaring.

The evidence so far points, tentatively, to the second reading. American strikes have deliberately avoided Iran’s energy infrastructure; Iran’s attacks on shipping have been demonstrative rather than systematic; its parliament has debated tolls on “hostile” shipping; and the MOU itself envisaged Iran’s help managing strait traffic. None of this precludes escalation—miscalculation is the Gulf’s default risk—but for now both sides appear to be contesting the price of passage rather than passage itself.

For central banks, the two paths lead to very different destinations. If Iran is collecting tolls, elevated but broadly capped energy prices act like a chronic tax: painful, but not a reason to restart aggressive monetary-policy tightening. Interest-rate expectations would settle roughly where they stood two weeks ago, with attention shifting to second-round effects—whether higher fuel, freight, and food costs fuel wage pressure. If Iran is reaching for the strait itself, central banks will be compelled to act forcefully to prevent a temporary shock from becoming embedded inflation.

That is why markets react so sharply to every headline. Investors are not refining a single forecast; they are toggling between two regimes, and each jump in oil poses the same question: Is this a move from toll collection to blockade?

As a result, interest rates are unusually sensitive to oil. Positioning, at least, is healthier than in the spring: in March, many investors had effectively sold insurance against large swings in interest rates, and when oil spiked they were forced to buy it back at any price, amplifying every move. That exposure has largely been cleared out, so the same headline still moves markets, but without the forced unwinding of March.

Neither scenario, however, resolves the underlying policy bind. With inflation above central-bank targets, and public finances under strain worldwide, none of the standard responses works. Aggressive monetary tightening—unavoidable in the blockade scenario—impedes growth and undermines debt sustainability. Expansive fiscal support fuels inflation and drives up borrowing costs, now that foreign central banks no longer buy government debt at any price. And doing nothing invites a procyclical adjustment, with financing costs rising even as the economy slows.

To navigate this treacherous economic terrain, fiscal and monetary policy must reinforce rather than offset one another. That means targeting support at the most exposed households and sectors, rather than conducting broad cash transfers, and issuing debt that resists the lure of cheaper short-term paper, which merely concentrates refinancing risk when the next shock hits.

It is in the blockade scenario that this logic reaches its unorthodox conclusion. With central banks tightening even as the shock deepens, rising government borrowing costs would crowd out the targeted fiscal support most needed—unless central banks cap increases in short- and medium-term interest rates. With such intervention remaining firmly under central-bank control, and with a clear exit strategy, this would not compromise central banks’ independence, and the alternative—leaving them to bear the burden of adjustment alone—is worse. Recognizing the trade-off now, while the toll collector still holds sway, is preferable to confronting it in the middle of a blockade.

That option is not available to every country: success depends on fiscal starting points, institutional credibility, and investors’ confidence that intervention will be temporary. The US has the most room to maneuver, thanks to deep global demand for Treasuries, even as the dollar’s privilege gradually erodes. The Federal Reserve has held interest rates steady, and markets that began the year expecting cuts now flirt with hikes—the direction hinging on which Gulf scenario prevails.

The eurozone faces a more complicated trade-off. Its fragmented sovereign-debt markets mean that any conditional intervention immediately raises the question of which government is being supported, and why. The European Central Bank’s recent 25-basis-point rate increase underscored the dilemma: the ECB has little choice but to tighten, yet helping the governments most in need of fiscal support would revive the fragmentation fears its 2022 Transmission Protection Instrument was designed to contain.

Japan is in a stronger position: its large foreign-exchange reserves let policymakers resist yen depreciation before energy costs feed into domestic inflation. In either scenario for the strait, the United Kingdom has the narrowest path: a limited fiscal cushion, a persistent external deficit, and inflation running above the Bank of England’s projections point to a wider gap between UK and German government bond yields and a weaker pound.

Even the more benign scenario offers little comfort as winter approaches. European gas storage is at its lowest level for this time of year since 2011, while Qatar would require two months to restore LNG exports even after a durable reopening of the strait. Regardless of how the latest escalation is resolved, Europe’s energy bill will not fall materially before winter.

That is why sequencing matters. The economies most likely to need this toolkit lack the institutional credibility to use it, whereas those with the greatest credibility are least likely to require it. And the path will not announce itself in advance: by the time markets know which one they are on, the room for a measured response will have narrowed—and ordinary borrowers and savers in the most exposed economies will bear the cost of the delay.

The partnership that will shape Ethiopia’s future

0

Ethiopia is currently experiencing a moment of change. Its economy has seen real expansion through many years of state investment in major infrastructure projects including dams, railways, and industrial parks; but it has developed a large amount of debt, has significant inefficiencies, and relies on foreign assistance for a large part of its economy. 

The period of rapid economic growth that followed serious public investment in major infrastructure projects has ended and the country is transitioning to the new phase of the economic plan. There will be no more experimentation with public-private partnerships and they will now be an integral part of the country’s economic strategy.

It has already been decided that the government of Ethiopia will pursue public-private partnerships(PPP), but the key area on which to evaluate the success of this decision will be whether or not Ethiopia has sufficient institutional capacity; a sufficiently mature private sector; and sufficient political will to implement a successful program.

Why Ethiopia turned to Public-Private Partnerships

Ethiopia has turned to public private partnerships (PPP) due to severe financial constraints that threaten the country’s market economy; as such it is moving away from its ideological base. Fiscal constraints on Ethiopia include high levels of government debt, inflation and low levels of tax revenues. A recent audit conducted by the Office of the Federal Auditor General identified over 17 billion birr in total cost of mismanaged road construction and university construction projects, in addition to another estimated 20 billion US dollars needed for recovery and reconstruction over the next five years.

According to investment analysis “PPP is still a work in progress. We all understand the challenges. However, there are no viable alternatives that can sustain additional public sector borrowing.”

The developmental state has reached its limits from debt-financed investment. The private sector will now be required to support a greater portion of Ethiopia’s economy not because the government has abandoned its mission of developing its country, but because it has reached its maximum potential along that path.

The legal architecture — and where it falls short

Under Proclamation No. 1076/2018, Ethiopia has established a PPP Board that is headed by the Minister of Finance and a PPP Directorate-General that serves as the Board’s Secretariat. The sectors covered by the framework are energy, transport, telecoms, healthcare, education, and digital infrastructure. Ethiopian Investment Holding, with $47 – 48 billion in assets under management, will take minority interests in conjunction with private sector investors in key areas.

The structure looks good on paper. The reality on the ground lacks the critical element of capacity, credibility, and confidence. Investors require guarantees for profits repatriation, bankable tariff rates, enforceable contracts – these elements are not consistently in place. The PPP Unit within the Ministry of Finance operates without being adequately coordinated with the Ministry of Planning. Line ministries develop projects independently of each other and they do so, completely bypassing any involvement from central agencies. In most cases, when evaluating a project, investors do not fund framework processes; rather they fund projects with definitive authority, predictable cash flow and strong capable government institutional counterpart that can perform.

The projects showing PPP can work

Recurring projects tend to happen because of the success of preceding ones. For example, the Gad and Dicheto solar projects located in the Somali and Afar regional states were both procured using a public-private partnership (PPP) model. This is how PPP’s are meant to be operated — the use of private sector efficiency to deliver public goods in areas in which the government does not have the means or capability to provide timely, cost-effective services.

A great example of this style of partnership is the Addis Ababa–Adama Expressway project, whereby the public and private sectors both share the risks associated with the project, and toll revenue is used to establish a transparent, predictable revenue stream to fund the project. All future roads, railways, and transit projects built in Ethiopia should hopefully be constructed under similar circumstances.

The sectors that will define Ethiopia’s future

The focus of any government should be on energy and electrification due to their importance to all sectors (manufacturing, digital growth, health services, and education) which rely on universal electrification for their productivity and growth.

The most significant area for development and the least served by private businesses in Ethiopia is the agricultural sector. The World Bank predicts that, with enough private support, Ethiopia is likely to transition from being a net importer of food products to producing surplus food product above and beyond domestic needs (i.e., 20–25% surplus). The public/private partnerships required would include investment in cold chain infrastructure, investment in processing infrastructure, and investment in rural financial services to connect each of these smallholder produced food products to the commercial marketplace.  

The health sector is still a vastly under-developed frontier in Ethiopia and represents one of the missing links between achieving full coverage of health services throughout Ethiopia to all 130 million citizens with minimal or no increase in government health spending. Significant private investment is needed for private hospitals, diagnostic laboratories, and supply chain facilities for pharmaceuticals to allow for the widest access of services to all Ethiopians.  

By improving digital infrastructure (broadband access), farmers would have access to real-time market information, students would have access to global knowledge and businesses would be able to compete on the international market. The premise is simple; the government has ownership of spectrum and regulatory permission to operate in the market; therefore, it is the job of the private sector to bring capital, technology and operating skills to the market.

The five tests that will decide Ethiopia’s PPP future

The legal framework to support institutional capability is in place, but there is an urgent need to develop project preparation capability, such as bankable feasibility studies, credible risk management frameworks, and enforceable contracts.

Investors remain concerned by ongoing foreign exchange restrictions that impede investment, so reasonable confidence will never be achieved from IMF engagement and debt rescheduling without visible evidence of improvement.

Renegotiation of commercial contracts has been a common occurrence throughout Ethiopia’s history and signals to investors that commercial contracts are conditional. The commercial rule of law is the central pillar on which the entire public-private partnership business model relies.

The domestic private sector is not capable of supporting one billion dollar deals; therefore, strategies such as joint ventures, technology transfer, and local procurement should be utilized intentionally to build their capacity.

There is a tension between an overly controlling government and a private sector that prefers to exercise autonomy that has yet to be resolved. To be successful, the framework should be secured in a way that is deep within the institutions of the country so that it can survive times of change in its leadership.

Beyond financing: Redefining the relationship between state and market

A true PPP (Public-Private Partnership) model creates a different fundamental relationship between a state and a citizen. When the state partners with an investor or entrepreneur, they are saying collectively to both the investor and entrepreneur: We trust that you can deliver public goods in partnership with us for mutual benefit, and subject to the terms of accountability agreed upon before entering into partnership.

At a recent investment forum in Ethiopia, the head of the Ethiopian Investment Holding Company challenged private sector participation directly: The government provides capital, land, and regulatory support; however, investors have to provide at least half of the solution. This is the right approach. A PPP works when both parties provide something that neither party could provide alone. A PPP fails when either party tries to take control of the arrangement.

Ethiopia has an abundance of renewable energy resources available. With its prime geographic location, youthful population, and numerous members of its diaspora interested in investing into the country, now is the time to develop an adequate institutional framework in order to transform these resources into collaborative agreements with partners to bring electricity to rural communities, develop roads connecting rural communities to markets, provide healthcare to rural areas, and create employment opportunities for young people who can’t afford to wait for jobs.

A partnership agreement between the government and private sector is more than just a financing vehicle; it is a contract between what the country is now and what it has determined to become in the future.

A 105-Year Journey of Struggle: The Code of China’s Development and a New Chapter in China-Africa Cooperation

0

On July 1st, the Communist Party of China (CPC) marked the 105th anniversary of its founding. For the Chinese people, it is an important occasion to reflect on the nation’s journey of struggle and achievement while looking ahead to the bright prospects. For our African friends who are interested in China’s development, it also offers an important opportunity to gain a deeper understanding of the key to China’s development.

          Over the past 105 years, the CPC has grown from a small group of just over 50 members into the world’s largest governing party with a membership of more than 100 million and tremendous global influence. Under its leadership, the Chinese people founded the People’s Republic of China, a state where the people run the country, and achieved a historic transformation in living standards—from basic subsistence to moderate prosperity, and then to moderate prosperity in all respects. The Party has also led the Chinese people through an industrialization process that took only a few decades to accomplish what developed countries achieved over centuries, creating the twin miracles of rapid economic growth and long-term social stability.

          Chinese President Xi Jinping pointed out that the fundamental reason why the CPC has been able to continuously forge glories over 105 years of struggle, and why history and the people have chosen the Party, lies in its unparalleled fine qualities.

          These fine qualities are reflected primarily in six aspects:

          First, the Party remains steadfast in pursuing truth and always steers the right course. It has consistently integrated the basic tenets of Marxism with China’s specific realities and with its fine traditional culture, while continuously adapting its theories to guide new practices.

          Second, the Party is deeply rooted in the people and always rests on a solid foundation. It is dedicated to serving the public good and exercising governance for the people, and remains committed to its fundamental purpose of serving the people wholeheartedly.

          Third, the Party bravely shoulders its historic mission and always holds the strategic initiative. It combines long-term objectives with phased goals and defines its central tasks in light of the evolving principal contradiction facing Chinese society.

          Fourth, the Party keeps pace with the trend of development and always stands at the forefront of the times. It always proactively identifies, responds to, and steers changes, advancing with the course of history and growing with the progress of the times.

          Fifth, the Party dares to struggle and excels in it, and always maintains full confidence in victory. It remains confident of ultimate success and never wavers or retreats in pursuing the interests of the people, the country and the nation, or in upholding its ideals and convictions.

          Sixth, the Party focuses on self-strengthening and always brims with vigor and vitality. It gives high priority to self-improvement and self-governance, continuously reinforcing its capacity and resilience through self-reform.

          These fine qualities hold the key to the CPC’s enduring success. They also constitute an important source of China’s development achievements and offer valuable insights into the country’s continued progress.

          The CPC is committed not only to pursuing happiness for the Chinese people and rejuvenation for the Chinese nation. It is also dedicated to human progress and world harmony. The Party has always stood on the right side of history and on the side of human civilization and progress. Chinese modernization has opened up a new path to modernization and created a new form of human advancement, offering developing countries broader options for pursuing modernization suited to their own national conditions.

          China has actively promoted the building of a community with a shared future for mankind and put forward the Global Development Initiative, the Global Security Initiative, Global Civilization Initiative, and the Global governance Initiative, contributing Chinese wisdom, Chinese solutions and Chinese strength to addressing common challenges facing humanity, while bringing greater stability and positive energy to a world undergoing profound transformation and turbulence.

          China-Africa friendship and cooperation stand as a vivid testament to this vision. The year 2026 marks the 70th anniversary of the establishment of diplomatic relations between China and African countries, and has also been designated the China-Africa Year of People-to-People Exchanges.

          Over the past seven decades, China and Africa have remained committed to the principles of sincerity, real results, amity and good faith, as well as the approach of pursuing the greater good and shared interests, forging a path of mutually beneficial cooperation. Bilateral trade reached US$348 billion in 2025, and China has remained Africa’s largest trading partner for 17 consecutive years. From the Mombasa–Nairobi Standard Gauge Railway and cross-border telecommunications networks to the promotion of Juncao technology and numerous “small yet beautiful” projects such as water wells and rural water supply systems, China-Africa cooperation has delivered tangible benefits to the lives of African people.

          On May 1st, China started granting zero-tariff treatment on 100 percent of tariff lines to all 53 African countries with which it has diplomatic relations, further opening its market and sharing development opportunities with Africa. More recently, following the outbreak of a new Ebola epidemic, China promptly provided emergency humanitarian assistance to the affected countries and the African Union, once again demonstrating the true meaning of the all-weather China-Africa community with a shared future for the new era.

          At present, under the leadership of the CPC, the Chinese people are steadily advancing toward the goals of basically realizing socialist modernization by 2035 and building China into a great modern socialist country in all respects by the middle of the century. On this new journey, China-Africa cooperation enjoys even broader prospects. China will continue to support Africa in implementing Agenda 2063 and deepen cooperation in such areas as industrialization, agricultural modernization, infrastructure development, green energy, the digital economy, public health and youth development, helping Africa achieve independent and sustainable development. China will also continue to work with Africa and other developing countries to promote greater representation and a stronger voice for the Global South in international affairs, and to make the international order more just and equitable.

          History has shown that solidarity is the key to overcoming challenges, while independence is essential to shaping one’s own future. The CPC’s 105 years of struggle have also demonstrated that any country can achieve development and national rejuvenation by staying true to its founding mission, remaining firmly rooted in its people, and pursuing a development path suited to its own national conditions.

          China and Africa share similar historical experiences and common aspirations for development. More than ever, we should stand together, firmly keep our future in our own hands, and work to deliver even greater outcomes through the all-weather China-Africa community with a shared future for the new era—bringing greater benefits to our peoples and making new contributions to the progress of humanity.

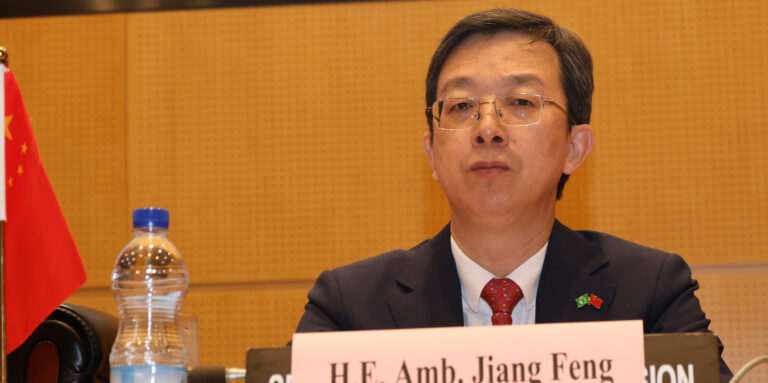
Ambassador JIANG Feng is Head of Mission of China to the AU and Representative of China to the UNECA

Role of ethics and technology in building efficient and trustworthy tax system

0

An effective tax system is the backbone of government finance and national development. However, the success of a tax system should not be measured solely by the amount of revenue collected. Equally important is the efficiency with which taxes are collected and the degree to which taxpayers perceive the system as fair and transparent.

A widely used indicator of tax administration efficiency is the Cost of Collection Ratio (CCR), which measures the amount spent by a tax authority to collect tax revenue. Many tax administrations face challenges related to the potential for undue influence or corruption in the assessment process. As governments embrace digital transformation, technology and artificial intelligence (AI) are increasingly used to reduce administrative costs, improve compliance, and minimize direct interactions between taxpayers and tax officials—thereby limiting opportunities for unethical practices.

The cost of tax collection refers to the total expenditure incurred by a tax authority in administering, assessing, and collecting taxes. These costs include employee salaries, office operations, taxpayer education, audits, and IT systems.

Tax professionals calculate the Cost of Collection Ratio (CCR) as (Total Tax Administration Costs divided by Total Tax Revenue Collected) × 100.

Based on the calculation, internationally approved rates indicate that a CCR below 1% is considered as highly efficient, while 1–2% is efficient. Be that as it may ratios between 2–3% are acceptable for developing countries facing several administrative challenges. Ratios exceeding 5% often signal inefficiencies requiring further investigation.

However, a low ratio alone does not indicate an effective tax system. A tax authority that cuts enforcement may reduce costs in the short term while losing substantial revenue due to increased evasion. Therefore, the objective should be an optimal balance between administrative costs, revenue generation, and taxpayer compliance.

In this regard one thing to be considered is the challenge of discretionary power in tax assessment. In many tax administrations, individual assessors possess significant authority in determining taxable income, evaluating deductions, imposing penalties, and selecting audits. While professional judgment is sometimes necessary, excessive discretion can undermine confidence in the tax system.

When taxpayers believe their liabilities depend more on individual officials than on objective legal standards, opportunities arise for informal negotiations, favoritism, and corruption. Such situations reduce public trust and discourage voluntary compliance.

The challenge for modern tax administration is to reduce unnecessary human discretion while preserving fairness and professional oversight. As has been indicated in Ethiopia’s Tax Administration Proclamation No. 983/2016, tax officers are required to be honest and fair, to avoid conflicts of interest, and maintain taxpayer confidentiality.

All in all, strengthening ethical frameworks is essential. Tax officials should be guided by principles of integrity, impartiality, and professional competence. Regular ethics training and strict disciplinary measures help maintain public confidence.

Professional capacity is equally important. Tax assessors should receive ongoing training in taxation, accounting, information systems, and taxpayer rights. Staff rotation policies can also reduce the risk of long-term relationships developing between officials and taxpayers. Independent internal audit units should regularly review assessments to ensure compliance with established procedures.

Reducing assessor influence in particular requires investment—in training, digital infrastructure, cybersecurity, and institutional reforms. Although these investments may increase administrative costs in the short term, international experience demonstrates that they often produce significant long-term benefits: improved compliance, limited personal contacts, higher revenue collection, and lower administrative burdens.

Spending on modernization, in this regard should not be viewed as a cost but as an investment in better governance. Because, the transformative role of information technology and AI is immense.

IT has become one of the most effective tools for reducing direct contact between taxpayers and tax officials. Electronic registration systems eliminate manual procedures and improve record accuracy. Online filing platforms and electronic payment systems reduce cash-related transactions and create transparent transaction records.

Integrated databases enable tax authorities to verify information using data from banks, customs, employers, business licensing agencies, and land registries. Such systems reduce dependence on subjective judgments and improve assessment accuracy. By standardizing procedures and creating electronic audit trails, technology helps ensure consistent treatment of taxpayers.

AI represents the next stage in tax administration reform. AI systems can analyze large volumes of data, identify unusual patterns, and support evidence-based decision-making. They can select audit cases through risk-based models, detect doubtful transactions, identify potential fraud, and compare taxpayer declarations with industry benchmarks and third-party information. AI-powered virtual assistants can provide taxpayers with consistent information, reducing dependence on individual officers.

Despite those advantages, AI is not a complete substitute for human judgment. Effective implementation requires strong governance, reliable data, cyber-security safeguards, and legal protections for taxpayer privacy.

Several countries provide useful examples of how technology and institutional reforms can improve tax administration efficiency.

For example, in the United Kingdom, HM Revenue and Customs has implemented extensive digital services through its “Making Tax Digital” initiative, reducing direct interactions between taxpayers and officials.

In Japan, the National Tax Agency emphasizes professionalism, taxpayer education, and electronic filing, contributing to strong voluntary compliance.

While the Ghana Revenue Authority’s digital reforms have significantly reduced opportunities for informal negotiations, the South African Revenue Service, widely regarded as one of Africa’s most advanced tax administrations, uses automated assessments and sophisticated data analytics to minimize manual intervention.

With this background, the author of this article believes that improving tax administration efficiency in Ethiopia requires a comprehensive reform strategy combining ethical standards, professional development, technological modernization, and institutional accountability.

Short-term priorities should include strengthening ethics programs, improving staff training, implementing staff rotation policies, and enhancing internal oversight mechanisms.

Medium-term reforms should focus on expanding electronic filing, electronic payment platforms, integrated taxpayer databases, and risk-based audit selection methods.

Long-term objectives should include the adoption of AI, automated assessments, predictive analytics, and advanced data-matching technologies.

In general, the future of effective tax administration lies in reducing dependence on individual discretion and increasing reliance on transparent rules, professional standards, accurate data, and modern technology. While investments in reform may initially increase administrative costs, international experience demonstrates that such expenditures ultimately improve efficiency, increase revenue, strengthen public trust, and reduce opportunities for dishonesty.

A successful tax system is not simply one that collects more revenue. It is the one that collects revenue fairly, efficiently, transparently, and at a reasonable cost to both government and taxpayers. In the digital age, IT and AI provide powerful tools for achieving these objectives.

ficient and Trustworthy Tax System

An effective tax system is the backbone of government finance and national development. However, the success of a tax system should not be measured solely by the amount of revenue collected. Equally important is the efficiency with which taxes are collected and the degree to which taxpayers perceive the system as fair and transparent.

A widely used indicator of tax administration efficiency is the Cost of Collection Ratio (CCR), which measures the amount spent by a tax authority to collect tax revenue. Many tax administrations face challenges related to the potential for undue influence or corruption in the assessment process. As governments embrace digital transformation, technology and artificial intelligence (AI) are increasingly used to reduce administrative costs, improve compliance, and minimize direct interactions between taxpayers and tax officials—thereby limiting opportunities for unethical practices.

The cost of tax collection refers to the total expenditure incurred by a tax authority in administering, assessing, and collecting taxes. These costs include employee salaries, office operations, taxpayer education, audits, and IT systems.

Tax professionals calculate the Cost of Collection Ratio (CCR) as (Total Tax Administration Costs divided by Total Tax Revenue Collected) × 100.

Based on the calculation, internationally approved rates indicate that a CCR below 1% is considered as highly efficient, while 1–2% is efficient. Be that as it may ratios between 2–3% are acceptable for developing countries facing several administrative challenges. Ratios exceeding 5% often signal inefficiencies requiring further investigation.

However, a low ratio alone does not indicate an effective tax system. A tax authority that cuts enforcement may reduce costs in the short term while losing substantial revenue due to increased evasion. Therefore, the objective should be an optimal balance between administrative costs, revenue generation, and taxpayer compliance.

In this regard one thing to be considered is the challenge of discretionary power in tax assessment. In many tax administrations, individual assessors possess significant authority in determining taxable income, evaluating deductions, imposing penalties, and selecting audits. While professional judgment is sometimes necessary, excessive discretion can undermine confidence in the tax system.

When taxpayers believe their liabilities depend more on individual officials than on objective legal standards, opportunities arise for informal negotiations, favoritism, and corruption. Such situations reduce public trust and discourage voluntary compliance.

The challenge for modern tax administration is to reduce unnecessary human discretion while preserving fairness and professional oversight. As has been indicated in Ethiopia’s Tax Administration Proclamation No. 983/2016, tax officers are required to be honest and fair, to avoid conflicts of interest, and maintain taxpayer confidentiality.

All in all, strengthening ethical frameworks is essential. Tax officials should be guided by principles of integrity, impartiality, and professional competence. Regular ethics training and strict disciplinary measures help maintain public confidence.

Professional capacity is equally important. Tax assessors should receive ongoing training in taxation, accounting, information systems, and taxpayer rights. Staff rotation policies can also reduce the risk of long-term relationships developing between officials and taxpayers. Independent internal audit units should regularly review assessments to ensure compliance with established procedures.

Reducing assessor influence in particular requires investment—in training, digital infrastructure, cybersecurity, and institutional reforms. Although these investments may increase administrative costs in the short term, international experience demonstrates that they often produce significant long-term benefits: improved compliance, limited personal contacts, higher revenue collection, and lower administrative burdens.

Spending on modernization, in this regard should not be viewed as a cost but as an investment in better governance. Because, the transformative role of information technology and AI is immense.

IT has become one of the most effective tools for reducing direct contact between taxpayers and tax officials. Electronic registration systems eliminate manual procedures and improve record accuracy. Online filing platforms and electronic payment systems reduce cash-related transactions and create transparent transaction records.

Integrated databases enable tax authorities to verify information using data from banks, customs, employers, business licensing agencies, and land registries. Such systems reduce dependence on subjective judgments and improve assessment accuracy. By standardizing procedures and creating electronic audit trails, technology helps ensure consistent treatment of taxpayers.

AI represents the next stage in tax administration reform. AI systems can analyze large volumes of data, identify unusual patterns, and support evidence-based decision-making. They can select audit cases through risk-based models, detect doubtful transactions, identify potential fraud, and compare taxpayer declarations with industry benchmarks and third-party information. AI-powered virtual assistants can provide taxpayers with consistent information, reducing dependence on individual officers.

Despite those advantages, AI is not a complete substitute for human judgment. Effective implementation requires strong governance, reliable data, cyber-security safeguards, and legal protections for taxpayer privacy.

Several countries provide useful examples of how technology and institutional reforms can improve tax administration efficiency.

For example, in the United Kingdom, HM Revenue and Customs has implemented extensive digital services through its “Making Tax Digital” initiative, reducing direct interactions between taxpayers and officials.

In Japan, the National Tax Agency emphasizes professionalism, taxpayer education, and electronic filing, contributing to strong voluntary compliance.

While the Ghana Revenue Authority’s digital reforms have significantly reduced opportunities for informal negotiations, the South African Revenue Service, widely regarded as one of Africa’s most advanced tax administrations, uses automated assessments and sophisticated data analytics to minimize manual intervention.

With this background, the author of this article believes that improving tax administration efficiency in Ethiopia requires a comprehensive reform strategy combining ethical standards, professional development, technological modernization, and institutional accountability.

Short-term priorities should include strengthening ethics programs, improving staff training, implementing staff rotation policies, and enhancing internal oversight mechanisms.

Medium-term reforms should focus on expanding electronic filing, electronic payment platforms, integrated taxpayer databases, and risk-based audit selection methods.

Long-term objectives should include the adoption of AI, automated assessments, predictive analytics, and advanced data-matching technologies.

In general, the future of effective tax administration lies in reducing dependence on individual discretion and increasing reliance on transparent rules, professional standards, accurate data, and modern technology. While investments in reform may initially increase administrative costs, international experience demonstrates that such expenditures ultimately improve efficiency, increase revenue, strengthen public trust, and reduce opportunities for dishonesty.

A successful tax system is not simply one that collects more revenue. It is the one that collects revenue fairly, efficiently, transparently, and at a reasonable cost to both government and taxpayers. In the digital age, IT and AI provide powerful tools for achieving these objectives.