

ECMA eyes digital integration, investor trust to deepen Ethiopia’s capital market
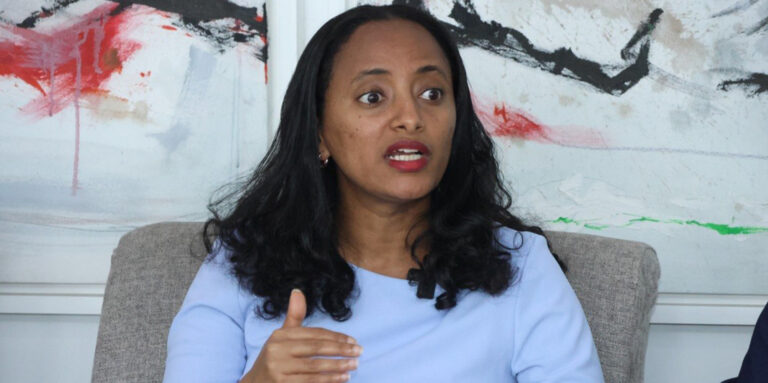
In this interview with Capital’s Groum Abate on the sidelines of the Africa CEO Forum in Kigali, Rwanda Hana Tehelku, Director General of the Ethiopian Capital Market Authority (ECMA), discusses the steps Ethiopia is taking to build a stronger capital market. She explains the authority’s plans to integrate investment platforms with payment systems, strengthen investor protection, improve financial literacy and attract foreign portfolio investment through clearer regulation and better market infrastructure. Excerpts;
Capital: Compared to other African countries, Ethiopia lags in payment integration and lacks a streamlined, unified system. What are your plans and readiness level in this regard?
Hanna Tehelku: Payment systems do not fall directly under our regulatory purview. As you know, the National Bank of Ethiopia (NBE) regulates banks and the financial system, and is responsible for overseeing all payment systems, including those operated by banks, fintechs, and advanced technology startups.
Nevertheless, these payment systems are of great value to us, particularly for the capital market. They play a significant role by expanding liquidity, increasing public participation, and enabling individuals to manage savings and investments concurrently.
A key benefit of linking investment with payment solutions is that it allows individuals to access their invested funds quickly for various needs—such as daily expenses, children’s school fees, or health emergencies. This accessibility encourages them to shift money from traditional bank accounts to higher-yield investment options.
Over the past two to three years, Ethiopia has witnessed extremely rapid mobile money adoption, with transactions reaching tens of trillions of Birr. This significant shift indicates that despite initial public skepticism about the technology’s reliability, people adapted quickly and embraced its use. Consequently, integrating this payment system with investment products is absolutely essential.
While mobile money systems are not fully deployed across all countries globally, Africa’s mobile money growth is remarkably significant compared to the global pace, and Ethiopia’s adoption rate is particularly high. Therefore, integrating this system is critical.
Currently, the Ethiopian Securities Exchange (ESX) has introduced an app called ‘Neway,’ which allows individuals to open investment accounts and trade remotely. This app eventually needs to be linked with payment systems, as such integration is crucial for users to open investment accounts, execute trades, and transfer funds. Although we are in the initial stages, we are working extensively on this integration.
Our benchmark for this work is the trading and fund manager applications recently launched in Kenya in collaboration with Safaricom.
The primary reasons for needing this system are to streamline Know Your Customer (KYC) verification and Anti-Money Laundering/Countering the Financing of Terrorism (AML/CFT) requirements. Opening an account necessitates a thorough KYC verification process, which includes confirming name, age, address, and National ID. Integrating our newly launched National ID with this system is a current priority.
If customers must manually fill out this information for every account, the process becomes time-consuming, thereby increasing the cost of investment. While valuing time as money is not always prevalent in our country, this manual burden undeniably represents a significant cost.
For instance, the two to three hours it takes to open an account, or the transport expenses incurred to visit a broker’s office, all contribute to the overall investment cost.
To eliminate this hassle, efforts are underway to link the National ID with existing KYC data that users have already provided to their payment systems, banks, or mobile banking apps. Our current dilemma is whether to await the full completion of this process or to integrate it simultaneously. Once fully established, the integration will synchronize National ID and banking data, significantly simplifying the retrieval and processing of KYC information. We are prioritizing this, as moving in this direction is inevitable.
Capital: Globally, fraud related to stock exchanges is highly sophisticated. How do you plan to prevent this, and what is your readiness?
Hanna: In the capital market, trust, credibility, and reliability are critical issues. To combat this threat, both we and other countries employ multiple layers of defense.
Our primary defense is fostering financial awareness. Regulatory actions and other operational tools serve as secondary and tertiary defenses. Retail and institutional investors possess distinct internal capacities. Institutional investors, for instance, can afford financial analysts or investment advisors, which significantly lowers their risk exposure to such dangers.
Expanding financial awareness is crucial, especially for protecting retail investors. They need a fundamental understanding of key aspects: how to differentiate legitimate from illegitimate investments, how to identify risk, and what opportunities and risks are involved in any investment.
When an investment option is presented via platforms like TikTok, Facebook, or Telegram, individuals must have independent means to verify its authenticity. For instance, we mandate that all investment advertisements include a confirmation at the end stating, “Approved by the Ethiopian Capital Market Authority.”
This serves as a simple, clear filter. If an advertisement lacks this confirmation, it signals a problem. It indicates the company has not submitted its documents to the Authority, lacks a registration statement, or is otherwise evading the regulatory framework, prompting investors to exercise caution.
Secondly, investors should be aware of essential documents like the “Prospectus” and “Registration Statement.” They need to know where to find and how to interpret these documents. Anyone proficient in Amharic or English can easily access and review the company’s history and detailed information within these documents.
Thus, investor awareness is our primary tool of protection. Without requiring advanced economic knowledge, the ability to read financial charts, or legal expertise, simply understanding these basics is sufficient to establish the first wall of defense.
Our second defense is a robust regulator. The regulator must be capable of thoroughly understanding and reviewing submitted documents, proactively preventing fraud, and imposing penalties proportional to the scale of violations once they occur.
Our rigorous evaluation process for registration statements would illustrate this mechanism clearly. We conduct deep examinations of these documents. On average, we provide multi-page feedback over four to five rounds. Discussions are held both in person and virtually. Beyond submitted documents, we extensively review accessible open-source information and records from various institutions. This comprehensive approach forms our second line of defense against fraud.
Our third and most critical defense involves our supervisory tools. This includes monitoring our service providers and the broader market.
We monitor the market both on-site and off-site, leveraging technology. For this, we integrate modern technology with the exchange system for market surveillance. This technological framework, utilizing market parameterization, is capable of detecting market manipulation, insider trading, front-running, and any other market misconduct strictly prohibited under Proclamation No. 929.
The system alerts us to suspicious activity. However, as technology alone is insufficient, we also employ extensively trained professionals specializing in surveillance. These combined elements form our primary defenses.
Capital: How are you creating that awareness? Secondly, how can you detect insider trading? What kind of tools do you have?
Hanna: Creating financial awareness involves a multi-layered approach. Our initial focus, as you know, is expanding our regional presence. Over the past year, we’ve conducted seven to ten public engagements in various cities across the regions.
Our objective isn’t to turn people into sector experts, but to equip them with a basic understanding of the capital market. We’ve established a presence in cities such as Mekelle, Dire Dawa, Harar, Jimma, Bahir Dar, Wolaita Sodo, Arba Minch, and Ambo. We avoid a one-size-fits-all training approach, instead segmenting the community. For instance, we organize distinct platforms for the business community and separate ones for students and the academic community.
Last week in Dire Dawa, for example, we held training sessions for the business community, another for students and teachers, and a third for government institutions (specifically the Documents Authentication and Registration Service). This segmentation is crucial because the required knowledge and existing capacity vary significantly across societal groups. We tailor our programs by identifying the specific type and depth of knowledge each segment needs, recognizing that this is an ongoing process, not something achievable in a single one- or two-day session.
Our second strategy targets youth. We organize summer camps and foster close relationships with young people. Recognizing their natural inclination towards new and innovative investments like the capital market, we provide them with training as a preventative measure. Moreover, youth play a significant catalytic role. They readily share acquired knowledge with peers at school, relatives, and during family gatherings. Their active sharing of what they learn and observe extends beyond self-protection, positioning them as potential major investors in the future. This approach has proven highly beneficial.
The third segment we engage is the educated middle class. While the existence of a middle class in Ethiopia is debatable and not our current focus, this educated segment forms a substantial following on our LinkedIn page. We continuously update our website and leverage platforms like LinkedIn, YouTube, and other social media to consistently deliver information and demystify market concepts. With approximately 67,700 followers on LinkedIn alone, a remarkably high number for a government institution, we strive to utilize this capacity effectively.
We apply a similar logic here as with the youth. These followers, eager to adopt new concepts, are themselves capable investors. Furthermore, as many lead institutions or are educators, their catalytic role is broader and more pronounced than that of students. This segmented approach allows us to effectively reach the public.
Additionally, we are formalizing this process through platforms like the Regional Capital Market Summit. We are also actively seeking collaboration with media institutions such as yours. Moreover, we are working to bring international platforms, including AFIS (Africa Financial Industry Summit) and the Africa CEO Forum, to Addis Ababa, and have received encouraging preliminary feedback.
We aim to host AFIS in 2027 and a similar conference next year. We are also in discussions with Jeune Afrique Media, though significant work remains. Additionally, we have secured funding for a study to establish a Capital Market Academy. Once established, the academy will enable individuals to acquire knowledge supported by certification or a standardized curriculum. Our efforts are thus multi-sectoral, not confined to a single area.
Regarding your excellent question about insider trading, misusing inside information is a complex issue everywhere. Our law clearly defines who is considered an “insider” and what constitutes inside information.
We proactively identify potential insiders, rather than reacting after a problem occurs. We start by identifying senior company officials listed in the company’s prospectus and registration statement. This allows us to identify and monitor specific insider groups in advance. This process is then complemented by the technology I mentioned earlier.
Parameters exist to detect insider trading, such as changes in trading volume. For instance, if an individual who typically makes 100-Birr transactions suddenly executes a one-million-Birr transaction, the system generates an alert. In the future, this system will need to be linked with Artificial Intelligence (AI) tools, as an increase in transaction volume alone is not a definitive indicator of insider trading.
Therefore, such alerts must be correlated with new company information. We consider factors like the release of earnings statements or management changes. This is because most insider trading fraud is associated with corporate mergers and acquisitions, shifts in top leadership, the publication of earnings reports, and material contracts that significantly impact a company’s revenue—all of which are explicitly stated in the prospectus.
For example, if a high-revenue contract is terminated or a new one secured, we thoroughly examine high-volume trades executed just before that information became public. We operate by considering all these conditions.
Capital: A significant challenge for foreign investors is the ability to repatriate their funds. If foreign investors do not participate, and we only trade domestically, the market will stagnate without growth. How do you plan to address this?
Hanna: Regarding funds repatriation, as I mentioned, while I prefer not to speak broadly outside my regulatory mandate, I recognize its critical importance. Since the implementation of the Forex Reform, positive changes have emerged, such as increased interest in Foreign Direct Investment (FDI). Nevertheless, my stance is that capital must first enter the country before it can be repatriated. Therefore, a legal framework and robust mechanisms to encourage portfolio investment must be established beforehand. When investors bring in capital, they will naturally inquire about the process for taking it back out. The initial Directive No. 001/2024, introduced foreign portfolio investment under the forex reform framework, stipulates that the National Bank and the Capital Market Authority will jointly issue detailed guidelines.
Therefore, the country requires a favorable and predictable legal framework for portfolio investors—those who invest in shares, bonds, Collective Investment Schemes (CIS), and similar securities—distinct from direct foreign investors. We are currently developing this framework.
Currently, the National Bank has assigned the responsibility for repatriation directly to commercial banks. In this regard, we propose two solutions. The first is to adequately train banks in foreign exchange management and build their internal capacity to operate in this open market. This includes increasing foreign exchange supply through auctions, boosting exports, and implementing other solutions.
The second option is the entry of foreign banks into the country. Several regional banks have expressed significant interest in entering Ethiopia and have held numerous discussions with the Ethiopian Investment Commission and our office. This is publicly known; for instance, Kenya’s Equity Bank and KCB have officially announced their interest in acquiring existing Ethiopian banks. Additionally, Nigeria’s Zenith Bank and other North African banks are engaged in both public and private discussions.
Given their extensive global and regional operations, these foreign banks are not expected to face a unique dollar shortage in Ethiopia. Therefore, foreign investors could either utilize domestic banks with better foreign exchange liquidity or engage with the newly entering foreign banks.
Consequently, my greater concern is not repatriation itself, but rather establishing options for foreign investors to engage in portfolio investments, creating a robust price discovery mechanism, and ensuring sufficient liquidity for the equity and debt instruments available in our market.
Capital: What is the current status of the Collective Investment Scheme (CIS) directive?
Hanna: We have finalized the Collective Investment Scheme (CIS) directive and sent it to the Ministry of Justice. As the directive is extensive and highly technical, we are actively following up on its progress and awaiting the outcome. The Ministry requires time for a thorough technical review of the directive.
Recognizing that it would be inappropriate to simply submit such a complex technical directive for approval, we conducted an initial training session for their experts before submission. To further enable their review and deliberation on its contents, we will provide a second round of training within the week. This two-day training session will explain the perspective from which the directive was drafted, clarify its technical details, identify stakeholders, and demonstrate its linkage with our proclamation and other relevant laws. After this, I am confident they will submit all their comments. As this directive is crucial and will leave a significant legacy, we eagerly await its swift issuance and will provide all necessary support.
Capital: Are foreign investors waiting for this directive?
Hanna: Exactly. Fund managers, in particular, are eagerly awaiting it. Foreign investors can be categorized in two or three ways. The first category comprises service providers, and we are currently processing applications from two sub-categories within this group.
Regarding fund managers, I personally traveled to Nairobi and provided an extensive briefing on Ethiopian investment opportunities to the President and Vice President of the Fund Managers Association of Kenya. Additionally, we visited the offices of four or five large fund managers to explain how they can participate in the Ethiopian market and outline the support they would require. They expressed significant interest. Some subsequently visited Addis Ababa a week after my return to explore the ecosystem. I anticipate that as soon as the Collective Investment Scheme (CIS) directive is issued, foreign fund managers will come to Ethiopia and apply for licenses. Beyond this, I believe many investors involved in official portfolio investment, Venture Capital (VC), and Private Equity (PE) sectors will also enter the market.
Capital: The Kenyan stock market lost billions of shillings due to severe panic selling and foreign investor flight. Tanzania and Uganda have experienced similar issues, including low liquidity and reduced foreign investor participation. Despite establishing capital markets long ago, these countries continue to face such challenges. As a newcomer, aren’t you concerned by this situation? Will investors abandon these markets for yours, or will they lose confidence in the African market entirely?
Hanna: We have thoroughly considered the common challenges facing the African financial market. The first challenge is the historically minimal number of new Initial Public Offerings (IPOs) across the continent.
The second major problem is a lack of liquidity. If investors cannot easily enter and exit (buy and sell) the market, they become wary. Consequently, rather than investing, they prefer to keep their money in savings accounts despite low interest rates. Therefore, liquidity is absolutely critical, and it is the primary problem for the countries you mentioned.
Another recurring issue is the erosion of security and credibility. Since trust and credibility are the main pillars of a market, their erosion creates significant problems.
Furthermore, market volatility is common in countries with highly dominant foreign investor participation. When global changes, domestic security issues, policy shifts, or elections occur, foreign investors tend to quickly divest and exit. During a global capital crisis, investor flight is inevitable and a natural process.
Capital: So, how do you plan to mitigate these problems?
Hanna: Our greatest advantage lies in the legacy we possess. Hundreds of share companies have been established in Ethiopia over the past three decades. This provides us with immense leverage. If we progressively register and list these companies on the stock exchange over the next three to five years, we will achieve highly significant results.
Our second solution focuses on Small and Medium Enterprises (SMEs). We have recently established an SME Advocacy Office. We are closely monitoring the support existing SMEs receive from various donors and venture capital (VC) firms, and we will enable them to transition into public companies and issue shares within five to ten years. To avoid falling into the same traps as others, we have focused on them right from their foundational stage.
Our third solution is the ‘IPO Clinic,’ designed to bring traditionally family-owned private limited companies into the capital market by facilitating their conversion into public companies. We achieve this by offsetting regulatory compliance and IPO preparation costs through financial and technical support from various donor organizations, thereby building trust and encouraging private companies to participate in the market.
Our fourth solution focuses on bringing State-Owned Enterprises (SOEs) to the capital market. Addressing liquidity, we have several strategies. While public awareness and digital payment solutions are crucial, we also benefit from a significant demographic advantage: a population of 130 million, with 70% under 30. Furthermore, our low unemployment rate, stemming from an economy that is nearly 80% agricultural, means many individuals have disposable income, however modest. The challenge lies in thoroughly studying how to channel this collective capacity into the capital market, a direction we must pursue with special focus.
Considering this large youth population, particularly those aged 18 and older, a key question is how to transform their savings into productive investments. While this represents an enormous undertaking requiring extensive work over the next 5 to 10 years, it also presents a significant opportunity for Ethiopia to resolve its liquidity challenges.
For instance, recent data from Commercial Bank of Ethiopia (CBE) Capital highlights the potential of our population. Since November, the trading volume in the Treasury Bill (T-Bill) auction market has reached 1 billion Birr. Notably, this historic figure largely excludes banks and pension funds, representing trades executed by retail and small institutional investors who accessed the market through the investment bank. This demonstrates our capacity to leverage population size for enhanced liquidity.
Additionally, diversifying our investment products is crucial. We cannot indefinitely rely solely on equities. Ethiopia currently lacks a debt instrument market, which we must introduce. Initially, credible large corporations, starting with banks, should utilize this market. Furthermore, the issuance of the Collective Investment Scheme (CIS) directive is expected to address many of these challenges.
Looking ahead, we also plan to introduce asset digitalization or tokenization. However, given our nascent market, we must first assess the performance of conventional products. Despite this, tokenization is not a distant goal; as latecomers, we cannot afford to delay, needing to compress into a short timeframe the development path that took the rest of the world 20 years to traverse.
Addressing market volatility, another solution involves balancing the participation of various investor types within the capital market: domestic, foreign, retail, and institutional. These segments must complement one another, as sole reliance on any single group is unsustainable. For instance, in Kenya, foreign investor share dropped from approximately 68% in 2018 to about 30% today. Yet, the market remained resilient due to a significant increase in domestic investor participation, driven by both Collective Investment Schemes (CIS) and direct retail engagement. This resilience can be attributed to growing public awareness and the adoption of technological platforms. Thus, the departure of foreign investors is not inherently catastrophic, provided a robust domestic retail or institutional investor base is prepared to fill the void.
Our country’s pension funds must significantly enhance their asset capacity and broaden their investment flexibility. They cannot continuously invest solely in short-term Treasury bills; instead, they must diversify into private sector debt instruments or equities. This is crucial for matching long-term liabilities with corresponding assets. A young population today will reach retirement age in approximately 30 years, necessitating the availability of funds at that future point.
Therefore, since Treasury bills are short-term instruments, pension funds require long-term investment options, such as equities or long-term debt instruments. Empowering and preparing our institutional investors to prevent a maturity mismatch is paramount. If these measures are implemented, the market can be stabilized, even in the event of foreign investor exits. However, as we are still in the early stages of observing foreign portfolio investment patterns and have not yet fully tested market resilience, a highly watchful approach is essential throughout this process.
Another critical consideration is ownership caps. This is a contentious issue: some advocate for unrestricted free markets, while others argue that caps are vital tools for market protection. Examining the experiences of countries like Vietnam, China, and others in our region reveals a common strategy. These nations, when progressively opening their foreign portfolio investment opportunities, typically began with strict frameworks and low ownership caps, gradually extending holding or lock-in periods over time.
Investors, conversely, often contend that such restrictions infringe upon their property ownership rights, asserting their ability to exit investments at will. Nevertheless, any regulatory mechanism must strike a careful balance between attracting foreign investment and safeguarding the domestic economy.
Tempting strawberry bliss: Ethiopia’s red gold revolution
In Ethiopia’s highlands, volcanic soils and favourable temperate conditions support the production of premium strawberries, recognized as “Red Gold” alongside blueberries as “Blue Gold.” This crop has consistently delivered exceptional foreign exchange earnings per unit of land and capital deployed. Despite its superior economic performance, nutritional profile, and alignment with global demand for high-margin, sustainable produce, strawberries remain outside the country’s flagship agricultural development programs. This article presents a rigorous economic analysis of the opportunity costs of this exclusion and advocates for data-driven prioritization. Drawing on two decades of experience in Ethiopia’s horticultural export sector, the assessment integrates trade statistics, productivity metrics, and strategic benchmarking to demonstrate why strawberries warrant inclusion alongside—or ahead of—volume-oriented staples in national resource allocation
Empirical data underscore strawberries’ outsized contribution to export revenues. Approximately 521 hectares under commercial cultivation generated roughly USD 25 million in export earnings over the past five years. By contrast, the national avocado program, spanning approximately 31,000 hectares, yielded only USD 7.41 million in the same period. This translates to dramatically higher returns per hectare for strawberries—often orders of magnitude greater—highlighting superior capital productivity and land-use efficiency in a resource-constrained economy.
Historical performance (2013–2017) further validates this pattern: strawberries represented just 3.8% of fruit export volume (7,454 tons out of 202,130 tons) yet accounted for nearly 30% of fruit export revenues (USD 25.15 million). The unit value of approximately USD 3,375 per ton significantly exceeded benchmarks for bananas (USD 248/ton), avocados (USD 405/ton), and the overall fruit category average (USD 438/ton), delivering 7–8 times higher revenue per ton. Recent data reinforces the trend: in 2022, fresh strawberry exports exceeded 1.7 million kg, generating USD 5.34 million, primarily to premium Gulf markets. In 2023, the “Other fresh fruit” category—dominated by strawberries—contributed USD 5.08 million. These metrics demonstrate an optimized value-to-volume ratio that reduces exposure to bulk logistics constraints and airfreight capacity limitations while maximizing foreign exchange generation.
Avocado initiatives emphasize scale and domestic processing potential through a 15-year national program. However, in an environment of scarce arable land, foreign currency, and infrastructure, policymakers must apply rigorous marginal efficiency analysis. Prioritizing lower unit-value crops at the expense of high-intensity forex generators warrants transparent justification through formal cost-benefit and opportunity-cost frameworks.
Strawberries address Ethiopia’s twin challenges of malnutrition and rising non-communicable diseases more effectively than many alternatives. Per equivalent serving, they provide 568% more Vitamin C than avocados, lower sugar content, substantially reduced saturated fat, and favourable caloric density (32 kcal/100g). Their rich anthocyanin profile supports cardiovascular health and anti-inflammatory benefits, complementing avocados’ fiber and fat contributions. A small 1/8-acre plot can yield 30–50 kg weekly within 90 days, with a productive lifespan of 2–3 years, enabling rapid cash flow and household nutritional security for smallholders. This short production cycle and labour-intensive harvesting and packing phases also generate high employment elasticity, particularly for women.
Ethiopia’s highlands, including clusters around Holeta and Ejera, offer optimal conditions—cool nights, moderate daytime temperatures, and altitude—that enhance flavor, Brix levels (>8), and market appeal. The sector’s origins in former rose flower operations provide transferable expertise in protected cultivation, post-harvest management, and export logistics. The recent Phytophthora outbreak at Zequala Horti PLC prompted a successful collaboration with Dutch expertise, resulting in a high-tech raised-gutter hydroponic demonstration greenhouse. This initiative exemplifies precision agriculture that conserves water, mitigates disease risk, and improves quality—positioning Ethiopia for leapfrog advancement over open-field systems prevalent in neighboring countries.
Ethiopia leads East Africa in commercial strawberry production (516–600 hectares), export revenues, and unit values approaching USD 3,000+/ton. Kenya produces around 533 metric tons annually with modest export earnings, while Uganda’s sector remains negligible. Proven varieties such as Rotmi, Fragaria Soraya, Dorina, Daniel, Florida Brilliance, Monterey, and Rowena deliver yields of 30–43 tons per hectare with strong adaptability and disease resistance. Established air connectivity enables 24-hour delivery to Europe, while proximity to the Middle East optimizes costs. The Cool Port Addis at Modjo supports sea freight for IQF and processed products, enhancing flexibility and sustainability.
Demand extends beyond the Gulf to Western Europe (UK, Netherlands, France, Belgium), where Ethiopian strawberries serve food service and premium retail channels. Strategic branding as “Ethiopian Highland Strawberries,” combined with GLOBALG.A.P. and other certifications, alongside portfolio expansion into blueberries and raspberries, can capture higher margins in a growing global berries market driven by health trends.
National flagship programs for wheat, avocado, sorghum, and enset allocate significant resources for R&D, inputs, subsidies, and infrastructure based on volume and food security objectives. Strawberries’ exclusion from these mechanisms, despite superior forex intensity, rapid ROI, technological sophistication, employment generation, and nutritional impact, raises critical questions about selection criteria. Effective economic governance requires transparent, multi-criteria decision frameworks incorporating: Foreign exchange yield per hectare and per unit of scarce resources, Net present value and internal rate of return, Employment and income multipliers, Nutritional cost-effectiveness, Climate resilience and risk-adjusted returns. Regular performance audits against regional and global benchmarks would strengthen accountability and optimize resource allocation.
To realize this potential, the following actions are proposed: Incorporate strawberries as a dedicated component within the next 10-Year National Agricultural Development Plan, with ring-fenced funding and clear KPIs, Launch subsidized nucleus-outgrower schemes linking established commercial producers (e.g., Metrolax Flower, Tal Flower, Euro Flora, Zequala Horti, Bahir Dar Fresh Fruits PLC) with cooperatives to scale quality-compliant production, Accelerate adoption of hydroponics, precision fertigation, and resilient varieties through public-private partnerships, Invest in premium branding, certifications, and value-added processing (IQF, juices, powders) to extend shelf life and margins, Complete cold-chain infrastructure development, leveraging Cool Port Addis for dual air-sea competitiveness, Institutionalize multi-criteria prioritization protocols with independent economic evaluations.
These measures would enhance FDI attraction, as demonstrated by recent commitments such as those from African Farming Industries, and establish Ethiopia as East Africa’s premier high-value horticultural exporter.
To conclude Strawberries, represent a high-return, low-land-footprint opportunity that aligns tightly with Ethiopia’s goals of foreign reserve accumulation, technological upgrading, rural economic empowerment, and nutritional improvement. In a competitive global marketplace, delay carries measurable opportunity costs. By integrating “Red Gold” into flagship frameworks through evidence-based policy adjustments, Ethiopia can capture greater value from its comparative advantages, strengthen economic resilience, and build a world-class horticultural sector. The data are compelling; the strategic rationale is clear. Visionary leadership and decisive execution are now required.
Mekonnen Solomon is agricultural economist and Former Director in Ministry of Agriculture and can be reached via ehdaplan@gmail.com
Narrating a nation: Media, identity, and nationhood
Accounts of a Nation are based on sets of beliefs that are agreed upon in a community. Something as tangible as a country, its land, flag, constitution, can be challenged or changed, yet the collective understanding of what a country has been through, where it came from, and where the future is leading it is what keeps people bonded together over hundreds of years and between different places.
Ethiopia has an abundance of stories. Its rich history includes an unbroken civilization predating colonization by Westerners; an amazing military victory at Adwa that inspired Africa; a diverse population of more than 80 ethnic backgrounds and languages; the presence of an Orthodox Christian Church that has existed longer than most of Europe; and its contribution to the Nile River Basin as the only country providing water to millions of people while most of that water goes to waste because nearby countries produce nothing and have no way to share resources with each other.
However, in the last few decades the question of what actually constitutes Ethiopia’s national narrative, who has the right to define it, what experiences are included and emphasized or excluded, and what story will be told, has become one of the most contentious and important issues in Ethiopia today. The “battle” for Ethiopia’s national narrative is as much about politics as it is about media; and media are not simply neutral bystanders in this political dispute—they are part of the battle.
The Making of the National Narrative
The national narrative of Ethiopia has historically been the same throughout the country’s modern history. In Ethiopia’s recent history, all of the major political powers that ruled have always sought to manipulate or completely censor the content of the national narrative, and use censorship mechanisms and mechanisms to monitor abuse against the individual, or independent, media; the emperor was an enemy when the Derg controlled Ethiopia, and the Derg became an enemy after the EPRDF took control, but, every time, the controlling force did maintain the same structural logic; the state controlled the story, and the story served the state.
The EPRDF was theoretically going to completely change the structure of the nation; the EPRDF enshrined ethnic federalism with the 1995 Constitution, thus, affirmatively recognizing the rights of all nations, nationalities, and peoples to self-determination; creating new regional states based on ethnicity; designating and giving official status to regional languages; and creating regional broadcasters in order to provide a voice to identities that had been historically silenced. As a result, the national story, in theory, became a collection of stories from across the nation, or a federation of stories.
However, the legal construct of a story and how members of the nation experience a story are two very different things. The question of what is the national story, or who represents the national story, has never really been addressed, but only managed, or ignored, until it eventually erupts.
What Media Liberalization Unleashed
When Abiy Ahmed took office in April 2018, he quickly set out to reform Ethiopia’s media system by freeing jailed journalists; opening up previously blocked websites; and bringing back into the country many of the journalists and writers that had temporarily fled due to their writing and/or broadcasting. Many viewed this as the beginning of a free press in Ethiopia, and they were correct. However, in a country as divided as Ethiopia, freedom does not equate to pluralism; it equates to amplification.
What was amplified through the reform of Ethiopia’s media was not an inclusive national story with many diverse voices; rather, it was amplified ethnic narratives that sought to challenge each other’s right to determine what constitutes “Ethiopia.” In addition, research supports that ethnicity is now the primary driver of media polarization, replacing the historical divide between the state and private media. Furthermore, within each community, there is a wide variety of outlets; however, these outlets emphasize the grievances of their respective communities, while minimizing or denigrating the grievances of neighboring communities. Ultimately, rather than being one nation with many stories, Ethiopia consists of numerous competing nations that occupy the same geographical area.
The Tigray conflict has exemplified the destructive nature of this polarization. For example, following the start of the Tigray conflict, the government media establishment in Ethiopia produced a variety of messages blaming the Tigrayans as a group for the conflict, while various Tigray-based and diaspora based media organizations issued messages expressing the view that the Ethiopian government was committing genocide. Each of the corresponding hashtags (#EthiopiaPrevail and #TigrayGenocide) mobilized significant resources; entrenched opposing views; and escalated the violence of the war that has resulted in the death of hundreds of thousands of human beings.
When competing narratives share no common ground, no dialogue, and no shared framework for truth, the outcome is not debate. It is war.
Medemer and the Search for a Shared Ethiopian Story
Abiy Ahmed developed Medemer, a political philosophy, and introduced to Ethiopia’s damaged environment. Medemer is an example of a vision in terms of both objectives and locale. The development of this philosophy began with a book written by Abiy, followed by the use of state media to communicate his vision to the public, as well as the merging of ruling political parties into one party called the “Prosperity Party,” better than what had come before it.
The state media communicated Medemer as the new national story to tell. Evidence of its promise can be seen by the creation of the Grand Ethiopian Renaissance Dam, which symbolically is the basis for demonstrating the realities of Medemer.
However, the political realities of Ethiopia do not match what is claimed by Abiy in terms of forward-thinking and the promises made within his philosophy, the result being that in approximately the first month of Abiy’s appointment to office, numerous political “alignment” and “disalignment” occurred with a number of political factions throughout the country. The potential for examining the differences between the Medemer philosophy and the realities of combat, displacement, and ethnic violence, as well as being supported by other forms of media, has not occurred. The state media supported the philosophy without question, whereas independent media sources were subjected to harassment and to shutdowns for questioning or not supporting the Medemer philosophy. Therefore, the new national story has been based upon aspirations, not upon the realities of the actual results of Abiy’s vision.
Toward a More Responsible National Narrative
The media in Ethiopia does cover the country, however the coverage is typically filtered to aligns with either specific ethnic groups’ or government interests of the Ethiopian state. Therefore, independent journalism, offering some courage to report simultaneously for the entire spectrum of Ethiopian identities dependent on no political master, is absent therein.
To quote an Ethiopian editor: “You cannot imprison your way to a unified information space.” Merely suppressing damaging narratives does not eliminate it; it re-distributes them and drives them into a more extreme state. The number of one-sided Youtube channels and other platforms run by exiled journalists is evidence of what a closed domestic journalism environment produces.
A credible narrative for the entire country must be housed by the Ethiopian media, in its newsrooms. An Ethiopian narrative would document the Battle of Adwa as well as the Irreechaa massacre as equally a part of Ethiopian history. A credible narrative would have reported about the GERD not only as an engineering marvel, but also as a major point of political contention. A credible narrative would incorporate Tigrayan, Amhara, Oromo, Somali, Afar, and Sidama voices not as ethnic representatives, but as citizens possessing overlapping, intricate identities that transcend ethnicity.
Lastly and most importantly, a credible narrative would not suggest the false binary that exists between pan-Ethiopianism and ethno-nationalism. Most Ethiopians do not occupy either extreme; rather, they occupy both, and journalism has a responsibility to meet the Ethiopian people at their intersection point.
Ethiopia: A Nation Still Being Written
According to Benedict Anderson, the shared imagination of people who have never met creates the idea of a nation, not blood or territory. Ethiopia’s imagination has always been vast enough to encompass its diversity—but will this be possible in 2026? Will Ethiopia’s media be able to share and portray that diversity?
At this point in time the answer is no, but we have the building blocks for a better environment. These include fact-checkers (working in various languages) who are able to work across ethnic lines to report on communities, and journalists and editors who are committed to the idea that complexity is not disloyalty.
The narrative of Grand Ethiopia will not come from the government or any one ethnic group or the diaspora abroad. It will be slowly and imperfectly created by journalists who are committed to telling the whole truth about the whole country, a task that has barely begun. It must begin now.
The writer can be reached via moges4994@gmail.com
