Thursday, October 22, 2026
Home Blog Page 214

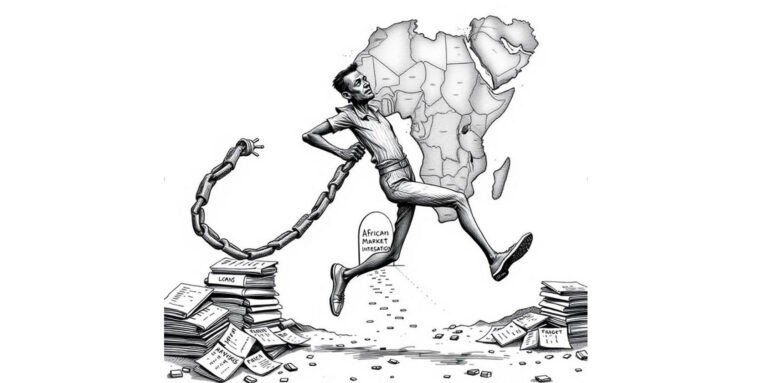
Africa can break the debt trap by trading more with itself

0

Africa’s debt crisis will not be solved by borrowing alone, nor by waiting for rescue from outside the continent. The more durable answer is to grow the continent’s own markets, strengthen production, and expand intra-African trade so that African economies can generate more of the revenue they need at home.

For decades, many African countries have relied on external financing to cover budget gaps, fund infrastructure, and stabilize currencies. That model has left governments vulnerable to exchange-rate shocks, rising global interest rates, and sudden changes in investor sentiment. When debt service rises, social spending, development programs, and public investment are usually the first to suffer. The result is a cycle in which countries borrow to survive, then borrow again to repay the last round.

Breaking that cycle requires a shift in strategy. Africa must stop treating itself mainly as a collection of small national markets and start behaving like one large economic space. The African Continental Free Trade Area is the clearest path toward that goal. If it is implemented seriously, it can create scale, deepen industrialization, and keep more value within the continent. But trade agreements alone are not enough. Governments must remove the practical barriers that still make it easier to trade with Europe, Asia, or the Gulf than with a neighboring African country.

The first barrier is infrastructure. Goods cannot move cheaply across Africa if roads are poor, rail links are weak, ports are congested, and border posts remain slow and unpredictable. A trader in Kigali should not face more difficulty shipping to Nairobi than to Rotterdam. The same applies to a manufacturer in Accra trying to sell in Abidjan or a farmer in Ethiopia trying to access regional markets. Better logistics is not a luxury; it is the foundation of trade-led growth.

The second barrier is regulation. African businesses still face a patchwork of customs rules, product standards, permit systems, and payment procedures. These frictions raise costs and discourage cross-border commerce. Governments should harmonize standards, simplify customs procedures, and digitize clearance systems so that goods can move faster and more transparently. Regional trade should not depend on political speeches; it should depend on predictable systems that firms can trust.

The third barrier is finance. African trade needs African money. One reason intra-African trade remains underdeveloped is that many transactions are still settled in foreign currencies, exposing firms to exchange-rate risk and higher costs. Regional payment systems, local-currency settlement arrangements, and stronger correspondent banking links can reduce those burdens. If an importer in Uganda can pay a supplier in Tanzania more easily in regional currency, trade becomes simpler and cheaper. That is how markets deepen.

Africa also needs to build more regional value chains. Too many countries export raw materials and import finished goods at a premium. That pattern drains foreign exchange and leaves economies exposed to price swings. Instead, countries should specialize within the continent: one producing inputs, another processing them, another assembling finished goods, and others providing logistics and services. This is how trade becomes a ladder out of debt rather than another reason to borrow.

At the same time, governments must support small and medium-sized enterprises, which are the backbone of any meaningful regional trade system. Large firms can navigate high compliance costs and distant markets, but smaller businesses often cannot. If Africa wants trade to reduce debt pressure, SMEs need access to trade finance, market information, insurance, and export support. Without them, intra-African trade will remain a policy slogan rather than an economic engine.

There is also a political dimension. African leaders must resist the temptation to measure success by how much external financing they attract. The better measure is how much domestic wealth they mobilize and how much regional trade they enable. A continent that consumes what it produces, processes more of what it exports, and circulates capital within its own markets will be less dependent on lenders and more resilient in a volatile world.

Debt will not disappear overnight. Many countries will still need external financing for some time. But the terms of dependence can change. If Africa trades more with itself, it will earn more in local value, build more industrial capacity, and reduce the foreign exchange drain that makes debt so dangerous. Intra-African trade is not just a commercial agenda. It is a debt strategy, a development strategy, and a sovereignty strategy.

The continent’s future will not be secured by borrowing its way forward. It will be secured by building an economy that can stand on its own feet, with African goods, African markets, and African confidence at the center.
How Africa can escape the debt trap

0

The narrative that Africa faces a persistent debt crisis has become entrenched. In fact, despite representing nearly one-fifth of the world’s population, the continent accounts for less than 3% of global sovereign debt. By contrast, the European Union and the United States account for a much larger share (nearly 16% and more than 34%, respectively). Moreover, Africa’s average debt-to-GDP ratio, at 67%, is markedly lower than those of Europe (88.5%), the US (122.6%), and Japan (236.7%).

Nonetheless, many countries on the least-indebted and most capital-starved continent remain stuck in a debt trap. On May 12–13, Senegal will host an international conference to address the country’s escalating debt crisis and, crucially, one of its main drivers: the structural asymmetries embedded in the global financial system. This flawed architecture has obstructed Africa’s access to affordable, long-term capital and prevented the continent from diversifying its sources of economic growth and trade, transforming debt from a manageable development instrument into a self-perpetuating cycle of vulnerability.

In particular, the shift toward costly, short-term, market-based borrowing amid declining concessional lending has trapped African countries in cycles of indebtedness and external dependence. Constrained by fragmented monetary landscapes and underdeveloped domestic financial markets, African countries are forced to borrow in foreign currencies, mainly the US dollar. This leads to currency mismatches and exposes these countries to disorderly capital outflows and exchange-rate and interest-rate risks, especially monetary-policy shifts by the US Federal Reserve and other major central banks.

The balance-of-payments constraint associated with dollar funding creates a negative feedback loop. Exogenous economic shocks trigger capital flight to safe havens, sudden stops in financial inflows, and currency depreciation, all of which exacerbate the debt burden. Policymakers enact fiscal austerity, leading to a further slowdown in economic growth and revenues that make it even harder to service debt in the future.

Credit-ratings agencies such as S&P, Fitch, and Moody’s deepen the debt trap by assigning most African countries lower ratings, which substantially elevate their borrowing costs and limit their market access. Sovereign bonds issued by African countries typically yield 8–15%, in sharp contrast to yields of 1–5% in Europe and North America. These spreads impose high macroeconomic costs. According to the United Nations Development Programme, credit-ratings agencies’ subjective evaluations have cost African countries an estimated $74.5 billion.

These additional costs help create a debt overhang. Interest payments now account for more than 20% of government revenue in several African countries—including around 40% in Nigeria and over 70% in Egypt—thereby imposing significant opportunity costs on development. Resources that could be allocated to infrastructure, industrial policy, human-capital development, and technological upgrading are instead redirected to debt servicing.

In short, Africa is paying so much not because of the amount of debt it has accumulated, but because of how that debt is structured and perceived. For African countries, it costs more to borrow less, setting unrealistic return-on-investment expectations that further undermine debt sustainability. As a result, a growing number of African countries have pursued rollovers and refinancing options, such as issuing new eurobonds, to settle maturing obligations—falling deeper into the debt trap.

This has accelerated the shift in recent decades from long-term concessional loans to short-term commercial debt. Private creditors now hold more than 40% of Africa’s external public debt, up from 17% in 2000. Loans with shorter maturities compress repayment timelines, increase refinancing risks, and are misaligned with Africa’s long-term development objectives. They also raise the risk of maturity clustering. This year, for example, African countries face a record $90 billion debt wall driven by maturing eurobonds. Difficult tradeoffs will likely be necessary.

At the same time, Africa faces other economic constraints. The continent loses more than $50 billion annually in illicit financial outflows through trade misinvoicing, abusive transfer pricing, and tax avoidance. The global financial system enables these leakages with secrecy jurisdictions and limited multilateral cooperation on international taxation.

Moreover, the erosion of human capital and a chronic infrastructure deficit in an austerity-prone operating environment leave many African economies vulnerable to commodity shocks that drive external liabilities higher. When balance-of-payments crises invariably materialize, African governments are compelled to borrow in foreign currencies and implement adjustment programs that prioritize short-term fiscal consolidation over long-term development. (These programs’ procyclical austerity measures can help stabilize public finances but often weaken state capacity and lower potential economic growth). Over time, this leads to repeated cycles of borrowing, crisis, and adjustment—the very definition of a debt trap.

To break the cycle of dependency and accelerate development, policymakers must redesign the global financial architecture. Aligning debt maturities with longer-term development objectives requires improving access to concessional financing, which can be achieved by strengthening development-finance institutions’ capital base. At the regional level, policymakers must fast-track monetary integration and the development of deeper domestic capital markets to support long-term borrowing in local currencies and address structural mismatches between currency denomination and revenue generation.

It is also crucial to reform credit-ratings agencies’ methodologies to achieve parity in access to affordable development finance, and to reduce the incidence of procyclical policies. This will not only rebuild these institutions’ credibility but also foster economic growth and sustainable development. Lastly, the international community should regard fiscal consolidation and debt sustainability as being in service of a broader goal: to promote Africa’s economic development.

Africa is not heavily indebted; it is a victim of deep-seated inequalities, underpinned by an international financial architecture that prevents structural economic transformation and perpetuates debt crises. If the world is to harness Africa’s demographic dividends and unlock its growth potential, both of which are essential to maintaining financial stability worldwide, the institutions, rules, and norms of global governance must become more balanced and development-oriented.

Federal Police uncover counterfeit tissue network, seek more time to probe suspect

0

The Federal Police Crime Investigation Bureau says it has uncovered a large-scale counterfeit distribution network that allegedly harmed market stability, reduced tax revenue and put public health at risk through the sale of substandard products.

Investigators appearing before the Federal First Instance Court, Arada Division First-Instance Criminal Bench, requested a 14-day remand extension to continue their probe into the main suspect, Seyid Mohammednur Umer. Police said the case involves trademark infringement and a wider criminal network that was targeting both the economy and consumers.

According to court documents, the alleged operation ran counter to the government’s recent macroeconomic reforms, which are aimed at stabilizing markets, curbing inflation and improving consumer welfare. Police said the network also deprived the state of significant tax revenue and distorted fair competition in the market.

In their application to the court, investigators said the suspect had used the “VIVa” tissue trademark, registered under International Class 16 by Pure Wood Pulp & Paper Packaging PLC with the Ethiopian Intellectual Property Authority, without the owner’s consent.

Police said they received tip-offs indicating that the suspect had been illegally copying Viva Tissue packaging since 2024 and flooding the market with counterfeit products. They said the alleged operation was not limited to Addis Ababa, but extended to regional towns through a covert network of representatives and accomplices.

Beyond the economic damage, police warned that the counterfeit tissue posed serious health risks to consumers. They said the fake product was reportedly made from substandard waste materials and hazardous chemical additives, unlike the genuine product, which is manufactured under quality controls.

Police told the court that the suspect could destroy evidence, alter facts or intimidate witnesses if released while the investigation continues. They therefore asked for more time to collect testimonial and documentary evidence.

However, during the court session on 5 June 2026, the bench granted a seven-day remand extension instead of the 14 days requested. The case was adjourned to 11 June 2026 for a progress update on the investigation.

NBE allows embassies, foreign investors to import fuel under Franco-Valuta scheme

0

The National Bank of Ethiopia has introduced a new directive allowing embassies, international organizations and foreign direct investors to import fuel using their own foreign currency, in a move aimed at easing pressure on the country’s strained foreign exchange system.

The directive, signed by National Bank Governor Eyob Tekalign and effective as of 29 May 2026, permits eligible institutions to bring in refined petroleum products under the Franco-Valuta system, which allows imports without drawing foreign currency from Ethiopia’s domestic banking system.

Officials and industry experts say the new framework is designed to help stabilize the macroeconomy by reducing pressure on foreign currency reserves while keeping imported fuel out of the domestic retail market. Under the directive, fuel imported through Franco-Valuta cannot be sold to the public, transferred to third parties or mixed with ordinary commercial fuel supplies.

For more than five decades, the state-owned Ethiopian Petroleum Supply Enterprise was the sole legal importer of refined petroleum products. It was responsible for assessing national demand, negotiating purchases, managing tenders and overseeing strategic fuel depots. Fuel distributors and gas stations have traditionally bought from the state enterprise rather than importing independently.

That centralized system helped the government control fuel supply and retail prices, but it also left Ethiopia highly exposed to external shocks. Fuel is the country’s largest import item, costing an estimated $4.2 billion a year and accounting for roughly a quarter of total imports.

The latest directive comes as fuel markets have been hit by international disruptions, including conflict in the Middle East and pressure on strategic shipping routes such as the Strait of Hormuz. For landlocked Ethiopia, the problem has been compounded by a chronic shortage of foreign currency, making it difficult to finance timely fuel purchases.

In recent months, the government has been forced to provide billions of birr in fuel subsidies, but that approach has proved increasingly difficult to sustain. Authorities have also introduced a quota system that prioritizes fuel for defense, public transport and key manufacturers, while ordinary motorists in Addis Ababa have often faced long waits at filling stations.

The new Franco-Valuta directive is intended to provide an additional channel for fuel supply without putting further strain on the banking system. Franco-Valuta is a mechanism that allows eligible importers to pay with foreign currency held abroad rather than requesting hard currency from Ethiopian banks.

The National Bank said previous regulations had allowed some Franco-Valuta practices but lacked a clear legal framework. It said that gap had contributed to customs misclassification, distorted reporting, capital control violations and illicit financial flows.

Under the new rules, fuel imported for the own use of embassies, international organizations and foreign investors has now been explicitly added to the list of goods that may be brought in through Franco-Valuta. However, the bank stressed that the arrangement does not open the general fuel market to private traders.

To clear fuel through customs, importers must present a supporting letter from the relevant government institution confirming their fuel needs, along with a valid diplomatic or investment license. The directive does not set a specific dollar ceiling for fuel imports, saying volumes will be determined by the issuing institution’s assessment of need.

The bank has also established a digital monitoring system to track every shipment from customs to the point of use. The Ethiopian Customs Commission will be required to register each Franco-Valuta shipment in the central bank’s new monitoring platform.

According to the directive, any false declaration, diversion of fuel or attempt to bypass the system will trigger administrative and legal penalties.