Thursday, October 15, 2026
Home Blog Page 37

Tigray, Amhara, Gambella lead disability rates as Federation rejects survey findings

0

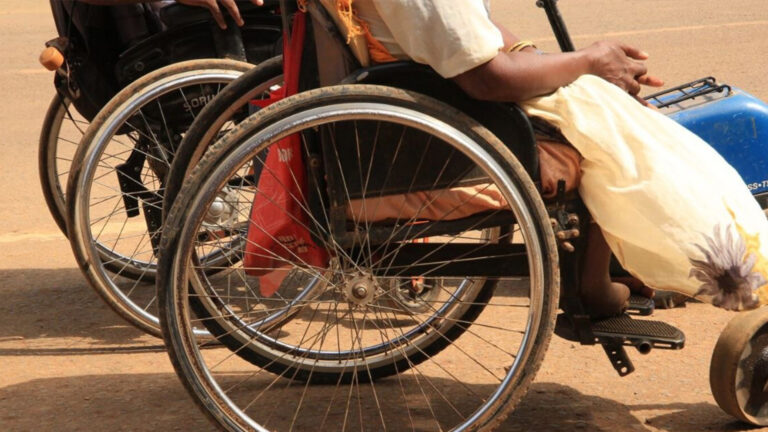
A new National Disability Survey reports that Tigray, Amhara, and Gambella have the highest household-level disability rates in Ethiopia. However, the National Federation of Disabled Persons’ Associations has rejected the findings.

The Ethiopian Policy Institute, in collaboration with UNICEF and Inclusive Development Partners, released the National Disability Survey Report on September 23, 2026. The survey estimates that 5.8 percent of Ethiopia’s total population lives with disabilities, with rates of 5.79 percent among females and 5.77 percent among males.

The survey gathered data from 9,200 households and 42,269 household members across all regions and city administrations, excluding individuals in prisons, medical facilities, and those experiencing homelessness.

Covering the period from the end of the war in northern Ethiopia through December 2024, the study found that conflict-affected regions, particularly Tigray, Amhara, and Gambella, recorded the highest household-level disability rates.

Specifically, 30 percent of households in Tigray have at least one member with a disability, compared to 25.8 percent in Amhara and 22 percent in Gambella. Sidama, Southern Ethiopia, and Afar were identified as regions with relatively lower disability rates.

The National Federation of Disabled Persons’ Associations has rejected the survey, citing inadequate involvement in the research process and the exclusion of their feedback from the final report.

Abayneh Gujo, the federation’s Director General, informed Capital that the organization was not involved in the survey from its inception, only being invited to review the findings.

“We did not participate in this survey from the beginning,” Abayneh stated. “Since it was a study conducted without our participation, we do not believe that it is accurate and beneficial to the country.”

He noted that previous national data estimated the proportion of people with disabilities at 1.1 percent, while international organizations like the World Bank and the United Nations have cited figures around 17 percent.

Abayneh also expressed concern that the new findings might be used for future policymaking without sufficient consultation with organizations representing people with disabilities.

He anticipates that the proportion of people with disabilities will rise to 10 percent or more of the population due to factors such as armed conflict, road traffic accidents, and natural disasters.

Kaleab Kebede, a gender and child development researcher at the Ethiopian Policy Research Institute who participated in the survey, explained that the study aimed to clarify the extent of disability in Ethiopia and identify the challenges faced by people with disabilities.

According to the survey, people with disabilities encounter significant social, economic, and political barriers. Children with disabilities are 24 percent less likely to access education than their non-disabled peers, and about half are unable to read and write.

Families of people with disabilities also face higher healthcare and education costs. In urban areas, 66 percent of people with disabilities are unemployed.

Kaleab highlighted infrastructure and accessibility as major challenges, with only 13 percent of people with disabilities using assistive devices or support equipment.

The survey identified war, road traffic accidents, natural disasters, and injuries during pregnancy as major reported causes of disability.

At the household level, the disability rate was 17 percent in urban areas and 22 percent in rural areas, resulting in a national average of 20 percent.

African governments lead new push to finance forest protection

0

African governments are developing new models to finance forest protection and restoration, with Ethiopia, Kenya, Nigeria and Gabon emerging as key examples of how domestic budgets, international support, carbon finance and results-based payments can be combined to protect forests while supporting economic development.

The examples are highlighted in the first Progress Report of the Forest Finance Roadmap, released on September 23 during the Forest & Climate Leaders’ Partnership Forest Finance Day at Climate Week NYC.

The report says credible forest-finance mechanisms are beginning to gain momentum, but warns that investment is still moving too slowly to meet the global commitment to halt and reverse forest loss by 2030.

Forests receive less than 1% of global climate finance despite offering an estimated one-fifth of the world’s cost-effective climate-mitigation potential, according to the report. The Forest Finance Roadmap was established to help close an estimated annual forest-finance gap of US$66.8 billion.

Africa is central to that effort. The continent is home to about 663 million hectares of forest, representing around 16% of the world’s forest area. The future of these forests will be critical to international efforts to cut emissions, protect biodiversity, strengthen food systems and support climate resilience.

The report argues that African countries are increasingly moving beyond calls for international conservation funding and are creating country-led systems that connect forest protection with national development priorities, local livelihoods and public investment.

“Forests cannot be an afterthought in the international climate agenda,” said Emelyne Cheney, Director of the Forest & Climate Leaders’ Partnership Secretariat. “They need to remain at the centre of it.”

Cheney said the report offers a clearer picture of where forest finance is flowing and where gaps remain.

“Pressures on forests are intensifying and the solutions are clear, but they need sustained political attention and investment at scale to turn into action,” she said.

Ethiopia is highlighted as an example of how domestic public financing can support long-term restoration and attract additional international investment.

Land degradation is estimated to cost Ethiopia about US$4.3 billion annually through reduced agricultural productivity and the loss of ecosystem services. In response, the federal government is allocating between 0.5% and 1% of its annual budget—estimated at US$40 million to US$80 million each year—to the Green Legacy and Landscape Restoration Fund.

The nationally owned mechanism supports forest and landscape restoration and has helped Ethiopia attract hundreds of millions of dollars in concessional finance and co-financing from development partners.

The approach seeks to make forest restoration part of core economic planning rather than treating it as a stand-alone environmental activity. By investing public resources, Ethiopia aims to support watershed protection, agricultural productivity, soil health, biodiversity and rural livelihoods while creating a stronger basis for private and international investment.

In August, Ethiopia also became the 17th country to endorse the Intergovernmental Land Tenure Commitment, strengthening political backing for the rights of Indigenous Peoples and local communities in forest and land landscapes.

Ethiopia’s role is expected to receive greater international attention as Addis Ababa prepares to host COP32 in 2027. The report said this provides an opportunity for the country and other African governments to shape the global forest-finance agenda from a position of demonstrated leadership.

Kenya has mobilised at least US$229 million in new external finance for forest- and landscape-based economic development, according to the report.

The funding includes a US$200 million World Bank operation and a US$29.2 million Green Climate Fund grant focused on the Lake Region. The finance is intended to support restoration, sustainable land use and the development of economic activities linked to healthy landscapes.

Kenya has also increased its domestic forestry budget. The country raised its allocation by approximately US$38.7 million in the 2025/26 fiscal year and retained a higher forestry budget of about US$143.8 million for the 2026/27 fiscal year.

The report points to a wider pipeline of investment in Kenya’s forest bioeconomy, including institutions seeking to mobilise US$10 billion by 2030. It also notes commitments covering 3.7 million hectares for protection and restoration.

The Kenyan model demonstrates how domestic public spending can complement multilateral climate finance. By combining external funds with national budget allocations, governments can create stronger conditions for long-term investment in restoration and forest-based value chains.

Nigeria is preparing to launch its Securing Nigeria’s Forest Future Country Package internationally at COP31 in Türkiye later this year.

Developed with support from the Forest & Climate Leaders’ Partnership, the package is designed as a government-led framework that aligns forest, climate and biodiversity objectives with investment from development partners, financial institutions, philanthropic organisations and private businesses.

The initiative aims to strengthen forest management, restore degraded land, conserve biodiversity and build climate resilience. It also seeks to improve conditions for private-sector investment, blended finance and carbon-finance projects.

Nigeria’s Minister of Environment, Balarabe Abbas Lawal, said forest finance must produce practical benefits for communities.

“We must strengthen the enabling environment for private investment, blended finance [and] carbon finance, and ensure these investments translate into real benefits,” Lawal said. “That includes livelihoods linked to conservation, commercially viable forest value chains, meaningful participation for women and young people in the green economy, and recognition of forest-dependent communities as partners, not bystanders, in sustainable forest management.”

The Nigerian package reflects a wider shift in forest policy, where governments are seeking to use environmental finance not only for conservation but also to support jobs, enterprise development and local economic resilience.

Gabon is advancing results-based models intended to generate greater economic value from keeping forests standing. The country is a partner in the Central African Forest Initiative, known as CAFI, which is developing a payments-for-ecosystem-services pipeline across the Congo Basin.

CAFI’s current pipeline totals US$290 million and has an ambition to mobilise up to US$2 billion by 2035 from domestic and international public and private sources.

The programme aims to reach about 7.8 million direct beneficiaries and enrol approximately 2.9 million hectares in payments for environmental services and related performance-based schemes. At least half of the programme’s resources are intended to flow directly to farmers, local communities and Indigenous Peoples.

Gabon launched its Forest & Climate Leaders’ Partnership Country Package in 2025, creating a national framework to align forest, climate and development priorities with investment and international partnerships.

The Congo Basin contains one of the world’s largest remaining tropical forest systems and plays a major role in global climate regulation. The report suggests that results-based payments and ecosystem-service finance could help provide an alternative economic rationale for forest protection in countries that face pressure to exploit natural resources for short-term revenue.

The report also points to broader innovation across the continent. Côte d’Ivoire has introduced Africa’s first Sustainability-Linked Finance Framework and secured West Africa’s first sustainability-linked sovereign loan, worth €433 million. Uganda, meanwhile, is piloting an approach to integrate forest and agricultural resilience into sovereign debt and credit analysis.

Taken together, the initiatives show that African governments are beginning to place forests more firmly within national economic, financial and investment strategies.

However, the Forest Finance Roadmap warns that the scale of finance remains far below what is needed to halt deforestation and land degradation by 2030. The key test, it says, will be whether these models can attract and deploy finance fast enough—and ensure that the benefits reach local communities, farmers and Indigenous Peoples.

The report concludes that the mechanisms are increasingly available. What is now needed is sustained political commitment, larger investment flows and faster implementation to turn forest protection into an economic opportunity for African countries and their communities.

Economic Nationalism and the Global Political Economy

0

Economic nationalism has re-emerged as a defining force in the contemporary global political economy, reshaping trade regimes, industrial policy, and the relationship between states and markets. Once regarded as a relic of protectionist eras, it has returned in new forms under conditions of intensified globalisation, strategic competition, and domestic political backlash against inequality. From tariffs and industrial subsidies to reshoring strategies and supply-chain security policies, governments are increasingly prioritising national economic resilience over unfettered global integration. This shift reflects not merely ideological change, but deeper structural tensions within the architecture of global capitalism.

At its core, economic nationalism refers to the prioritisation of domestic economic interests jobs, industries, and strategic sectors, over international efficiency or comparative advantage. Historically, it has been associated with mercantilist doctrines and protectionist trade regimes. However, in the contemporary context, it is better understood as a strategic recalibration of state-market relations in response to global interdependence. Rather than rejecting globalisation outright, modern economic nationalism seeks to manage and selectively reverse it in ways that enhance national autonomy and geopolitical leverage.

The resurgence of economic nationalism can be traced to several interconnected developments. First, the uneven distributional effects of globalisation have generated significant political discontent in advanced economies. While global trade and investment have contributed to aggregate growth, the gains have been unevenly distributed, with deindustrialised regions and lower-skilled workers experiencing stagnating wages and job losses. This has fuelled populist political movements that frame globalisation as a zero-sum process that disadvantages domestic populations.

Second, the 2008 global financial crisis fundamentally undermined confidence in neoliberal models of deregulated markets and self-correcting financial systems. The crisis exposed deep vulnerabilities in highly integrated global financial networks, leading to widespread state intervention and a renewed recognition of the importance of regulatory oversight. In the aftermath, many governments began to reconsider the assumption that market liberalisation would automatically deliver stability and prosperity.

Third, rising geopolitical tensions, particularly between the United States and China, have reinforced the strategic dimension of economic policy. Economic interdependence is increasingly viewed not as a guarantee of peace, but as a potential source of vulnerability. Supply chains, semiconductor production, and critical infrastructure have become sites of geopolitical competition, where states seek to reduce dependency on rival powers. This has led to policies aimed at “de-risking” or “decoupling” key sectors of the global economy.

One of the most visible expressions of contemporary economic nationalism is the resurgence of industrial policy. Governments across the world are actively subsidising strategic industries such as renewable energy, semiconductors, and advanced manufacturing. The United States’ CHIPS and Science Act and the European Union’s Green Deal Industrial Plan are emblematic of this shift. These policies reflect a belief that markets alone are insufficient to ensure national competitiveness in critical sectors, particularly where scale, innovation, and strategic coordination are required.

However, economic nationalism also introduces significant tensions into the global political economy. One key concern is the risk of fragmentation in the international trading system. Institutions such as the World Trade Organization were designed to promote open markets and constrain unilateral protectionist measures. Yet the increasing use of subsidies, export controls, and tariffs challenges the normative and legal foundations of this system. As states prioritise domestic resilience, the coherence of global trade governance is weakening.

Another tension lies in the potential for inefficiency and retaliation. Classical economic theory suggests that protectionist measures distort resource allocation and reduce aggregate welfare by insulating domestic industries from global competition. While strategic protection may yield short-term political and industrial benefits, it can also provoke retaliatory measures from trading partners, leading to trade disputes and reduced global efficiency. The US–China trade tensions illustrate how economic nationalism can escalate into broader economic conflict with global consequences.

Yet, it would be overly simplistic to interpret economic nationalism as purely regressive. In certain contexts, it may function as a corrective mechanism to the excesses of hyper-globalisation. Dani Rodrik’s “political trilemma of the world economy” argues that democracy, national sovereignty, and deep economic integration cannot all be simultaneously maximised. From this perspective, economic nationalism represents an attempt to restore democratic control over economic policy in the face of global constraints that limit domestic policy autonomy.

Furthermore, economic nationalism can serve legitimate developmental objectives. Historically, many successful late-industrialising economies, including South Korea, Japan, and Taiwan used selective protectionism and state-led industrial strategies to build competitive industries. These cases demonstrate that strategic state intervention can, under certain conditions, foster innovation and structural transformation. The contemporary revival of industrial policy in both advanced and emerging economies reflects a renewed interest in these developmental experiences.

Nevertheless, the effectiveness of economic nationalism depends heavily on institutional capacity and policy design. Poorly implemented protectionist policies can entrench inefficiency, encourage rent-seeking, and reduce innovation. Conversely, well-targeted industrial strategies require strong bureaucratic institutions capable of coordinating investments, evaluating performance, and withdrawing support from underperforming sectors. Without such capabilities, economic nationalism risks becoming a vehicle for political patronage rather than economic development.

The environmental dimension of economic nationalism further complicates its assessment. Climate change has introduced new imperatives for state intervention in markets, particularly in accelerating the transition to low-carbon economies. Green industrial policies often involve subsidies, carbon tariffs, and regulatory frameworks that prioritise domestic clean-energy industries. While these measures may be framed in national terms, they also contribute to global public goods. However, if implemented competitively rather than cooperatively, they may generate tensions between states competing for leadership in green technologies.

Financial markets also play a critical role in shaping the trajectory of economic nationalism. Global capital flows can both constrain and enable national policy autonomy. While governments may pursue nationalist economic policies, their ability to do so is often mediated by investor confidence, exchange rate stability, and access to international finance. This creates a structural tension between national economic priorities and global financial integration. In this context, economic nationalism does not eliminate global interdependence but rather reconfigures it.

In conclusion, economic nationalism represents a significant transformation in the global political economy rather than a simple reversal of globalisation. It reflects deep-seated tensions between efficiency and resilience, integration and sovereignty, and global markets and domestic democracy. While it offers potential benefits in terms of industrial strategy, economic security, and democratic accountability, it also carries risks of fragmentation, inefficiency, and geopolitical conflict. The challenge for policymakers is not to choose between globalisation and nationalism, but to design hybrid frameworks that balance openness with strategic autonomy. The future of the global political economy will likely be defined not by the triumph of either globalism or nationalism, but by their uneasy and evolving coexistence.

ATLS rail plan could change Ethiopia’s fuel route

0

Steel tanks are rising at Djibouti’s Doraleh Multipurpose Port. If ATLS’s plan succeeds, the terminal will do more than store fuel: it will load it directly onto trains bound for Ethiopia. That would mark a first for fuel imports into Ethiopia and give the heavily road-dependent fuel corridor a new way to move large volumes inland. The prospect is fewer tanker journeys on suitable routes and a closer link between ships, storage and rail. Whether it delivers those gains will depend on the railway connection and the way the system is run.

The African Terminal & Logistics Services (ATLS) project is designed as a petroleum storage and distribution hub connecting maritime imports with Ethiopia’s road and railway networks. Its first phase is expected to provide 288,000 cubic metres of storage and be commissioned by June 2027. Longer term, planned capacity could reach about 750,000 cubic metres.

Ethiopia imports much of its petroleum through Djibouti, and fuel has to be stored, loaded and moved inland before it reaches businesses and households. The route remains heavily dependent on tanker trucks. Roughly 350 trucks reportedly carry fuel from the Horizon Djibouti Terminal to Ethiopia each day, while congestion, border procedures, truck availability and shipping delays can all affect supply.

More storage can help ease that pressure. Operators can receive fuel from vessels, hold it near the port and dispatch it when demand or transport capacity allows. That separates ship arrivals from the immediate availability of trucks or rail wagons, giving the supply chain more room to respond to disruption and changing demand.

The added tank capacity could also give Ethiopia more room to build and maintain fuel safety stocks close to its main maritime gateway. These reserves would provide a buffer against shipping delays or short-term supply disruptions, strengthening national energy security while allowing imports to be stored before dispatch inland.

ATLS’s planned train-loading arms are the project’s most distinctive feature. They are intended to speed loading and handle more railway wagons, allowing fuel to move from the terminal onto the Ethio-Djibouti Railway. Direct rail loading would be new for ATLS and could open a practical route for carrying petroleum inland in bulk.

For long-distance movements, rail can carry volumes that would otherwise require many tanker truck journeys. Shifting some suitable traffic to trains could reduce pressure on the road corridor and make fuel dispatch more efficient. It would also give Ethiopia another way to move fuel when truck capacity is tight. The scale of any benefit will depend on reliable service, wagon availability and coordination across the route.

That connection is not automatic. The railway was built to provide a faster link between Djibouti’s ports and Ethiopia’s inland markets, but port access and loading infrastructure have limited its role in moving fuel. In February 2026, the Ethio-Djibouti Joint Railway Commission agreed to accelerate links to Doraleh and the Horizon terminal.

Trains will not replace trucks. Ethiopia’s markets are spread across a large territory, and many destinations are beyond the railway network. ATLS is therefore also installing several truck-loading stations so tankers can be loaded in parallel. Rail can serve high-volume destinations while trucks continue to reach places the railway cannot.

The two modes could give operators more flexibility when one route is disrupted or demand changes. But the terminal’s performance will depend on how well it coordinates vessel arrivals, storage, loading bays, train wagons, tanker trucks and border procedures. Storage capacity only becomes useful when fuel can move through each of those steps without avoidable delays.

For Djibouti, ATLS could bring more port activity and demand for logistics services. For Ethiopia, it could add storage and a rail option to a fuel-import route that is now dominated by road transport. Together, those links could strengthen the corridor’s ability to handle large volumes and respond to supply pressure.
The project will not by itself resolve every challenge in the fuel chain. Procurement, foreign-exchange

availability, road conditions, railway performance and coordination between agencies will continue to influence the cost and reliability of deliveries.

Construction has moved the project from plans to physical work. If the first phase is commissioned as scheduled in June 2027, ATLS will be tested on whether it can turn new storage and rail-loading capacity into dependable fuel movement. The first trains will matter for more than the terminal: they will show whether Djibouti’s port and Ethiopia’s inland supply chain can work as one system.