Wednesday, September 23, 2026
Home Blog Page 47

Ethiopia dominates Kenya’s informal export market, claims over 50% share

0

Ethiopia has solidified its position as the premier destination for Kenya’s informal cross-border trade, absorbing more than half of all unrecorded outbound goods across surveyed frontiers, according to newly released official statistics.

The 2025 Informal Cross Border Trade (ICBT) Survey Report, published by the Kenya National Bureau of Statistics (KNBS), reveals that Ethiopia captured a commanding 54% share of Kenya’s total unrecorded exports during the June 2025 observation cycle.

The joint study—conducted by the KNBS alongside the Central Bank of Kenya (CBK), the Kenya Revenue Authority (KRA), and the Ministry of Trade—monitored unrecorded goods flows at key border points during two 14-day sample periods in December 2024 and June 2025.

The findings emphasize that small-scale, unrecorded cross-border trade continues to serve as a vital support for food security, community livelihoods, and regional trade integration in the Horn of Africa.

Ethiopia was the main destination for Kenya’s informal exports across both survey cycles. During the 14-day monitoring period in December 2024, Kenya recorded a total informal export value of 159.7 million Kenyan Shillings (KES) across all its land borders. Of this total, exports to Ethiopia accounted for KES 74.5 million, or roughly 46.7%.

By June 2025, Ethiopia’s dominance as a trade destination expanded further. Out of the KES 124.0 million in total informal exports recorded during the 14-day period in June, shipments to Ethiopia reached KES 67.0 million—representing 54.0% of Kenya’s total informal exports.

Combined with Uganda (which received KES 36.2 million or 29.1% in June 2025), the two neighboring countries accounted for over 83% of Kenya’s unrecorded export trade.

Conversely, Kenya imported informal goods from Ethiopia valued at KES 50.4 million in December 2024 and KES 39.1 million in June 2025. During both periods, Kenya maintained a significant trade surplus in its informal trade with Ethiopia—rising from KES 24.2 million in December 2024 to KES 27.8 million in June 2025.

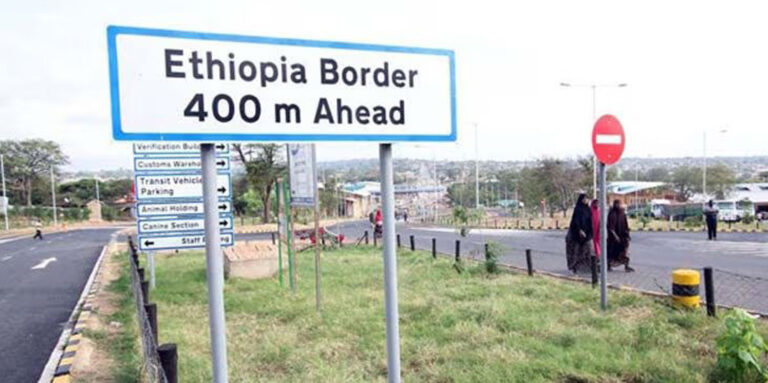
The Moyale border post emerged as the primary gateway facilitating informal trade between Kenya and Ethiopia, consistently outperforming all other surveyed border points in export value.

In December 2024, Moyale registered KES 63.8 million in informal exports and KES 8.2 million in imports, yielding a trade surplus of KES 55.6 million.

In June 2025, Moyale recorded KES 51.9 million in exports and KES 19.1 million in imports, maintaining a trade surplus of KES 32.8 million.

According to the study released on August 21, 2026, key routes serving the Ethiopia-Kenya border also include Mandera (Ethiopia side) and Ramu. In December 2024, Mandera handled KES 10.8 million in exports and KES 8.8 million in imports, followed by KES 11.2 million in exports and KES 11.1 million in imports in June 2025.

On the other hand, Ramu shifted from being heavily import-dependent in December 2024 (KES 33.4 million in imports against KES 2.4 million in exports) to recording KES 4.1 million in exports and KES 8.9 million in imports in June 2025.

The three state agencies explained that in December 2024, exports passing through Moyale and Mandera mainly consisted of inedible crude materials (excluding fuel), representing 42.1% (KES 67.2 million) of Kenya’s total informal exports. Food and live animals accounted for 28.3% (KES 45.3 million). During this cycle, unprocessed agricultural materials and food items constituted 63.7% and 17.1%, respectively, of direct exports to Ethiopia.

By June 2025, food and live animals became the leading export category across all borders, accounting for 37.9% (KES 47.0 million) of total informal exports, followed by crude materials at 24.0% (KES 29.8 million), officials reported.

Recognizing the scale and economic importance of this informal trade, both governments have taken steps toward formalization.

 In December 2025, Kenya and Ethiopia signed a bilateral agreement in Moyale to establish a Simplified Trade Regime (STR) aimed at facilitating trade by streamlining procedures and reducing administrative hurdles.

Under the new framework, eligible traders must reside within a 50-kilometer radius of the authorized border crossing on the Ethiopian side and within a 100-kilometer radius on the Kenyan side. Licensed traders are permitted to trade goods valued up to $1,000 per month under simplified customs procedures, with border crossings restricted to once a week.

The system covers locally produced goods, including livestock, agricultural produce, food items, and other approved commodities. While it does not exempt participants from customs duties, qualifying goods receive a 10% bilateral tariff discount under COMESA Rules of Origin.

However, trade policy experts have raised concerns that the system’s limitations—including travel frequency caps, geographical restrictions, and administrative requirements—might inadvertently discourage traders from choosing formal channels.

An article published on the World Bank website suggests that allowing more frequent crossings, raising value thresholds, and expanding the operational radius would make formal trade more competitive and better reflect the daily reality of local traders.

This critical study highlights that total regional informal trade across Kenya’s borders declined by 16.7%—dropping from KES 299.0 million in December 2024 to KES 249.1 million in June 2025. This overall decline shifted Kenya’s overall informal trade balance from a surplus of KES 20.4 million in December 2024 to a slight deficit of KES 1.1 million in June 2025, driven primarily by an increase in informal imports from Tanzania.

Statistical authorities noted that recording these unrecorded flows is essential for improving national accounts, the balance of payments (BOP), and international merchandise trade statistics (IMTS).
Breaking the debt and currency cycle

0

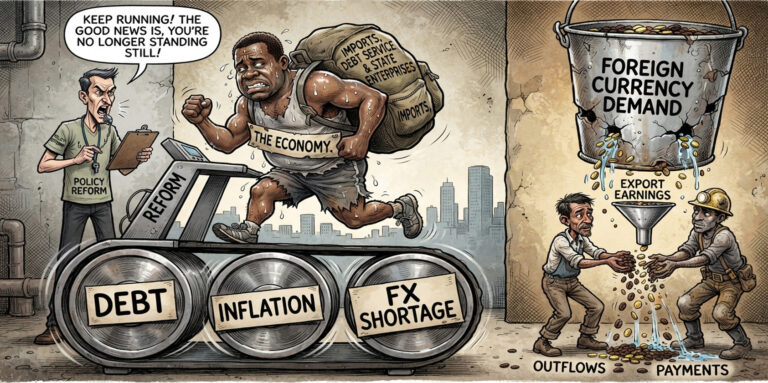
Ray Dalio’s ‘How Countries Go Broke: The Big Cycle’ is not a book about one country, one government or one moment of bad policy. It is a warning about a recurring economic pattern: countries become vulnerable when debt rises faster than their ability to earn, produce, tax and repay. Eventually, the bill arrives through inflation, currency weakness, financial instability or painful austerity.

Ethiopia should read that warning carefully—not because it is destined to “go broke,” but because it is now attempting a difficult recovery from many of the conditions Dalio identifies: foreign-exchange scarcity, heavy public obligations, weak domestic revenue, import dependence, inflation and the temptation to solve structural problems with short-term financial measures.

Dalio’s central argument is straightforward. A country enters danger when debt-service costs consume an ever-larger share of government revenue, while buyers become less willing to finance new borrowing. At that point, policymakers face unpleasant choices: raise taxes, cut spending, borrow at higher interest rates, default or rely on the central bank to create money. The latter can ease pressure temporarily, but risks devaluing the currency and fuelling inflation.

For Ethiopia, the language is different, but the logic is familiar.

For years, Ethiopia’s growth model relied heavily on public investment, large infrastructure projects, state-led financing and external borrowing. Roads, railways, industrial parks, dams and public enterprises were meant to create the foundation for industrialisation. Some of these investments were necessary. No country can develop without infrastructure.

But infrastructure does not repay debt by itself. It must be followed by exports, productive firms, jobs, tax revenue and foreign-exchange earnings. When those returns arrive slowly, debt accumulates faster than repayment capacity.

That is where Ethiopia’s challenge lies. The country has not merely faced a public-debt problem. It has faced a foreign-currency problem. Ethiopia earns hard currency through exports, remittances, tourism and foreign investment, but it needs even more hard currency for fuel, machinery, medicines, industrial inputs, debt service and essential imports.

For too long, the difference was managed through foreign-exchange controls, rationing and an overvalued currency. This did not eliminate the shortage. It only distributed it through queues, privilege, informal markets and administrative discretion.

The July 2024 shift toward a market-determined exchange rate was therefore a necessary correction. It recognised an uncomfortable truth: a currency cannot remain artificially strong when the country lacks enough foreign exchange to support it. Since then, Ethiopia has recorded stronger export performance and improved reserve buffers, while the parallel-market premium has narrowed from earlier extremes. The IMF has stressed that maintaining adequate reserves and exchange-rate flexibility is essential for cushioning external shocks.

But correction is not the same as cure.

The depreciation of the birr has made imports more expensive. That means higher costs for fuel, fertiliser, medicines, transport, machinery and consumer goods. Inflation reached 13.9 percent in June 2026, driven largely by food and non-food price pressures.  For ordinary citizens paid in birr, macroeconomic reform can feel less like stabilisation and more like a reduction in daily purchasing power.

This is the political danger of reform. A government can be technically correct and socially unsuccessful at the same time if the burden of adjustment falls too heavily on households, wage earners and small businesses.

Dalio’s book reminds us that debt crises are never only about accounting. They are about the distribution of pain. When prices rise faster than incomes, when jobs do not grow, when access to foreign currency depends on connections and when public services remain weak, economic hardship becomes a crisis of trust.

Ethiopia must therefore avoid treating exchange-rate liberalisation as the end of reform. It is only the beginning.

The first priority must be to expand the country’s ability to earn foreign exchange. Gold and coffee have helped lift export revenues, but an economy cannot depend indefinitely on a narrow range of commodities. Ethiopia needs processed agricultural exports, tourism, digital services, mining value addition, manufactured goods, logistics and electricity exports. It must export more than raw potential; it must export reliability, quality and value.

The second priority is fiscal discipline. Dalio’s warning about debt service is relevant here. Governments cannot borrow indefinitely to cover current spending, bail out inefficient institutions or finance projects without clear returns. Ethiopia needs better public investment selection, stronger oversight of state-owned enterprises, transparent borrowing and realistic assessment of contingent liabilities.

That does not mean abandoning development spending. It means distinguishing between investment that expands productive capacity and expenditure that merely postpones difficult decisions.

Third, Ethiopia must deepen domestic savings and capital markets. A country that depends entirely on external finance becomes vulnerable whenever global conditions worsen. Stronger pension funds, insurance companies, bond markets, investment banks and transparent capital-market institutions can help mobilise local resources for long-term development.

But domestic finance must not become another form of hidden taxation. If banks are forced to absorb government obligations at uncompetitive returns, or if inflation erodes depositors’ savings, confidence in the financial system will weaken.

Fourth, reforms must strengthen the private sector rather than merely announce its importance. Investors still face foreign-exchange constraints, regulatory uncertainty, weak property-rights protection, inconsistent taxation and administrative delays. The IMF has noted that while Ethiopia’s reform direction has been welcomed, implementation remains uneven.

The country does not need more declarations about private-sector leadership. It needs predictable rules, fair competition, functioning logistics, access to finance and an environment in which productive businesses can survive.

Finally, Ethiopia must recognise that social stability is an economic asset. No macroeconomic programme can succeed if conflict, displacement and insecurity continue to destroy farms, markets, roads, schools and investor confidence. The cost of war is not only measured in military spending. It is measured in foregone exports, lost livelihoods, interrupted education and generations of weakened human capital.

Dalio’s “big cycle” is a cautionary framework, not a prophecy. Countries do not collapse simply because they have debt, inflation or currency pressure. They collapse when leaders deny reality, delay adjustment and allow short-term politics to overwhelm long-term economic discipline.

Ethiopia has begun to confront reality. The task now is to ensure that reform produces a more productive economy—not merely a more expensive one. The true test is whether the country can turn stabilisation into jobs, exports, domestic investment and improved living standards.

That is how a nation escapes the cycle: not by borrowing more time, but by building more capacity.

Ethiopia targets China trade gap with export drive 

0

Ethiopia is stepping up efforts to narrow its widening trade deficit with China by using new duty-free market access, domestic economic reforms and export-promotion initiatives to expand sales to the world’s second-largest economy.

China remains Ethiopia’s largest trading partner and leading source of foreign direct investment, with more than 4,500 Chinese companies operating in manufacturing, infrastructure and services. However, bilateral trade remains heavily tilted in China’s favour.

During the 2025/26 fiscal year, Ethiopia imported nearly USD 21 billion worth of goods from China, largely machinery, construction materials, manufactured products and industrial inputs. Ethiopian exports to China, by contrast, reached USD 369 million, leaving a substantial trade imbalance.

The figures were highlighted at the forum held in Addis Ababa on Aug. 19, where Ethiopian and Chinese companies signed 33 cooperation agreements valued at more than USD 330 million. The agreements cover coffee, oilseeds, pulses, leather, mineral products and textiles.

Kassahun Gofe, Minister of Trade and Regional Integration, said Ethiopia was seeking to use the Chinese market to accelerate domestic production, diversify exports and improve foreign-exchange earnings.

He said exports to China had grown at an average annual rate of 92 percent over the past five years, supported by demand for Ethiopian coffee, oilseeds, pulses, leather products and other agricultural goods.

However, the growth in exports remains small compared with the value of imports from China. Chinese involvement in Ethiopian infrastructure, including roads, industrial parks, energy projects and construction, has increased demand for imported machinery, equipment and materials.

The imbalance has placed additional pressure on Ethiopia’s foreign-exchange reserves and strengthened calls for greater domestic processing, import substitution and export-oriented manufacturing.

Kassahun said the government’s Homegrown Economic Reform Agenda was intended to address such structural challenges by liberalising the foreign-exchange market, improving trade logistics, reducing administrative bottlenecks and providing incentives for private-sector investment.

China has also expanded market access for African exporters. On May 1, Beijing began implementing zero-tariff treatment for imports from all 53 African countries with which it maintains diplomatic ties, including Ethiopia. The policy expanded an earlier preferential arrangement that had applied mainly to least-developed countries.

Chinese Ambassador to Ethiopia Chen Hai said the policy could reduce market-entry costs for Ethiopian small and medium-sized enterprises and encourage investment in sectors where Ethiopia has a comparative advantage.

The arrangement is expected to support exports of Ethiopian coffee, sesame, pulses, horticultural products, leather goods and other agricultural and manufactured items that meet Chinese quality, safety and quarantine requirements.

China has also granted market access to coffee beans meeting quarantine requirements from African countries with diplomatic relations with Beijing, creating an additional opening for Ethiopian exporters.

Chang Hui, Deputy Director-General of the Department of Foreign Trade at China’s Ministry of Commerce, said China was committed to expanding imports and strengthening commercial ties with Ethiopia.

“The zero-tariff policy reduces trading costs and enables a wider array of specialty Ethiopian products to reach Chinese consumers,” Chang said at the forum.

He said the policy could benefit farmers, processors and exporters by helping convert Ethiopia’s natural-resource base into higher export earnings.

Zekarias Assefa, Secretary-General of the Addis Ababa Chamber of Commerce and Sectoral Associations, said the forum offered Ethiopian firms a route to establish commercial relationships in a market of more than 1.4 billion consumers.

“Platforms like ‘Big Market for All’ are vital for our business community,” Zekarias said. “They enable investors to secure reliable partners, attract foreign investment and establish long-term commercial networks.”

The 33 agreements signed at the forum demonstrate commercial interest, but their impact will depend on whether Ethiopian suppliers can meet buyers’ standards on volume, quality, reliability, processing, certification and delivery.

Closing a multi-billion-dollar trade deficit will require more than duty-free access. Ethiopia will need to increase agricultural productivity, expand processing capacity, improve logistics, address foreign-currency shortages, secure trade finance and build stronger links between producers, exporters and Chinese buyers.

For policymakers, the immediate opportunity is to turn growing demand for Ethiopian coffee, oilseeds, horticulture, leather, textiles and mineral products into sustained export growth. The longer-term goal is to shift the trade relationship away from dependence on imported machinery and manufactured goods toward a more balanced exchange built on higher-value Ethiopian exports.

Does the law of attraction really attract wealth?

0

The promise is irresistible. Think positively, visualise financial success, believe that prosperity is on its way and somehow the universe will deliver. The “Law of Attraction” has become a powerful idea in modern self-help culture, popularised by books such as Rhonda Byrne’s The Secret. Its central proposition is simple: thoughts shape reality, and positive thoughts attract positive outcomes.

But economics asks a more uncomfortable question: does thinking about wealth actually create wealth? The short answer is no, not in the literal sense. There is little credible economic or scientific evidence that thoughts, wishes or visualisation possess an independent force capable of attracting money. Wealth is produced through a combination of human capital, productivity, entrepreneurship, investment, institutions, opportunity and, importantly, circumstances that individuals do not fully control. That does not make mindset irrelevant. Quite the opposite. Expectations can influence behaviour, and behaviour can influence economic outcomes. The mistake is to confuse this psychological channel with a supernatural one.

The Law of Attraction rests on the idea that “like attracts like”. If an individual continually imagines being wealthy, the theory suggests, that individual increases the probability of becoming wealthy. There is an appealing logic to this argument. Someone who believes that financial improvement is possible may be more willing to acquire skills, pursue opportunities, negotiate a salary, establish a business or invest.

Economics has a framework for understanding this without invoking the universe. Human behaviour is influenced by expectations, incentives and beliefs. Albert Bandura’s work on self-efficacy, for example, shows that people who believe in their ability to accomplish a task tend to demonstrate greater motivation and persistence. Confidence can therefore have economic value.

Consider two people with similar qualifications. One believes that changing careers is possible and actively searches for opportunities. The other assumes that nothing can change and never applies. Their different beliefs may eventually contribute to different economic outcomes. But the causal mechanism is behaviour not attraction. The first person does not become wealthier because the universe responded to positive thoughts. They become wealthier, if they do, because confidence encouraged action, action created opportunities and opportunities produced results.

That distinction matters. Wealth is not simply a state of mind. The more serious problem with the Law of Attraction appears when it is applied to inequality. If wealth is supposedly attracted through positive thinking, it follows at least implicitly that poverty may be the result of negative thinking. This is an appealing story because it makes economic success entirely personal. But it is also deeply misleading.

People do not begin their economic lives from the same starting point. Family wealth, quality of education, geography, access to finance, social networks, health, labour-market conditions and inherited assets all influence economic opportunity. Two people may possess equally ambitious mindsets while having dramatically different resources available to them.

Economists have long recognised the importance of these differences. Intergenerational wealth, for example, can provide access to better education, housing, investment opportunities and business capital. A young person whose parents can finance university and provide a financial safety net does not face the same constraints as someone who must immediately work to support a household.

Mindset matters but starting conditions matter too. Ignoring this reality risks turning a structural economic problem into a personal moral judgment. Telling someone facing unemployment or poverty simply to “think positively” may sound encouraging, but it does not create jobs, raise wages or remove barriers to capital.

There is another problem with manifestation culture: positive fantasies can sometimes substitute for action. Psychologist Gabrielle Oettingen in her 2014 published book entitled “Rethinking Positive Thinking: Inside the New Science of Motivation” has distinguished between imagining a desirable future and confronting the obstacles that stand between people and that future. Her work suggests that positive fantasies alone do not necessarily produce better outcomes. A more effective approach involves recognising the desired goal while also identifying the obstacles and developing strategies to overcome them.

This is particularly relevant to personal finance. Someone can spend an hour every morning visualising a million-dollar bank balance. But unless that exercise is accompanied by increased income, controlled expenditure, investment, entrepreneurship or skill development, the bank balance is unlikely to change. The economically productive question is not, “How do I attract a million dollars?” It is, “What combination of skills, income, savings, investment and entrepreneurial activity could realistically increase my net worth?” That is a less glamorous question but a much more useful one.

The Law of Attraction becomes particularly problematic when applied to financial markets. Markets are uncertain. Investments can rise or fall for reasons that have nothing to do with an investor’s optimism. Interest rates, inflation, corporate earnings, geopolitical developments, technological change and investor expectations all affect asset prices.

Believing that an investment will succeed does not make it succeed. In fact, excessive confidence can make investors more vulnerable to financial losses. Behavioural economics has documented the role of cognitive biases such as overconfidence, whereby individuals overestimate their knowledge, abilities or capacity to predict uncertain outcomes. This is precisely where manifestation can become dangerous. If investors interpret failure as evidence that they did not “believe strongly enough”, they may continue taking risks instead of reassessing their assumptions. Sound financial management requires the opposite mindset: recognise uncertainty, diversify risk, evaluate evidence and accept that some outcomes cannot be controlled.

Yet it would be too easy to dismiss the entire concept. There is one valuable idea buried within the Law of Attraction: people’s beliefs can influence their economic behaviour. A person who believes financial independence is impossible may never learn about investing. Someone who believes they can improve their circumstances may seek education, negotiate better employment conditions or establish a business.

The difference is not mystical. It is behavioural. This suggests that visualisation can be useful when treated as a motivational tool rather than a financial mechanism. Imagining a desired future may help clarify goals. But the next step must be measurable action. Instead of merely visualising financial independence, set a savings target. Instead of imagining a successful business, research the market. Instead of wishing for higher income, develop a skill that employers value. Instead of believing an investment must rise, assess its risk and expected return. In other words, convert aspiration into economic behaviour.

There is no universal formula for becoming wealthy. However, the underlying principles are considerably less mysterious than the Law of Attraction suggests. Wealth accumulation generally requires some combination of earning more than one spends, investing capital productively, acquiring valuable skills, managing risk and allowing time and compounding to work. But even these factors do not guarantee success. Economic conditions matter. A recession can destroy employment opportunities. Inflation can reduce purchasing power. A business can fail despite competent management. An investment can lose value despite careful analysis. This is why an honest discussion of wealth must contain both agency and uncertainty. Individuals have choices, but they do not control the entire economic environment.

Perhaps the Law of Attraction survives because it offers something economics often struggles to provide: hope. It tells people that their future can be different from their present. That message should not be dismissed. But hope becomes useful only when it is connected to reality. Positive thinking can strengthen confidence. Confidence can encourage action. Action can create opportunities. Opportunities, combined with skills, capital and favourable circumstances, can produce wealth.

That is a credible chain of causation. The claim that thoughts themselves send a signal to the universe that returns money, however, is another matter. There is insufficient evidence to support it. The better financial philosophy is therefore straightforward: do not merely visualise wealth, understand how wealth is created. Think positively, certainly. Set ambitious goals. Imagine a better future. But then examine the numbers, understand the risks, acquire useful skills, save consistently, invest prudently and take advantage of genuine opportunities. The universe may not owe anyone a fortune. The economy, however, rewards productivity, innovation, capital formation and persistence far more reliably than it rewards wishful thinking.