

Monetary Reform
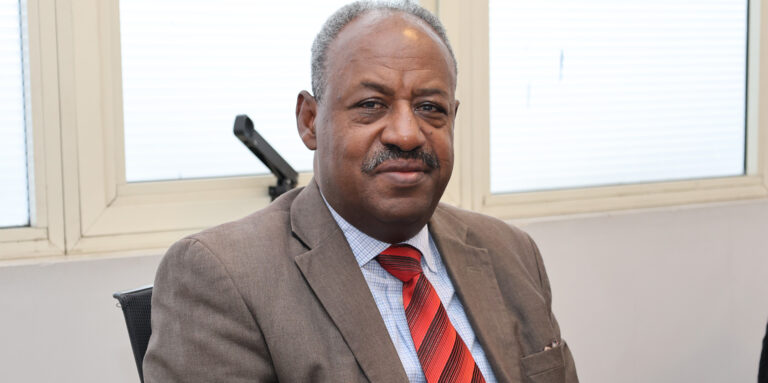
Worku Lemma is a towering figure in Ethiopia’s financial and economic landscape, with more than two decades of leadership experience. Having risen through the banking sector from bank clerk to founding president of two commercial banks, his strategic acumen has helped shape the nation’s financial institutions. He currently serves as a board member of Hibret Bank S.C. and is also involved in national logistics-modernisation efforts within Ethiopia’s logistics sector.
In this interview with Capital, Worku shares his perspective on Ethiopia’s evolving macroeconomic policy framework, the National Bank of Ethiopia’s latest monetary tools and the realities of credit demand. He assesses the likely impact of higher policy rates, raises practical concerns about performance-based secondary reserve requirements, and discusses foreign-exchange dynamics, inflation control and the balance between market liberalisation and national survival priorities. Excerpts;
Capital: How do you view the current macroeconomic policy framework and the newly introduced tools by the National Bank?
Worku Lemma: Overall, I view the matter positively. Regardless of the country or policy framework, when these measures are assessed against Ethiopia’s current economic strengths and weaknesses, they represent a step that can improve stability and support macroeconomic development going forward.
In my view, lifting lending caps is consistent with the International Monetary Fund’s recommendations. Looking closely at those guidelines, they do not advocate lifting all restrictions at once. Rather, the idea is that restrictions should be phased out gradually as economic conditions evolve. Maintaining rigid caps can be harmful in many ways. If the economy is starved of money, credit is not easily accessible and, conversely, sectors crucial for national survival and industrial development—such as manufacturing—do not receive adequate and appropriate financing, economic growth can be severely undermined.
Capital: Given that the Monetary Policy Committee raised the policy rate to curb credit competition, how effective will this tool be, given the realities of the banking sector?
Worku: Raising the policy rate helps to a certain extent, but I do not believe it will solve the challenge entirely. One of the main limitations is that the policy rate is not directly linked to the commercial lending rates set by banks. We rarely see banks automatically adjusting their lending rates in response to changes in the policy rate.
In practice, even when the nominal lending rate hovered around 15 percent, the actual effective interest rate was much higher—often surpassing 20 percent and reaching 22 or 23 percent for many borrowers. Beyond that level, the situation remains ambiguous. While the interbank lending margin—ranging from minus 3 percent to plus 3 percent—may have some impact, I doubt it can control the broader money supply to the extent intended.
To be honest, our country’s economy and business community are credit-addicted. Whether the official rate rises or falls, the elasticity of credit demand is questionable. We have a business community that sometimes borrows at rates that border on usury.
If you look at the digital-lending and microfinance sector—small loans of 50,000, 75,000, 100,000 and up to 300,000 birr provided by banks and fintechs—the interest rates are shocking. Although structured over short terms of one to three months, the annualised rate often exceeds 30 to 40 percent. I genuinely worry about whether an entrepreneur can borrow at such a rate, build a viable enterprise and repay the loan. Furthermore, I have deep concerns about whether this high-interest credit sector helps control inflation at all.
Capital: What are your concerns regarding the practical implementation of the performance-based secondary reserve requirement linked to credit expansion?
Worku: My primary concern lies there. Instead of a traditional reserve requirement applied uniformly across all banks, this framework is formulated in a way that reserves could increase based on the lending behaviour of individual institutions. But under what exact conditions is that triggered? How is it monitored? Can it truly be practical?
Right now, a bank’s standard reserve requirement is around 10 percent. If a bank is suddenly told to deposit 13 or 15 percent based on its loan-to-deposit ratio, it creates extreme uncertainty because institutions cannot predict when or how severely they will be affected. Because excess reserves yield no profit, banks naturally focus on managing their cost of funds. If regulations become ambiguous or punitive based on loan-to-deposit ratios, banks may tend to retreat from lending altogether, preferring instead to park their capital safely in government securities such as Treasury bills.
The figures show that the National Bank’s Monetary Policy Committee noted that the current loan-to-deposit ratio is around 72 to 73 percent, while overall liquidity is about 30 percent—well above the 15 percent regulatory minimum. Compared with three years ago, when the loan-to-deposit ratio was stretched to 90 to 92 percent, banks are currently highly liquid.
However, if a bank has already deployed its liquidity into long-term loans and has exhausted its options, then is suddenly hit with a higher reserve requirement, where is it supposed to pull that cash from? Which market will it use to fill the gap? You cannot retroactively enforce compliance on money that has already been lent out. Doing this without prior warning and preparation could push otherwise stable banks into severe liquidity crises. A clear operational guideline must be in place before any punitive measures are taken.
Capital: Some analysts argue that tightening reserve requirements is a tactical strategy used by the government to pull bank liquidity into Treasury bills to cover its domestic borrowing needs and budget deficit. What is your view?
Worku: The notion that the government is doing this primarily to cover its budget deficit is secondary, in my view. Procedurally, we know that the government is restricted from taking direct bank loans to cover fiscal deficits. While it may finance part of its deficit through competitive bidding in the Treasury-bill market, the overriding priority must remain inflation control.
Inflation is a heavy and destructive force. Today, most ordinary citizens face severe daily challenges; many cannot even afford basic meals. Under conditions in which life has become a daily survival test for many people, strict monetary policy is imperative. Monetary policy alone cannot fight inflation, however. It must be paired with strict fiscal discipline and robust supply-side measures. Economic best practice requires a combination of policy instruments. Above all, while we view the overall monetary direction positively, the operational rules must be clear to avoid destabilising the banking sector.
Capital: How does the current framework compare with the aggressive controls—including unwritten credit caps and mandatory bonds—used by the National Bank since the early 2000s?
Worku: Today’s policy approaches are much closer to modernisation and international best practice than the heavy-handed interventions of the past. Looking back, we had mandatory National Bank bill purchases and Development Bank of Ethiopia 1 percent bond purchases, as well as strict caps on term loans, revolving credit, overdrafts and pre-shipment facilities. Those historical methods were blunt and restrictive instruments, with little market incentive or competitive dynamics. Implementing them was a nightmare for bank management, and the sector faced immense pressure.
Today’s regulatory philosophy is vastly superior. The current Monetary Policy Committee includes independent professionals and autonomous bodies that bring high-level technical rigour to the table. Despite modern complexities—particularly in adjusting targeted reserve requirements—the current approach is more constructive and market-aligned than the opaque, administratively imposed caps we faced years ago.
Capital: How do you evaluate current foreign-exchange dynamics and the 70–30 surrender-and-retention scheme amid continuing parallel-market activity?
Worku: First, we must accept a fundamental reality: there is a foreign-exchange shortage. I strongly reject the narrow argument that “the exporter’s dollar belongs entirely to the exporter.” Hard currency is a critical national resource. A developing country depends on sustainable foreign-exchange inflows to drive macroeconomic growth. Fortunately, we are currently observing positive trends in national foreign-exchange reserves.
Until the external sector fully normalises, proceeding gradually is prudent. While some advocate complete and immediate liberalisation—allowing exporters to retain and sell 100 percent of their earnings freely, a privilege previously granted selectively to the service sector—we must weigh this against our primary national priorities.
Our country still desperately needs fuel to keep the economy moving. Citizens still require life-saving medicines. Allowing exporters to speculate freely while ordinary people suffer from medicine and fuel shortages is neither economically nor socially responsible.
The current policy direction—requiring exporters to surrender 30 percent while allowing banks and exporters to retain 70 percent—is balanced and rational. However, execution determines everything. The system must be strictly monitored. I have heard criticism that mismanaged foreign-exchange allocations contribute significantly to the ongoing trade deficit, and that criticism is valid. Closing the trade gap will not happen overnight; even under favourable conditions, achieving a sustainable balance could easily take a decade.
Government mandates full statutory fuel-tax collection
The Government of Ethiopia has mandated the collection of all federal fuel taxes at full statutory rates, a measure projected to generate revenue equivalent to 0.8 percent of gross domestic product (GDP) in the 2026/27 fiscal year.
Under the directive, the Ministry of Finance has authorised the Ethiopian Customs Commission to remit all fuel-tax proceeds directly to the federal treasury, marking a significant departure from previous practice. In the past, part of the revenue was retained by entities such as the Ethiopian Petroleum Supply Enterprise (EPSE) and the Road Fund to offset operational losses and finance subsidies.
The fuel-tax reform is a central component of Ethiopia’s broader IMF-supported structural reform programme. It is intended to phase out untargeted subsidies, strengthen public finances, support the restructuring of key state-owned enterprises and help curb inflation.
During the 2025/26 fiscal year, the government formally incorporated fuel subsidies into the federal budget. Under the new framework, revenue derived from excise tax, value-added tax (VAT) and other fuel-related charges is to be channelled directly into the central treasury. Authorities aim to eliminate off-budget accounts, secure more predictable revenue and strengthen macro-fiscal stability.
According to recent International Monetary Fund documents, the initiative forms part of a broader strategy to improve Ethiopia’s tax-to-GDP ratio, which has historically remained among the lowest in the region. The planned reforms include expanding the excise-tax base, introducing specific excise regimes with higher rates on alcohol and tobacco, removing selected VAT exemptions and introducing motor-vehicle transfer taxes.
The IMF programme states that all federal fuel taxes—estimated at 0.8 percent of GDP in 2026/27—will be collected in full at statutory rates by Customs and remitted to the federal budget. It specifies that VAT and excise liabilities must be assessed using the applicable statutory tax base, without caps or ad hoc adjustments that reduce effective tax collection.
The tighter enforcement is seen as vital to the government’s plan to eliminate costly fuel subsidies. For the 2025/26 fiscal year, the budget set fuel and fertiliser subsidy ceilings of 100 billion birr, or 0.6 percent of GDP, and 84 billion birr, or 0.4 percent of GDP, respectively. However, reported fuel-subsidy spending exceeded the original cap during the year.
As the country enters the 2026/27 fiscal year, the fuel-subsidy envelope is expected to decline substantially. To institutionalise the transition, the government is deploying an automatic fuel-price adjustment mechanism developed with IMF technical assistance.
In the 2025/26 fiscal year, the Ministry of Revenue collected 1.5 trillion birr, an increase of about 618.39 billion birr from the same period in the previous year. The performance was largely driven by income-tax reforms. The revenue impact of tax policy measures already implemented is projected to raise the general government tax-to-GDP ratio to 10.1 percent in 2026/27, moving towards a medium-term target of 10.5 percent by 2027/28.
To resolve legacy fuel-subsidy debt—arising mainly from exchange-rate volatility and the historical use of deferred letters of credit for fuel procurement—the government is undertaking a major financial restructuring of EPSE.
As a prior action under the IMF programme, the Ministry of Finance decided to allocate 286 billion birr to recapitalise the state-owned enterprise. The decision was approved by the Ethiopia Investment Holdings board.
According to IMF assessments, approximately 170 billion birr, equivalent to USD 1.05 billion or 0.9 percent of GDP, from anticipated World Bank Development Policy Operation and Rapid Response Option financing is expected to be transferred to the federal budget to strengthen EPSE’s capital position. The remaining 116 billion birr, sourced from central treasury resources, is expected to be transferred before the end of March 2027.
As part of broader fiscal reforms introduced in June 2026, the Ministry of Finance directed the Ethiopian Customs Commission to collect fuel taxes—including 15 percent VAT and 15 percent excise tax—at their full statutory rates and transfer all proceeds to the federal treasury. Excise and VAT liabilities will be assessed on statutory tax bases, a move intended to improve fiscal transparency and make revenue collection more predictable.
Industry analysts say the social and economic effects of heavier tax burdens will require close monitoring, particularly as successive policy changes risk placing additional pressure on households, businesses and productive sectors. They also note that continued volatility in global fuel markets, compounded by geopolitical tensions in the Middle East, remains an important macroeconomic risk.
Inflationary pressures have also re-emerged. After falling to 9.4 percent in March 2026, 12-month headline inflation rose to 11.7 percent in April and 13.4 percent in May, largely driven by food prices and higher global commodity costs.
The Consumer Price Index reached 13.9 percent in June 2026. Food inflation stood at 15.1 percent, while transport costs rose by 14.3 percent year on year.
War in the North: A point of no return
The prospect of another war in northern Ethiopia should alarm every Ethiopian, every neighbour and every international partner that claims to care about stability in the Horn of Africa. The country has not recovered from the devastation of the 2020–2022 conflict. To return to large-scale fighting now would not be a continuation of an old crisis; it would be the creation of a deeper and potentially irreversible one.
Recent clashes in western Tigray have already displaced civilians and revived fears that the Pretoria Agreement could collapse completely. The agreement ended full-scale war, but it did not resolve the territorial, political, humanitarian and security questions that produced the conflict in the first place. A region left in this unresolved condition is not truly at peace. It is merely waiting for the next trigger.
The danger is not confined to Tigray. A renewed war would pull in disputes over western Tigray, tensions with Eritrea, the conflict in Amhara and the broader instability of the Ethiopia-Sudan border. The alliances and rivalries now forming are far more complicated than those of 2020. Former allies are enemies; former enemies may find temporary common cause. This is the kind of political landscape in which miscalculation, not deliberate strategy, can ignite a wider catastrophe.
The first victims would again be civilians. Families who have already lost homes, livelihoods, relatives and years of education would face another cycle of displacement. More than three years after the Pretoria Agreement, around 750,000 people in Tigray remain displaced, many unable to return to their homes in contested areas. A new war would not begin on an empty field. It would strike communities already weakened by hunger, trauma, interrupted health care and economic collapse.
The second casualty would be Ethiopia’s national economy. War does not only destroy roads, farms and factories. It destroys confidence. It discourages investment, interrupts trade, drains public resources and diverts attention from inflation, unemployment, debt, education and health care.
Ethiopia cannot pursue macroeconomic recovery while repeatedly financing armed conflict. It cannot attract long-term investors while major regions remain insecure. It cannot speak seriously of industrialisation, export growth and job creation while young people see mobilisation, displacement and unemployment as their most immediate realities.
The country’s development ambitions require peace not as a slogan, but as an economic foundation. Every birr spent on ammunition is a birr not spent on irrigation, schools, clinics, roads or employment. Every farmer displaced from land weakens food production. Every young person pulled into violence represents a future worker, entrepreneur, teacher or professional lost to the nation.
The humanitarian consequences would also extend beyond Ethiopia’s borders. Sudan is already struggling with its own devastating war. Eritrea remains deeply entangled in the political and security calculations of northern Ethiopia. The Red Sea and the wider Horn are becoming increasingly contested geopolitical spaces. A new conflict in northern Ethiopia could therefore become a regional crisis, drawing in neighbouring countries, armed groups, external powers and competing security interests. This is why the language of military victory is dangerous. There may be tactical victories, captured towns and temporary shifts in control. But there can be no genuine victory when the social fabric of entire regions is torn apart. A government may defeat an armed group in one area, but cannot defeat the grievances, memories and distrust that remain after mass displacement and loss.
Likewise, armed movements may gain territory or popular support, but they cannot build a stable future through permanent war. No community will achieve security by making another community permanently insecure. No political claim can be sustainably resolved through civilian suffering.
The central lesson of recent Ethiopian history is that military solutions produce temporary control, not lasting settlement. The 2022 Pretoria Agreement proved that even after a devastating war, dialogue remains necessary. The tragedy is that dialogue came after immense loss. Ethiopia must not repeat the same mistake by treating negotiations as a final option after another cycle of destruction.
The immediate task is clear. All parties must prevent further escalation, protect civilians and restore meaningful channels of communication. The outstanding provisions of the Pretoria Agreement must be addressed seriously, particularly the return of displaced people, restoration of services, demobilisation, political inclusion and the resolution of contested territories through lawful and peaceful means.
This will require courage from leaders who may face pressure from constituencies that believe compromise is weakness. But real leadership is not measured by the ability to mobilise anger. It is measured by the ability to stop a country from walking into a disaster it can already see coming.
Ethiopians are tired of funerals, displacement camps, checkpoints, destroyed schools and promises that peace will come after one more battle. The north has suffered enough. The country has suffered enough.
War in the north would not simply derail Ethiopia’s recovery. It could entrench a generation of trauma, deepen regional fragmentation and create a chaos that no future government could easily reverse. The choice is not between victory and compromise. It is between a difficult peace now and a far more destructive war later.
