Thursday, September 24, 2026
Home Blog Page 95

Productive credit push

0

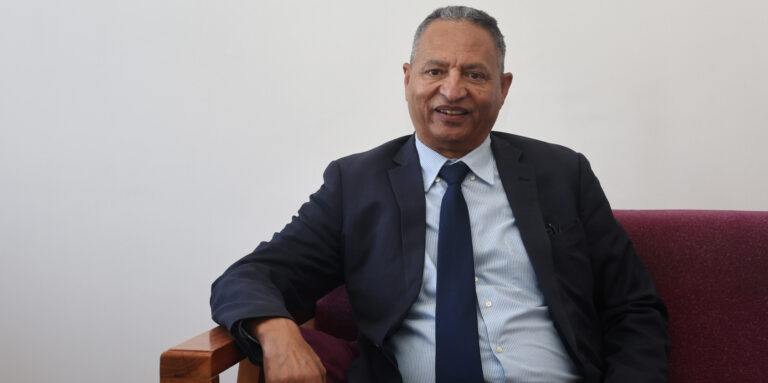
In this exclusive interview with Capital, economist and banking expert Eshetu Fantaye examines the National Bank of Ethiopia’s shift from bank credit caps to a reserve requirement-based framework, arguing that the real test will be whether lending is redirected toward productive sectors rather than government debt and speculative activity. Excerpts;

Capital: The National Bank has lifted the credit cap for banks. What impact will this decision have on the sector?

Eshetu Fantaye: That is a critical question. Access to transparent, granular financial data remains a challenge. If we see reports claiming a 24% disbursement rate, it is highly improbable that this is directed toward the private sector. It is more likely inflated by investments in Treasury bills and bonds. Currently, the monitoring of these figures is aggregate, which masks the reality. If government debt instruments are counted toward credit growth targets, then surpassing these caps is inevitable.

In practice, only a few major institutions—most notably the Commercial Bank of Ethiopia—possess the liquidity to simultaneously manage foreign currency requirements and heavy investments in government securities. While the decision to lift the cap is conceptually sound and offers necessary flexibility to capable banks, its success depends on implementation. If banks do not integrate a rigorous assessment of “supply impact” into their credit approval process, simply removing the cap will not achieve the desired economic outcome.

Capital: Are there parallels between the current climate of intervention and the restrictive, individually managed approach seen in 2009? What is your view regarding the new scheme for controlling credit growth and containing inflation?

Eshetu: The parallels exist in the mindset, but the mechanics are different. That earlier approach had a profound impact on banks’ decision-making processes. From a financial perspective, investing in Treasury bills and bonds is highly attractive for banks: it requires no provisioning (unlike private sector loans), and government exposure is treated as a sovereign asset, essentially risk-free.

This creates a systemic bias. Without explicit incentives or clear policy mandates, there is no guarantee that banks will shift their internal risk allocation away from “easy,” collateralized government debt toward the productive sector. Until the Ministry of Finance and the National Bank align their strategic thinking with long-term revenue generation rather than short-term borrowing, this institutional bias will persist.

Capital: You have often characterized the government’s relationship with credit as an “addiction.” Could you elaborate on why this focus on domestic borrowing is problematic compared to private sector lending?

Eshetu: Precisely. When the government focuses on domestic borrowing through bills and bonds, it is essentially just receiving a loan—it is a closed loop. However, consider the alternative: if that capital were directed toward exporters, manufacturers, or SMEs struggling with working capital, the economic multiplier effect is significant.

When a manufacturing company expands production, the government doesn’t just get a loan repayment; it generates a diverse, recurring tax revenue stream: VAT, withholding tax on transactions, payroll taxes from new hires, and pension contributions. This is what I call the “snowball effect.”

Currently, this year’s budget relies on 329 billion birr (14%) in domestic borrowing. If that sum were instead channeled into productive credit—working capital for import substitution or export expansion—the resulting tax revenue for the Ministry of Finance would be far more sustainable than the current reliance on debt. Unless the budget is visualized through this lens—where credit to the productive sector acts as a catalyst for future tax capacity—the reliance on domestic borrowing will remain difficult to break.

Capital: Given this, what is the role of the National Bank? Should we expect a return to a command-economy model where the regulator dictates lending quotas to individual banks, or are there more subtle levers available?

Eshetu: The National Bank neither should nor needs to direct individual banks on lending decisions. It possesses powerful monetary instruments, such as reserve requirements, which can be used as a lever. For instance, it could incentivize banks to lend to agriculture, manufacturing, and exports at favorable rates (e.g., 10–12%) by allowing them to utilize a portion of their required reserves.

This is not a subsidy; it is “operational orchestration.” The challenge lies in ensuring the IMF and other international partners understand that these are targeted monetary tools designed to correct market failures, not artificial subsidies. This approach requires sophisticated monitoring and evaluation skills.

Capital: If lending caps are lifted, how can we ensure that funds don’t simply flow into non-productive areas like real estate or retail trade?

Eshetu: That is the crux of the issue. If banks, after caps are lifted, channel funds into real estate, wholesale, or import-focused retail trade, the inflationary impact will be identical to that of domestic government borrowing.

However, if that capital enters the productive sector—manufacturing or export-oriented industries—the impact is transformative. It creates structural change by easing supply-side constraints. When the Central Bank shifts its focus from merely managing the “money supply” to monitoring the “quality of credit distribution,” the results will be profound. We must move away from a culture that prioritizes easy, import-driven returns and toward an ecosystem that rewards value-added production. Lifting the cap is a vital first step, but it must be paired with disciplined, productive-sector-focused credit policy to be effective.

Capital: Isn’t the National Bank of Ethiopia’s new strategy of controlling banks through reserve requirements just a return to the approach used in 2009?

Eshetu: Look, whether we like it or not, our current instruments for controlling inflation are price-related, and any market “swing” will have a significant impact. You can only withstand this by expanding supply. If you fail to do so, the resulting volatility increases the government’s debt repayment burden.

Why? Because as market prices rise, you are unable to break the cycle where domestic returns are driven by simple, non-productive activities. Consequently, you cannot stop imported inflation or inflation driven by rising local production costs. It is a vicious circle.

The path currently being taken is the correct one. Authorities understand that they must continuously monitor credit allocation. Are loans going to the productive sector? By ensuring they do, you expand supply, increase tax capacity, and reduce domestic borrowing. Simultaneously, this strengthens your ability to maintain price stability. In 12 to 24 months, as the system stabilizes, we will be in a much better position than we were during the “cap” period.

Regarding the “cap,” it simply allowed banks to lend to whomever they chose, often relying on existing, relationship-based lending. If a stranger approached them for a loan, they would often turn them away, citing risk assessment. The question is whether the current method will change this behavior, as the bank is effectively saying, “I will control you through a different set of levers.” That is my primary concern.

The challenge you are raising is one that countries like Tanzania, Rwanda, and Uganda have faced. They didn’t overcome it through a “cap”; they succeeded by fine-tuning the monetary instruments already at their disposal.
Capital: Given the high liquidity compared to the mandatory reserve, the changes in interest rates, and the pressure on “idle” funds, what is your outlook for the market?

Eshetu: This is precisely why I stress that success hinges on operational orchestration, skill, and discipline. The mere presence of liquidity in the system doesn’t dictate bank behavior. I always adopt a CEO’s perspective: if I were in that position, what would I do?

In a credit-capped environment, the focus shifts from who to lend to to which loans will generate a return with the least hassle. Currently, Treasury bills offer 10-11% returns, while most banks’ average cost of funds hovers between 4.5% and 5.5%. If the net interest margin on government T-bills is 11.5%, you’re looking at a comfortable 6% net margin every few months—without the need for provisions. As an operations manager, my priority would be to acquire these T-bills and bonds. However, this strategy fuels domestic borrowing and crowds out the private sector. The only private sector loans that survive are “safe,” collateralized, and relationship-based—often in trade or imports, which are inherently inflationary.

Reversing this trend—by mandating loans to the productive sector, regardless of the cap—is what reduces domestic borrowing and boosts the Ministry of Finance’s tax collection capacity. Operationalizing this requires internal capabilities, such as a standardized system for reporting credit disbursement by sector.

When all banks report their credit disbursements using the C-code, the flow of money becomes transparent. If it’s directed towards trade or import financing, it’s inflationary. If it goes to productive sectors, it expands supply, generates revenue for the Ministry of Finance, and lessens domestic government borrowing.

If authorities genuinely implement this, the outcomes will benefit everyone. However, if this is merely a temporary “tick-the-box” exercise to satisfy IMF conditionality—a way to claim “mission accomplished”—then we’ll see inconsistent results. It’s like students: some study out of internal motivation, while others only do so under duress.

We aren’t undertaking this for the IMF; we must do it to “clean house,” shield our citizens from inflation, and foster productive employment. The Ministry of Finance and the Central Bank must fully grasp that domestic borrowing harms the economy, whereas productive sector lending strengthens it. They must move beyond mere “lip service” and ensure these policies translate into actual, daily practice.
Road network grows at 75

0

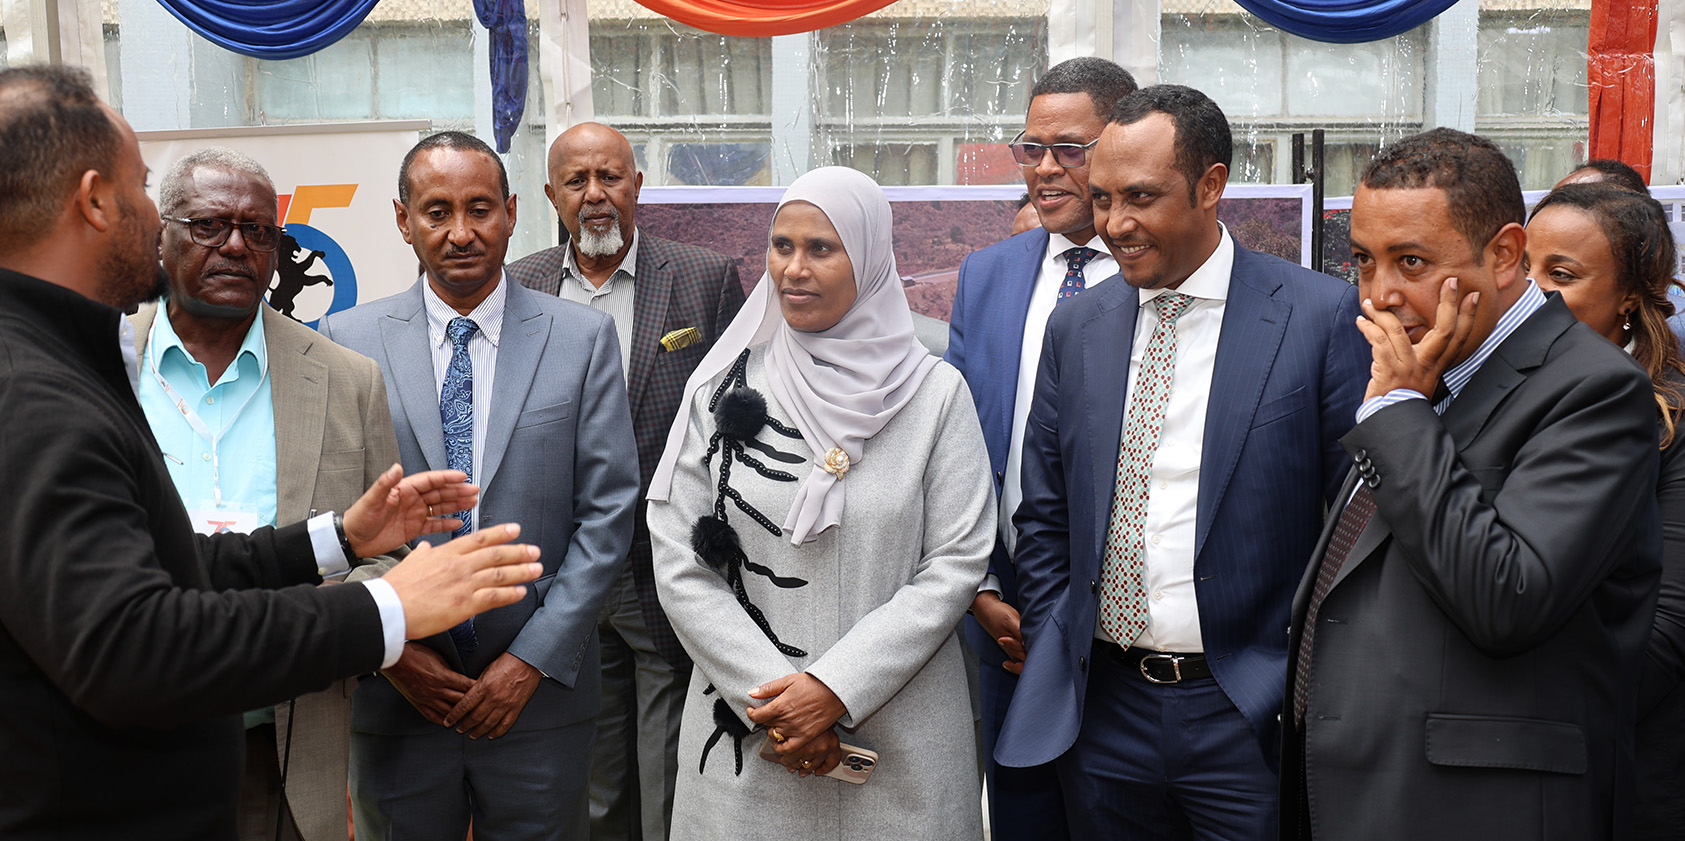
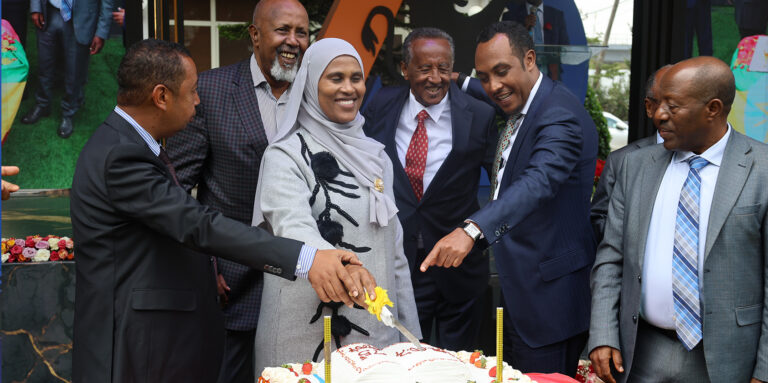
The Ethiopian Roads Administration (ERA) has launched its 75th anniversary Diamond Jubilee celebrations in Addis Ababa, highlighting decades of work that helped expand the country’s transport network and support national development.

The opening ceremony brought together government officials, former leaders of the institution, development partners, contractors, consultants and staff. The event reviewed the agency’s history while also reaffirming its commitment to future infrastructure development through modern and technology-driven transport systems.

Urban and Infrastructure Minister Chaltu Sani said the agency has grown significantly from its early years and stressed that the jubilee should serve as a moment to align with Ethiopia’s broader development goals. She said road infrastructure remains central to industrial growth, agricultural productivity and tourism, adding that institutional reforms based on digital systems and modern technology will remain a priority.

ERA Director General Mohammed Abdurahman said Ethiopia’s road network has expanded dramatically since the institution was established. He said the total network stood at only 6,400 kilometers at the time, but has now grown to 182,232 kilometers through successive road sector development programs.

He described the milestone as the result of vision, commitment and professional dedication over generations. According to him, the agency has moved from basic gravel roads to asphalt concrete highways, toll roads and major bridge networks.

ERA Board Chairperson Eyob Tekalign said the expansion of the network has helped connect the country from end to end, supporting trade, social integration and economic activity. He said the road system continues to play a crucial role in advancing national development objectives.

The three-day jubilee program includes historical photo and document exhibitions showing the evolution of Ethiopia’s transport sector, technology displays and panel discussions. It also features recognition ceremonies for outstanding contributors, as well as cultural presentations.

ERA said the celebration is not only about marking history but also about renewing its commitment to quality, safety and sustainable asset management in the years ahead.

Ethiopia must build resilience before the next oil shock

0

Ethiopia cannot afford to wait for the next global crisis to expose the weakness of its economy. The ongoing conflict involving Iran, and the resulting tension around the Strait of Hormuz, is a stark reminder that countries heavily dependent on imported fuel live at the mercy of events far beyond their borders. For Ethiopia, the lesson is urgent: structural economic resilience is no longer a policy option, but a national necessity.

Oil shocks do not remain in the oil market. They move quickly into transport costs, food prices, industrial production, foreign exchange demand, and public finances. In a country like Ethiopia, where fuel imports are essential to moving goods, powering businesses, and sustaining urban life, a sudden rise in global prices can ripple through the entire economy. When shipping routes become vulnerable or supply chains tighten, import-dependent states face immediate inflationary pressure and fiscal strain.

This is why the current crisis matters even if the conflict is geographically distant. The Strait of Hormuz is one of the world’s most important energy chokepoints, and any disruption there sends a signal to every economy that relies on imported petroleum. Ethiopia, like many developing countries, has limited ability to absorb such external shocks without pain. That reality should push policymakers to move beyond crisis response and toward structural preparation.

The first priority is reducing dependence on imported fuel wherever possible. Ethiopia must accelerate investment in domestic energy alternatives, especially hydropower, solar, wind, geothermal, and other renewable sources that can displace imported petroleum in electricity generation and, over time, in transport and industry. The country has already made progress in hydropower, but resilience requires diversification, not reliance on a single source. A more balanced energy mix would make the economy less vulnerable to price spikes and supply interruptions.

The transport sector also needs urgent reform. Ethiopia’s economy still relies heavily on fuel-intensive road transport. That means every dollar increase in oil prices raises the cost of moving agricultural goods, consumer products, and industrial inputs. Expanding rail logistics, improving urban mass transit, and encouraging electric mobility where feasible would help soften this dependence. Electrified transport is not a luxury in Ethiopia; it is a strategic economic shield.

Agriculture too must be part of the resilience agenda. Rising fuel prices increase the cost of fertilizer transport, irrigation, milling, and food distribution. When fuel becomes more expensive, food inflation often follows. Ethiopia should strengthen local production systems, modern storage, agro-processing, and regional supply chains so that food markets are less exposed to imported input costs and external shocks. A resilient food economy is one of the best defenses against energy turbulence.

Foreign exchange policy is another major front. Oil shocks drain hard currency quickly, because fuel imports must be paid for in foreign exchange. For Ethiopia, where foreign currency is already scarce, this creates a dangerous squeeze. The country must improve export performance, broaden the foreign exchange base, and reduce unnecessary import demand. That means supporting sectors that generate hard currency, such as horticulture, coffee, manufacturing, minerals, and digital services, while also tightening spending discipline on low-priority imports.

At the macroeconomic level, the state should develop stronger shock-absorption mechanisms. Strategic fuel reserves, more flexible procurement systems, and contingency financing tools can help cushion short-term disruptions. But buffers alone are not enough. Ethiopia needs a policy framework that assumes volatility rather than treating it as an exception. That means planning budgets, subsidies, and public investments with global risk in mind. If public policy is built on the assumption that oil prices will remain stable, the country will keep getting surprised.

There is also a lesson for industrial policy. Import dependence weakens sovereignty. Every economy that imports almost everything it consumes becomes fragile, no matter how ambitious its development plans may be. Ethiopia must therefore connect resilience to industrialization. Expanding local manufacturing of fertilizers, construction materials, consumer goods, and renewable-energy components would reduce exposure to external price shocks and create jobs at the same time. A more productive economy is a more defensible economy.

The political dimension should not be overlooked. Global crises often expose the gap between rhetoric and preparation. Leaders speak of transformation, but resilience is built through boring, disciplined work: infrastructure, institutions, diversification, and strategic planning. Ethiopia must treat energy security as national security. That means breaking the habit of reacting after prices rise and instead building systems that can absorb the next shock before it arrives.

The country does not need to isolate itself from the global economy. On the contrary, it should trade, invest, and integrate more deeply. But integration without resilience is vulnerability disguised as progress. Ethiopia should enter the global economy with stronger domestic buffers, more diversified energy sources, and a clearer sense of which sectors are essential to national stability.

The war in Iran and the threat to the Strait of Hormuz are reminders that geopolitics can rewrite economics overnight. Ethiopia has no control over those events, but it does control its own level of preparedness. The question is not whether global oil shocks will come again. They will. The real question is whether Ethiopia will continue to be caught off guard or finally build an economy that can endure them.

That is the challenge now: to make resilience a national project, not a crisis slogan.

Djibouti, Tiryaki Agro sign port MoU

0

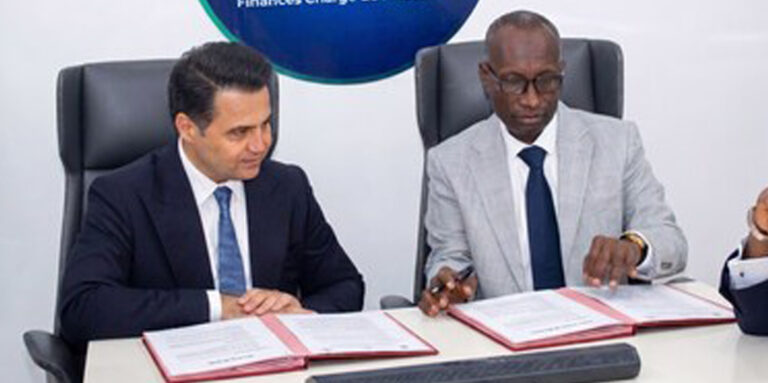
Tiryaki Agro, a Turkish agribusiness and logistics firm, is poised to become a significant international player in the Horn of Africa’s increasingly competitive port and logistics sector. This follows the signing of a Memorandum of Understanding (MoU) with the Djibouti Ports and Free Zones Authority (DPFZA) to explore the long-term management and operation of Tadjourah Port.

This agreement underscores Djibouti’s ongoing efforts to attract global private investment and solidify its position as a strategic maritime and logistics hub. The port overlooks the Bab el-Mandab Strait, one of the world’s busiest shipping corridors.

Under the MoU, Tiryaki Agro and DPFZA will negotiate a framework that could lead to a long-term concession agreement for Tadjourah Port’s management and operation. Before detailed negotiations and definitive agreements, both parties will conduct technical, commercial, and operational assessments.

According to DPFZA, this partnership is a significant step toward modernizing and expanding Tadjourah Port. It also aims to position Djibouti as a regional hub for trade, logistics, and agricultural supply chains serving the Horn of Africa.

The project includes substantial upgrades to port infrastructure, expansion of logistics and storage facilities, improved handling capacity for agricultural and bulk commodities, and broader investments to enhance regional trade connectivity and economic development.

Officials state that this initiative will not only strengthen Djibouti’s logistics sector but also improve food security and supply chain resilience across the wider Horn of Africa through increased private-sector participation.

The MoU also lays the groundwork for negotiating a long-term concession agreement that would formally grant Tiryaki Agro responsibility for managing and operating the port, pending successful completion of feasibility studies and negotiations.

This project builds upon an earlier partnership between Tiryaki Agro and the International Finance Corporation (IFC), the private-sector investment arm of the World Bank Group.

 The IFC has supported the initiative from its early stages by financing feasibility studies, strategic planning, and stakeholder engagement activities that helped shape the project.

This advisory support aims to unlock Djibouti’s potential as a strategic logistics gateway and encourage sustainable private-sector investment in transport infrastructure and agricultural trade.

“The signing of this Memorandum of Understanding marks an important step forward in our long-term commitment to Djibouti and our vision of contributing to the country’s role as a regional trade and logistics gateway,” said Süleyman Tiryakioğlu, CEO of Tiryaki Agro.

He thanked the Government of Djibouti, DPFZA, and IFC for their collaboration, expressing the company’s eagerness to advance the project’s next stages and strengthen regional trade, food security, and sustainable economic development.

DPFZA affirmed that the initiative aligns with Djibouti’s long-term vision of serving as a strategic logistics bridge connecting Africa, the Middle East, and global markets.

The Turkish company’s involvement comes months after Djibouti revealed that Ethiopia had declined an offer to take a leading role in administering Tadjourah Port.

In April, Capital reported DPFZA Chairman Aboubakar Omar Hadi stating that Addis Ababa preferred negotiating a broader corridor arrangement linked to port access rather than directly participating in the port’s administration.

Speaking to Capital, Hadi emphasized Djibouti’s continued commitment to working with Ethiopia and offering extensive facilities for Ethiopian trade.

“We are working well with the government and offering them all the facilities they need to use our ports. We are very open to Ethiopia,” he said.

Djibouti has proposed equity participation as part of its engagement with Addis Ababa. Since Eritrea’s independence in the early 1990s, Ethiopia has been landlocked, losing its direct access to the Red Sea. This issue continues to shape Ethiopian foreign and economic policy. Critics have long argued that the former Ethiopian People’s Revolutionary Democratic Front failed to secure sovereign or guaranteed maritime access during the negotiations surrounding Eritrea’s independence.

Today, Ethiopia is the world’s most populous landlocked country, making access to seaports a strategic national priority.

Over the past several years, Addis Ababa has intensified efforts to secure reliable maritime access, arguing that the loss of direct sea access represents a historic injustice that must be addressed through peaceful negotiations.

The debate escalated on January 1, 2024, when Ethiopia signed a controversial Memorandum of Understanding with Somaliland. This agreement sought access to a port on the Gulf of Aden in exchange for a stake in state-owned enterprises. The deal generated strong diplomatic opposition from Somalia and heightened geopolitical tensions across the Horn of Africa.

Following these developments, Djibouti proposed alternative arrangements involving access through Tadjourah Port. However, Ethiopia’s reported request for a broader corridor arrangement—including possible special transit or administrative rights—appears to have complicated negotiations.

The Tiryaki Agro agreement also reflects growing international competition among foreign investors seeking strategic positions in Horn of Africa ports.

In October 2025, Djibouti awarded a 30-year concession to Red Sea Gateway Terminal International, a subsidiary of Saudi Arabia’s Jeddah-based Red Sea Gateway Terminal (RSGT), to operate port facilities on the Red Sea.

Saudi-backed RSGT has also agreed to participate in the operation and future development of Tadjourah Port, underscoring the increasing interest of Gulf investors in regional maritime infrastructure.

Elsewhere in the region, UAE-based DP World operates Berbera Port in Somaliland under a long-term concession agreement and continues expanding logistics facilities there.

Other international investors have expressed interest in developing and operating ports across Eritrea, Somalia, and Sudan, despite ongoing political instability and security challenges, particularly Sudan’s continuing civil war.

The rush by global operators into Horn of Africa ports is driven by the region’s strategic location along one of the world’s busiest maritime trade routes, connecting Europe, Asia, and the Middle East.

Bab el-Mandab serves as the gateway between the Red Sea and the Gulf of Aden, making nearby ports critical nodes in international shipping and energy transportation.

Beyond commercial interests, Djibouti has become one of the world’s most strategically important military locations.

China established its first overseas military base in Djibouti adjacent to the Doraleh Multipurpose Port, where Chinese state-owned China Merchants Group also holds a significant ownership stake.

The United States, France, Japan, Italy, and several other Western countries also maintain military facilities in Djibouti, reflecting the country’s strategic importance for global security and maritime trade.