Ethiopian football record champions St George four year trophy draught appears to come to an end following the league season first round incredible performance. St George tops the league table three points clear of second place Wolayeta Dicha.
The first round only unbeaten side, scoring 24 goals while conceding only six and an amazing five consecutive clean sheets, St George is the most accomplished side taking the driver’s seat with 31 points from eight wins and seven draws.
A hard to beat goalkeeper, a strong defense an industrious midfield and a deadly strike force, it appears up to the club to lose the title rather than it’s adversaries efforts.
Maybe considered the surprise package of the first round Wolayeta Dicha is second in the roaster with 28 points from eight wins, four draws and three defeats.
Tsegaye K/ Mariam at the helm Dicha is considered the major title contender next to fourth place Fasil Ketema currently in some sloppy forms. Hawassa Ketema under head coach Zeray Mulu appeared to be in strong title contention sitting just four points behind the leaders.
Defending champions Fasil Ketema is still the strongest title contender despite camping fourth in the table five points behind the current league leaders. Resigning their former striker Mujib Kasim back from Algeria, Fasil is expected to be the strongest contender to retain the title.
Just six points behind the leaders Sidama Bunna joined the top five teams battling for the title. Gebremedin Haile who led AbaJifar and Mekele Ketema to championship title has a potential to turn around Sidama Bunna to one of the title contenders.
St George tops the league table at the end of the first round
South Sudan shocks Tunisia in World Cup qualifier
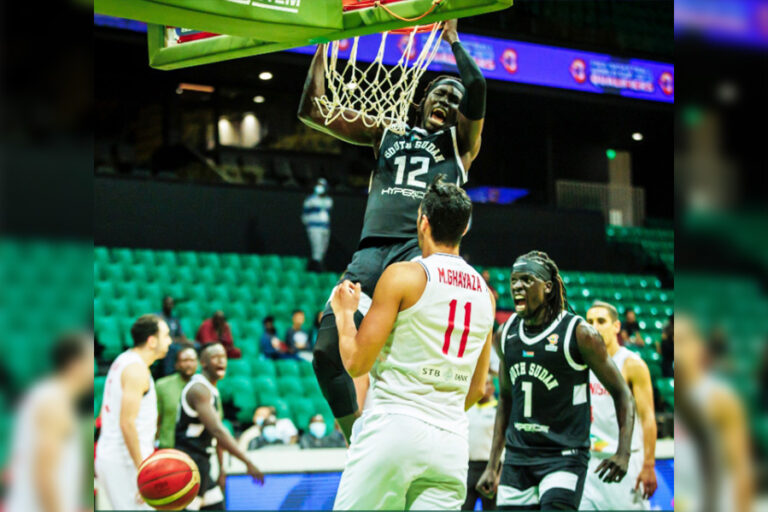
Back in September, Tunisia trounced South Sudan, 80-65, in the 2021 AfroBasket Quarter-Finals on the way to their third African title. Fast forward to Saturday, February 26, and South Sudan shocked the African champions Tunisia, 72-64, on Day 2 in Group B of the FIBA Basketball World Cup 2023 African Qualifiers in Dakar.
The World Cup African Qualifiers debutant’s win ends Tunisia’s winning streak on the continent of Africa, which lasted since February 2020 during the 2021 AfroBasket Qualifiers.Tunisia had been in difficult situations before in African basketball tournaments.
Remember when they trailed by 18 against Egypt at 2021 AfroBasket, and managed to turn things around in the last two minutes? They almost did it again. After trailing 68-57 with 2:43 minutes left, Tunisia outscored South Sudan 7-4, but the South Sudanese closed the game out by taking as much time as possible from the shot and contesting every one of Tunisia’s possessions.
Stats don’t lie: South Sudan stepped on the court knowing that beating Tunisia would require a tremendous team effort, and they played as a unit, which allowed them to lead in all but 24 seconds of the game.
After scoring just 55 points in Friday’s triumph over Cameroon, Tunisia struggled to create open shots, mainly due to South Sudan’s aggressive defense game.
It’s a major morale booster for South Sudan, a team that continues to make strides in the African basketball scene. If they beat DR Congo on Sunday, they will have a good chance to progress to the Second Round of the African Qualifiers, and become a contender for one of the tickets to the FIBA Basketball World Cup 2023.
Religion and Capitalism

The publication of George Gilder’s “Wealth and Poverty” in 1998 and, later, his work on “Recapturing the Spirit of Enterprise” brought renewed emphasis to capitalism’s spiritual side. George Gilder’s writings, along with Michael Novak’s “The Spirit of Democratic Capitalism”, provided a desperately needed counter to the almost century-long trend of casting capitalism in a morally negative side.
But George Gilder’s books also unfortunately implied that Adam Smith had ignored spiritual aspects of capitalism, suggesting that Smith concerned himself more with technical factors of supply, demand, and price. Such a misperception seeped into the work of writers of all political stripes, resulting in critics of capitalism from the Left, including Michael Harrington and Robert Heilbroner, and from the Right which includes Irving Kristol and Richard Weaver, charging that material progress occurred only at the expense of individual dignity or of society’s spiritual values.
Adam Smith explained that individual self-interest required a person to serve his fellow man to obtain a return. Whatever the motivation, the individual must focus on the desires and needs of others, address those needs, and provide a good or service before receiving any recompense. Another way to look at those activities is as service. A person must first serve others before demanding a return. Determining how much value the service has is fraught with problems if one leaves it to an arbitrary source, such as a government board or commission.
Market economies typically use money as a measure, or symbol, of how much service one individual has provided to others. Economist Walter Williams has detailed on several occasions how the process works in daily life. A woman sits down in a restaurant and orders a meal which represents the accumulated efforts of farmers, shippers, meat packers, the restaurant owner, the waiter, and others; but in order to pay for the meal, she must have money. Her money represents her own service to others that she has performed in her clothing business and the value that others have placed on her service to them. Money acts as a type of “accumulated service to others” which is a proof that the holder has served others, and to what degree.
Assume that an entrepreneur starts a hamburger stand. In doing so, he invests time, energy, and talent procuring products, facilities, and employees. Before earning a single dime, he has served others by making these investments of time, talent, and energy. The entrepreneur still has not received any personal return, which comes from meeting his customers’ culinary needs or desires. What if he provides terrible food? Or what if the food is good, but he is abusive and crabby to his customers? In either case, he will soon be out of business (not in Ethiopia of course!). He has not served his fellow man, nor has he met any need or fulfilled any desire. Note that despite working hard, he has not benefited others!
Consequently, labor itself is not sufficient as a measure of value. Indeed, unwanted labor is economically useless in one economic sense, in that it allows a single person to consume scarce resources without returning anything to society. Rather, labor that does not serve others, in a market sense, is actually consumption, not production. All economic activity can then be summarised with a question – “How have you served your fellow man?”, and an imperative, “Prove it!”
Adam Smith thought that most people were naturally inclined to such service, but that they naturally overestimated the value of their own labor and underestimated that of others. Consequently, the only reliable measure that could adjust for the individual misperceptions of millions of people in the market was the crucial price mechanism. Prices forced on everyone a reality check, so they could not overestimate their own service or undervalue that of others. For that reason, he warned about any distortions of prices brought about by anything other than the market itself. His warning extends to business combinations, monopolies, in current jargon, or businesses obtaining special privileges from governments.
Indeed, it is important to realize that any economic activity not solely derived from market effects can produce negative results. Charity, for example, generates its own economic implications. If individuals, Churches, community groups, or governments provide for nothing, or at artificially lower cost, what others in the market would charge to provide, that free service will have an impact on the price and affect the market. Labor unions have long resisted efforts to have prisoners perform work, contending that “slave labor” undermines the price of “free labor,” and they are correct.
If a farmer simply gave food away for whatever moral motive, it would have the effect of driving down the price of food everywhere, essentially telling other farmers that their service is worth less than it really is. Artists, musicians, writers, and actors have long faced the grim reality that their love of their craft means that they would paint, act, write, or play music if no one paid them, which has had the effect of driving down the price of all art. In short, all activity, even charity, has economic outcomes that affect prices. Giving goods away creates another problem. Gift givers don’t always choose what the recipient wants.
A final point alludes to one of our earlier questions, namely, how do others benefit from the failure of entrepreneurs? First, when entrepreneurs fail, they provide critical information about the wants and needs of others. The collapse of one business company may suggest, for instance, that the location is wrong. But it might also be that the product is poor quality or too expensive, or that the owner have other things to do. Here, one thing is certain. Other aspiring similar businesses will think twice before venturing into that location. Second, failure of a business frees up resources for the use of other businesses. The former location of the failed company may be the perfect location for the business. Third, not only do other businesses benefit from failed enterprises, but consumers profit, too.
In fact, some of the world’s greatest success stories resulted from abject failure. For example, America’s Automaker Henry Ford, banker A. P. Giannini, and department store founder Sam Walton all declared bankruptcy, had their first enterprises fail miserably, or were unceremoniously kicked out of companies they created before they attained ultimate success. In other cases, entrepreneurs have made fortunes or founded thriving businesses in services or with products that few would find lucrative. Yet no matter what path a particular entrepreneur took, each had a single characteristic in common: a willingness to take a risk.
The element of risk taking by entrepreneurs which, again, constitutes an act of faith and not reason, sets them apart from managers and paid employees. No element of business enterprise is risk free, and certainly management and labor have seen periods of mass layoffs. Ultimately, the only source of a job is one’s own talent and labor. The worker’s ability, in essence, creates his own employment demand. But in general, companies in capitalist societies offer a far higher level of income security and, whenever possible, extended employment to managers and employees than typical entrepreneurs ever attain.
In most small businesses, employees receive pay even if there is not enough left for the owner at the end of the week or the month. Different research studies revealed that many small-business owners have reported not taking their salary for years, plowing every cent back into their business.
Multi-bank account holders to merge accounts
The financial sector regulatory authority, National Bank of Ethiopia (NBE), urge banks to coalesce together multiple accounts owned by a single entity or individual.
It is to be recalled that the regulator gave banks set directives on knowing your customers (KYC) and customer due diligence (CDD), to which banks were in a rush to comply following the timeframe of six months which was set to authenticate customers’ accounts with required information and data, for the directive issued on August 27.
The operation has since then been concluded as per the given time frame and as Capital has learned banks have now got a new order from the regulatory body to harmonize duplicated bank accounts under one and single account as per the preference of their customers.
This now means that a bank customer who has multiple accounts in a single bank for instance the Bank of Abyssinia will have to merge all his/her accounts to one as per preference. “All the saving amounts will be included under a single account according to the preference of the account holder,” explained a bank clerk that Capital spoke to.
Currently, there are over 72.3 million bank accounts but it is common for a single customer to have more than one account in a similar bank which duplicates the number of accounts.
As was the norm, bank branches used to insist customers to open account in their branches without double checking whether they had similar accounts on other branches of the same bank.
Now as per the decision of NBE, bank branches have started approaching their customers to merge their accounts under a single account. This has also resulted in branches to compete for customers to settle in their account branch as opposed to the other.
One bank customer told Capital that unusually he has got a call from one of the bank branches where he is a depositor. “In this particular bank, I have more than one account in different branches. Early this week, one of the branches reached out to me in order for me to stay at their branch. However, I explained to them that the branch closer to my office and business activity was far more convenient for me,” he explained.
Experts stated that such move by NBE mainly targets to strength the illegal act on the financial and related issues.
The KYC and CDD directive, ‘requirements for undertaking account based transactions and ensuring of regulatory limits directive No. FIS/04/2021’ stated that KYC and CDD practices are critical to ensure proper identification of customers, appropriate assessment and monitoring of transactions including ensuring of proper compliance to regulatory transaction limits set by NBE.
It added that the implementation of KYC and CDD will combat illegal and unauthorized transactions. Thus the directive ordered banks or microfinance institutions and payment instrument issuers to have relevant information of their customers. Article five, sub article 5.1 for instance stated that in opening a deposit account, a financial institution will at a minimum record comprehensive customer profile that allows it to acquire adequate knowledge of the customer and identify suspicious transactions in a relatively easy and swift manner. “To this end a financial institution will use annex I which is part of a directive as a sample on how financial firms register customers profile, of the directive as a minimum standard for account opening at all time in a manner that ensures consistency across the financial industry,” it added.
Under the direction of NBE financial firms were in rush to know their customers ahead of the deadline in February 2022. Accounts that were found to not have the required profile were to be transferred to the regulatory body, as per the issued directive.
To this end, in the past few weeks, banks have been approaching their customers through different communication tools like text message (SMS), phone call or media announcements, for customers to appear at their branches for rechecks in their accounts information.
Bank clerks that reside in different banks’ branches told Capital that the new scheme has become an additional workload for them since the number of account holders who are visiting their branches are growing by the day.
“The new scheme has imposed further burden on our day to day activity,” a clerk said.
The clerk explained that despite being in a branch that is not regarded as a big branch with regards to the number of account holders, the numbers of visitors have continued to increase in the past few weeks.
“Our bank has already called all its customers to visit their branches. We will also give a call for customers if they do not appear in the coming weeks,” another bank clerk that works at a branch located around Bole Medhanialem told Capital.
She said that the bank called all of its accountholders regardless of customers having the required document like photo and ID with the bank, for a thorough check.
One customer that Capital interviewed for instance said that he received an SMS from the bank that he has a deposit account with, and went on to visit his branch. “However I have learnt that all the required profile was already filled when I opened the account years back and I have proved that on my latest visit to my branch,” he explained his case.
The work load mainly on big banks is very huge according to bankers since their bank account holders are in millions, while the story of Commercial Bank of Ethiopia (CBE) is different owing to its large customer base.
One of the clerks that Capital talked to at one of the state giant CBE branches said that the number of customers visiting in relation with the latest announcement has an unprecedented flocking of customers at their doorstep.
CBE has over 34 million accountholders. Recently Yinager Dessie, Governor of NBE, said that in relation with last year’s currency change an additional 7.2 million bank accounts have been opened. It is estimated about 60 million accounts are opened across all banks.
The new rush is followed by the NBE directive of knowing your customers (KYC) and customer due diligence (CDD) that issued in August 27 which became effective the same day.
Experts stated that such move by NBE is mainly targeted to strength the illegal act on the financial and relate issued.
The KYC and CDD directive, ‘requirements for undertaking account based transactions and ensuring of regulatory limits directive No. FIS/04/2021’ stated that KYC and CDD practices are critical to ensure proper identification of customers, appropriate assessment and monitoring of transactions including ensuring of proper compliance to regulatory transaction limits set by NBE.
NBE had given six months starting from August 27 as a transition period for financial firms to capture required customer profile from its long time and new customers so as to issue a unique customers ID and introduce a centralized account opening approval. The transitional period included loading of the information to the financial institution’s system. For those who failed to comply with the requirements of this directive the penalty incurred would be from 20,000 to 100,000 birr which differs as per the britches, while other administration measures were to be applied.
According to the information obtained from bankers, the account of those who do not have the required profile will be transferred to the regulatory body.