Thursday, October 8, 2026
Home Blog Page 3225

The Taliban and the Dollar

0

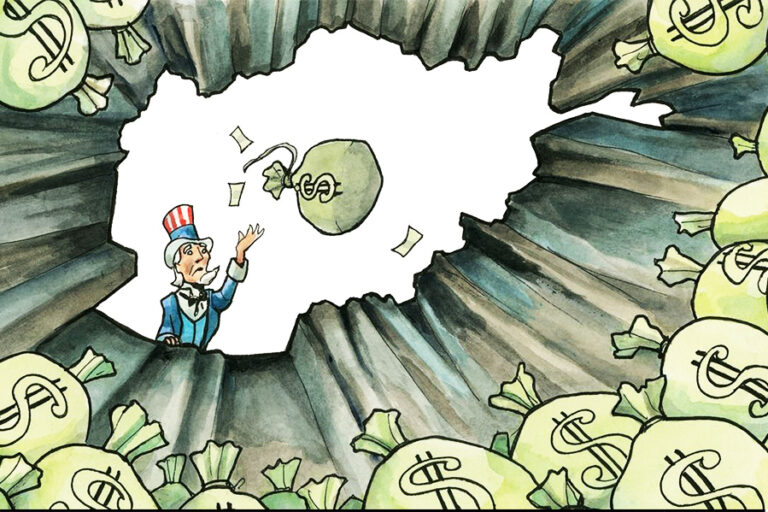
In the half-century since US President Richard Nixon closed the curtain on the Bretton Woods system, the US dollar has been the dominant global currency, largely because there were no other aspirants to the throne. Nonetheless, recent events have reminded us that conditions can change both gradually and suddenly.
By JIM O’NEILL
This month marks the 50th anniversary of the end the Bretton Woods system, when US President Richard Nixon suspended the US dollar’s convertibility into gold and allowed it to float. We are also approaching the 20th anniversary of the Taliban’s removal from power in Afghanistan at the hands of US-led coalition forces. Now that the Taliban has again prevailed, we should consider whether its victory over the world’s most powerful military and largest economy will have any implications for the dollar and its role in the world.
Looking back over the 50 years since Nixon closed the gold window (39 of which I spent being professionally engaged in financial markets), the biggest takeaway is that the floating-exchange-rate system, and the dollar’s dominant role in it, has turned out to be more robust than initially expected. Even knowing what we know now about the evolution of the world economy, most experts would have doubted that the system could survive for as long as it has.
Given this resilience, it is tempting to dismiss America’s failure in Afghanistan as inconsequential for the dollar. After all, the greenback weathered the fall of Saigon in 1975 and the debacle in Iraq following the US invasion in 2003. Why should this time be any different? Ultimately, the answer depends on one’s expectations about the evolution of the world economy and the behavior of its principal financial players, namely China and the European Union.
To understand the dollar’s prospects, consider three key reasons why the current system has persisted. First, most countries did not choose to have their currencies float freely against the dollar. Even though more countries have floated their currencies in recent decades, others have maintained fixed exchange rates, devised their own regional exchange-rate relationships, or launched a common currency – as in the case of the euro.
Second, and on a related note, the few countries that had enough economic heft to influence the global monetary system Japan, Germany (previously West Germany), and, more recently, China made a conscious decision not to do so. True, the German Deutsche Mark played a regional role from 1973 until the establishment of the European Monetary Union in 1992 and the introduction of the euro in 1999. But beyond that, Germany consistently took steps to keep its currency from assuming a larger global role.
Moreover, German authorities have persistently opposed the idea of pan-European bonds (notwithstanding the EU’s decision last year to launch a COVID-19 recovery fund based on mutualized debt obligations). Without a common budget, the euro will always be held back from competing with the dollar or playing a much bigger role in the world financial system.
As for Japan, it never showed any interest in a global role for the yen, even in the 1980s and 1990s, when it was fashionable to believe that the Japanese economy would catch up to that of the United States.
Finally, despite its frequent objections to the current global monetary system, China has long been reluctant to expand the renminbi’s footprint in financial markets both internally and internationally. Instead, China has indicated occasionally that it would prefer a global monetary order centered more around the special drawing rights (SDRs), the International Monetary Fund’s reserve asset, whose value is based on a basket of five currencies (the US dollar, the euro, the renminbi, the yen, and the British pound).
This idea has some appeal, especially in terms of global fairness. But it would be difficult to implement in practice. Not only would it depend on China allowing for more free use of the renminbi; an SDR-based monetary system also would have to be embraced by the US, which is probably a non-starter – at least for now.
That brings us to the third reason why the current system has lasted: the US wanted it to. As we saw during Donald Trump’s presidency, the US enjoys the benefits conferred by issuing the dominant global currency, not least its potential as a tool for pursuing diplomatic and security objectives. The Trump administration’s use of secondary sanctions against countries that did business with Iran was a perfect example of this. If current or future US leaders choose to use the dollar’s dominance in a similar fashion perhaps against countries doing business with a hostile Afghanistan – that could have a significant bearing on the currency’s future.
While the world marks the 20th anniversary of the September 11, 2001, terrorist attacks in the US, the IMF will be working on its mandated five-year review of the composition and valuation of the SDR basket. To the extent that the exercise increases the share allocated to renminbi, that will be taken as a sign that the world’s currency system is slowly but ineluctably evolving.
Just as China’s growing share of the global economy implies the need for a fundamental rebalancing, the renminbi’s share of the SDR basket cannot continue to grow without that increase meaning something for the future of the world financial system.

Jim O’Neill, a former chairman of Goldman Sachs Asset Management and a former UK treasury minister, is a member of the Pan-European Commission on Health and Sustainable Development.
Bumper Africa Travel Week in 2022

0

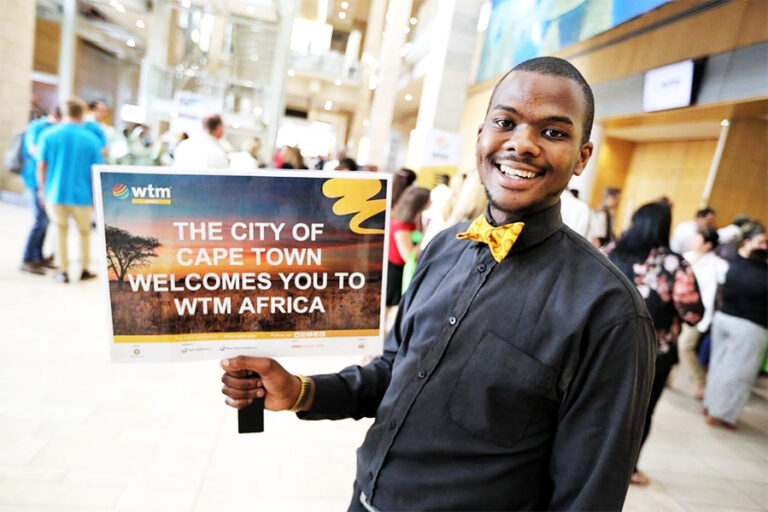
Africa Travel Week 2022 will go ahead from 11 to 13 April, 2022 in the Host City of Cape Town bringing together Pan-African & International exhibitors as well as buyers from across the globe at headline shows, World Travel Market Africa (WTM Africa) and International Luxury Travel Market Africa (ILTM Africa).
The highly anticipated event will include all the highlights delegates have come to expect in previous events, including a robust speaker programme and associated events like International Business Market Africa, EQUAL Africa, Travel Forward, Sports and Events Tourism Exchange (SETE) and the Africa Tourism Investment Summit (ATIS).
EQUAL Africa will bring together travel suppliers and buyers as well as lifestyle brands targeting the LGBTQ+ community. For the meetings, incentives, conferences and events industry, there’s ibtm Africa and stakeholders working in the sports, events and tourism industries won’t want to miss SETE. Lastly, Travel Forward is the leading travel technology show where travel executives and innovative solution providers gain access to cutting-edge insights, open debate and unrivalled networking opportunities.
Tourism investments across the continent will also be in the spotlight at the Africa Tourism Investment Summit, which WTM Africa will be co-hosting with the International Tourism and Investment Summit (ITIC). Our 2021 event was a resounding success, virtually bringing together investors and development projects to unlock a diversity of investment and business opportunities in tourism and travel destinations around the world that can be aligned with the UN 2030 Agenda – Sustainable Development Goals.
For the 2022 event, Africa Travel Week will renew its partnerships with organisations like the International LGBTQ+ Travel Association, the Africa Tourism Association and Africa Travel and Tourism Association to ensure that the themes addressed at the event will reflect those pressing issues for tourism stakeholders seeking to reignite tourism to the continent.
“Our partnership with the City of Cape Town is particularly noteworthy. We are privileged to be able to host a world-class event in a world-class city and can’t wait to welcome back all delegates to experience the best of Cape Town,” says Megan Oberholzer, RX Africa Portfolio Director Travel, Tourism & Creative Industries.
Executive Mayor Dan Plato, explains that the South African vaccination programme is gaining momentum, bringing the city a step closer to hosting large-scale events. He says: “We are pleased that Africa Travel Week 2022 will be part of those events. The City of Cape Town has worked with the tourism industry and other government counterparts to put together health and safety protocols to ensure we can safely welcome international visitors to our shores. Africa Travel Week is the perfect platform for us to showcase, to the international market, how our tourism sector has adapted to the times and improved on our already world-class offerings.”
“We have actively sought opportunities to keep the spirit of #MakingTravelHappenAgain on the African continent alive through our ATW Connect platform, Reignite Africa awards, podcasts, webinars, #UnlockAfrica series and more, so after two years of virtual connection, being able to meet face-to-face next April fills us with excitement, we are raring to go for next year April’s event,” adds Oberholzer.
ATW buyers have indicated their commitment to and excitement about attending a live event in April 2022. “We saw the pent-up demand from buyers with our virtual event in 2021 which saw over 5,000 successful 1-on-1 meetings held, 4,300 minutes of speed networking and 4,000 views of content sessions. Bringing the live and virtual together for 2022, we’re expecting even greater engagement, so watch this space,” concludes Oberholzer.

Italy extends funding for four archaeological missions in Ethiopia

0

The Italian Ministry of Foreign Affairs and International Cooperation has renewed the annual financial contribution for four archaeological missions in Ethiopia organized and led by Italian universities.
The University of Naples “L’Orientale” is the longest archaeological mission carried out by an Italian institution in Ethiopia, specifically in the area of Axum. The mission, led by Prof. Andrea Manzo, has been operating in Tigray since 1993 in cooperation with the International Association for Mediterranean and Oriental Studies (ISMEO) and the cultural bureaus in Mekelle and Axum.
This archaeological mission has largely contributed to the development of in-depth studies on the Aksumite kingdom. The University of Rome “La Sapienza” is the leader of three important archeological missions in Ethiopia. Since 1999 Prof. Margherita Mussi has researched the sites of Balchit and Melka Kunture, in the Upper Hawash Valley, to analyze the adaption of the Homo Erectus and Homo Sapiens’ species to the local environment.
Prof. Mussi, who is also the Director of the archeological site, has closely cooperated with local Authorities to promote the inclusion of Melka Kunture and Balchit in the UNESCO World Heritage List. The University of Rome “La Sapienza” has also carried on two archeological campaigns in 2017 and 2018 led by Prof. Enza Spinapolice in Gotera and Yabelo bringing to light the exceptional relevance of this area from an archeological standpoint, specifically for the study of the transition from the nomadic life to the pastoralist settlements.
For the first time, the Italian Ministry of Foreign Affairs and International Cooperation has decided to finance the archeological campaign conducted by Prof. Marina Gallinaro in Borana in order to study the rock art and the pastoral life that developed in this area. This project, which aims at researching and protecting rock art’s sites, has been developed in close cooperation with the Oromia Culture and Tourism Bureau.
These archeological campaigns are realized in coordination with the Ethiopian Ministry of Culture and Tourism and the Authority for Research and Conservation of Cultural Heritage (ARCCH), stressing the strong and long-lasting cultural ties between Ethiopia and Italy.

FINANCING HOUSING

0

Goh Betoch Bank SC is a new dynamic bank in town which is set to open its doors soon. The bank when operations begin will be the first mortgage financial firm aiming to bridge the gap in the challenging financial housing market.
This extraordinary bank has its sight set on realizing a better form of housing for all Ethiopians by providing strong financial schemes which stems from the great need of housing in the country. To make sure these goals are realized it has appointed its first ever president, Mulugeta Asmare, who himself is no stranger to the financial industry. Mulugeta’s career has grown astronomically over his close to 3 decade involvement in the financial industry. He has served also in top levels of management as he previously was the president of Abyssinia bank. Capital sat down with this financial expert, for an in-depth look into the country’s first private mortgage bank. Excerpts;

Capital: You are the first CEO of the first private mortgage bank in the country. How can you express this feeling?

Mulugeta: It is a big pleasure to be the first, however, at the same time it is a big challenge. We are getting in the market with a new system and operation which has never been in the country and it is going to be a strange and new arena.
We are trying to share experiences from other countries’ mortgage banks, which includes giving the proper education and trainings. So even if it is challenging, since its technically new grounds, we have embarked on this great journey, and we are confident that we will pass through the challenges and achieve great success in the process.

Capital: You have been leading one of the biggest banks in the country; don’t you think coming to a new organization will be a bit challenging?

Mulugeta: For the last 27 years I have been working in the banking sector in different positions up to the president or CEO level. For the last five years I have been working in Abyssinia bank as president. After my years of service, I saw it best to resign with my own consent so as to take a break and after one year of good recreation, I received an invitation from the organizing committee of Goh mortgage bank to join them.
Having realized the solution that they are going to provide in the market gap, which is important for the country and for the coming generation I wanted to be part of this monumental movement. However, in this market it is challenging to find the right CEO or president that can steer the financial institution to great strides. Moreover, to find the person with the right experience is a hurdle since in the sector there is a lack of experience in man power. Noting these challenges I decided to step up to be the CEO for a temporary period.
As the bank is new to joining the sector more so to the financial housing niche, I can understand that it can be presumed to be challenging since financing housing is one of the biggest challenges in the country. However, from my point of view, the bank could benefit our country, and I have decided to make a comeback not disregarding the challenges, but acknowledging that this could play an instrumental role in paving better housing for our country.

Capital: Can you elaborate for us the formation of the bank as a whole and also government’s support to its formation?

Mulugeta: Most of the financial institutions and their formation in our country are based on some regional, religious, ethnicity and similar foundations. This is of course always disheartening.
However as the political sphere of the country was the same, and as result lots of investors formed banks with someone they trusted and thought the customers would be drawn to them with the affiliation on the aforementioned basis of their bank’s formation. Of course not all banks are like that, there are some banks which are free from such kinds of formation but the effect is not noticeable.
Goh Mortgage bank is free from such kinds of mindset. This is evident since even the eleven organizers stem from different ethnic groups with different political views but have come together to join hands for a greater purpose. Individually, they are bankers with long experience in the sector with no personal interest except from forming the bank and benefiting the society and the country by solving the problem in the housing sector.
So we believe it will continue, by building a healthier Ethiopian institution which is free from any influence of religion, ethnic, or political beliefs.
The bank will engage mainly in financing the housing sector, and will also operate other banking operations which are similar with other commercial banks.
We are planning to support the majority of our society to have their own house by giving out long term loans, and to this end government has provided its backing as the National Bank of Ethiopia gave us the green light to for the bank license and we are waiting to commence operation.

Capital: When do you plan to start the operation? Similarly, how have you prepared in terms of technological readiness?

Mulugeta: In terms of technology we have selected a company called Technos in a bid to build a core banking system. With regards to opening our doors we plan to do that in the coming month. As we embark on our operation, we will use locally developed software for the transition period until the company completes its work, then we will upgrade to the same.

(Photo: Anteneh Aklilu)

Additional to the core banking, we are also building our own data center which will be completed in few weeks and be operational.
We have organized our head office and some branches; we have already hired employees and gave them trainings. The last thing we are waiting for is green light from the national bank to start our operation based on its supervision, since we have already received the license.
As previously mentioned, we are planning to start our operation in September 2021, and our doors are open to provide so our services to any Ethiopian citizen who can full fill the given criteria.

Capital: What kind of support are you waiting from the national bank, and also are you working with the Ministry of Urban Development and Constructions?

Mulugeta: The Ministry of Urban Development and Constructions is one of the different stakeholders in the housing sector and knows the gap properly. It is authorized to control the quality and speed of construction and wants housing to be widely available; in this case we expect the full support from ministry to build completely standard houses. Additionally, we plan to work and engage with the city administrations and also the mayor offices which are some of the other stakeholders.
The central bank is the superior bank where all the commercially banks are equally administrated. However since we are coming in with a different kind of bank, I believe that we need different kinds of practice stemming from the central bank. One of the biggest support of the national bank include; assembling long term deposit and loan and also creating a special policy practice where the central bank can create a conducive environment for the bank to thrive.
Additionally we may start working with international financial institutions to get long term funds and to this end we need the national bank to make new practices to facilitate our access and use of fund.
Prime Minister Abiy Ahmed has also said that the banking sector is only open for foreign mortgage bankers, which is a great move so we take it as a direction of hope that the national bank will also prepare different framework’s to benefit the new upcoming local bank as well.

Capital: How will the loan period being provided work?

Mulugeta: There are three different loan-term periods. The first one is a short term loan which has to be paid back in 12 months or in one year.
The other one which is stretched up to five years is the medium loan term whilst the last which is over five years is to be provided as the long term loan period. The last one could go for up to 30 years. Most of the loans in mortgage banks are long term loans. It is with this provisions that we seek a special policy framework from the national bank to allow us to give long term loan without proportion.