In a sweeping structural shift described by financial experts as “earthshaking,” Ethiopia’s central bank has delegated approval authority for Letters of Credit (LC) and Cash Against Documents (CAD) to commercial banks — a reform aimed at slashing bureaucracy and narrowing the gap between legal and parallel foreign exchange markets.
As part of broader structural changes aimed at liberalizing and modernizing the economy, the Ethiopian government continues to introduce sweeping reforms to rules and directives. On one hand, these changes target the financial sector; on the other, they aim to curb the illegal foreign exchange market and narrow the gap between the parallel and legal markets.
While some sector experts argue that commercial banks face limitations in implementing such massive changes, the central bank maintains that operational capacity is a strength of the banks themselves — not just the regulatory body.
As part of the financial sector and forex reform, the National Bank of Ethiopia (NBE) has taken bold decisions regarding the approval of LC and CAD, among other major moves in the forex market.
In a statement released midweek, the International Monetary Fund (IMF) noted that further efforts to enhance the functioning and transparency of the foreign exchange market will be important to support external adjustment.
The new NBE directive, FXD/05/2026, streamlines trade by delegating approval authority for LCs and CAD to commercial banks. It also allows foreign currency account holders to initiate shipments before bank approval and expedites payment processing, amending previous regulations to ease business operations.
Financial sector experts say this move — along with the introduction of a Franco-Valuta import directive — is key to tackling the parallel market trend while modernizing and creating a more functional forex business environment.
The new directive, they agree, helps remove procedural frictions that constrain the speed, cost and predictability of international trade for Ethiopian businesses.
Under the amended rules, commercial banks now hold the authority to approve import credit instruments — a mandate previously reserved for the central bank, which had long justified its control as essential for predictable resource utilization.
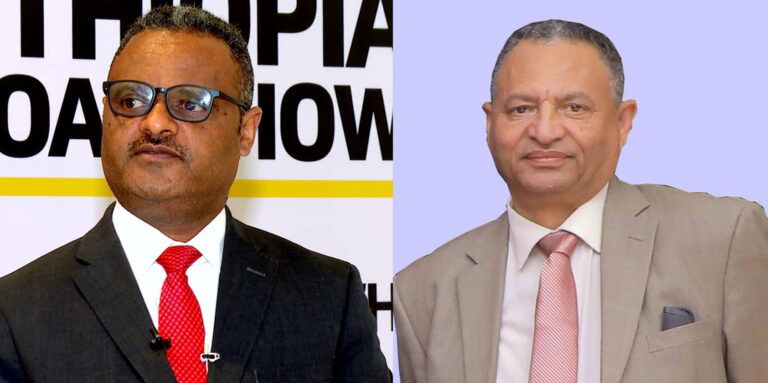
In an analysis published late last week, Eshetu Fantaye — a veteran financial professional with over 30 years of experience, including roles as president and vice president of financial institutions — explained the directive’s core economic effect on domestic prices.
According to Eshetu, FXD/05/2026 compresses procurement cycles. By removing NBE pre-approval delays and enabling pre-shipment ordering under Articles 3.3 and 3.4, the directive shortens the time between an importer’s purchase decision and the arrival of goods. This leads to faster replenishment of inventories, reducing supply gaps that drive up domestic prices when restocking is delayed.
The directive also contributes to foreign exchange market convergence through several channels. On the demand side, by making the formal banking channel faster and more operationally competitive with informal alternatives, it increases the share of import-related forex demand flowing through the formal banking system.
On the supply side, pre-shipment ordering flexibility enables export-oriented special economic zones (SEZs), manufacturers and agro-processors to cycle their retention account balances more rapidly — procuring inputs faster and exporting more quickly.
Eshetu noted that the reform sequence demonstrates a deliberate macro-to-micro progression. First, market pricing was established (FXD/01/2024). Next, investment categories (SEZ, wholesale/retail, banking) were opened, followed by the removal of income repatriation friction (FXD/04/2026). Finally, transaction-level processing delays are eliminated (FXD/05/2026). “Each measure is necessary but insufficient on its own; together, they form mutually reinforcing liberalization architecture,” he said.
Unlike a sight LC, which provides for immediate payment, acceptance-based LCs create a pipeline of forward foreign exchange obligations.
Experts such as Eshetu note that deferred imports could create unpredictable pressure on reserves, which is why the central bank believes it alone has the capacity to manage reserves at the macro level. They say this belief was the reason the central bank previously controlled LC acceptance.
However, some financial industry experts have reservations about local banks’ ability to handle their new responsibilities.
They insist the regulatory body must play its part to harmonize the liberalization process with a professional and effective response from the banks themselves.
According to experts, the new move essentially transfers risk to the banks. The key question is whether financial firms have the capacity to manage it.
Eshetu told Capital last week that banks need internal capacity in processes, screening, exposure management, document verification, regulatory reporting and human capital development.
In the past, the NBE took considerable time to process approvals; now that responsibility shifts to commercial banks, which previously only handled the administrative side when the NBE approved LCs or CAD on acceptance.
Eshetu explained that these credit instruments will now be managed by commercial banks, requiring complex internal administrative capacity not only for their direct customers, but also for their customers’ counterparties abroad.
Experts said the new law increases risks for banks. “They must conduct cross-platform assessments of the profiles of overseas counterparties, since they are now responsible for trade finance administration and approvals,” they said.
Eshetu stressed that banks are also responsible for anti-money laundering and sanctions screening, as well as managing exposure from deferred LCs and verifying end-to-end documentation previously handled by the NBE.
Through these three instruments, the central bank has pushed approval, management and risk mitigation responsibilities onto commercial banks.
According to experts, while this could generate additional income for banks, recent experience suggests the risks are real.
Insiders claim that several banks were affected by unsettled LCs when the NBE introduced forex liberalization about two years ago. Unless banks build strong internal capacity, the effect of the new deferred LC scheme could be severe.
Experts recalled that in the past, the NBE did not accept deferred LCs except for government imports or related sectors.
“It was unwilling to approve deferred LCs regardless of coverage. If it had allowed traders to use deferred LCs or CAD, they could have imported goods — particularly basic commodities — that would stabilize the market,” experts said.
According to Eshetu, if banks develop internal capacity, manage their local and foreign currency liquidity smoothly and work effectively with the deferred scheme, the market will undergo structural change.
“This is the basic difference between the Ethiopian and Kenyan markets in terms of commodity availability and inflation management at the macro level,” he said, adding that CAD or LC acceptance and pre-shipment provide a major advantage: ordering goods when prices drop, while enabling predictable price control and management.
Sector experts, including senior IDB directors, agreed that such schemes are particularly helpful for basic commodities, supporting not only speculation reduction but also price stability.
Experts stress that FXD/05/2026 does not reduce the total quantum of risk in Ethiopia’s trade finance system — it redistributes it.
In his analysis published late last week, Eshetu outlined four pillars banks must build to absorb the new responsibility: pre-approval credit and compliance underwriting, document verification, portfolio-level deferred FX liability management and post-transaction monitoring.
He argued these pillars help analyze importer creditworthiness, FX generation capacity, sanctions screening, trade document checking, real-time open acceptance registers, maturity concentration limits, periodic NBE reporting, anomaly detection, recovery procedures and correspondent bank feedback loops.
He emphasized that a banking system which previously operated under the protection of centralized NBE oversight must now perform those oversight functions itself.
This transition creates a window of vulnerability — approximately one to 24 months — during which banks will operate under delegated authority without the systems or trained staff required for international standards. “This window is the single greatest risk in the FXD/05/2026 implementation landscape,” he said.
Currently, most Ethiopian commercial banks process LCs manually or via basic core banking modules not designed for trade finance. While SWIFT connectivity is available at major banks — including CBE, Awash, Dashen, Abyssinia, United and Nib International — sophisticated trade finance platforms are either absent or in early development, according to experts.
Full deployment at large commercial banks is estimated at 12 to 18 months; for mid-tier banks, 24 to 36 months. “This makes the current moment urgent,” Eshetu said. “Banks that do not begin immediately will be operating the new delegated authority on manual, error-prone processes for one to three years, precisely when the highest-value trade finance clients are arriving in Ethiopia’s newly liberalized market.”
According to experts, it is worth recalling that the retail and wholesale trade sectors have been opened to international players, who are expected to operate on deferred payment schemes common in their home countries. The same applies to SEZs.
Currently, the central bank allows the scheme for foreign currency account holders and encourages traders — including small-scale operators — to engage in re-export.
Experts said that businesses that export goods from their industry can benefit by importing raw materials on time, generating foreign currency from products made with those materials.
Experts in investment banking and development banking say the new directive will also allow local producers to offer competitive prices on global markets. Moreover, it will build trust and boost investor confidence by stimulating the market, according to experts who recalled the NBE has recently relaxed dividend repatriation rules and allowed foreign financial players to operate in Ethiopia.
Experts, including investment banking directors interviewed by Capital, say the new scheme will help curb informal trade and reduce the illegal forex market.
Eshetu agrees, adding that the gap between legal and illegal forex markets would narrow to an acceptable level from the current estimated 19 percent.
Some experts believe that fees and charges requested by banks will become reasonable. Eshetu argues, however, that the directive’s impact on costs will be minor; correspondent banking relationships and local interest rates remain the key determinants.
He noted that the government should help improve correspondent banking relationships, as third-tier banks face much higher costs than first-tier banks. Ultimately, export growth and other means of forex mobilization must be amplified, and banks must change their structural position.
Capacity building and the central bank’s view
Experts say that in the past, policy focused on issuing price directives — adjusting interest rates and opening the forex market. Now, the task is to translate those directives into processes. These laws are execution frameworks handed to commercial banks. The question is whether they will take time to become effective.
In his analysis titled “Two Pages, Transformative Implications: Translating Foreign Exchange Directive FXD/05/2026,” Eshetu argued that the central bank should play a key role in capacity building for banks.
He told Capital that while capacity building is ultimately banks’ responsibility, when the NBE issues such earthshaking and structural shift laws, it should also provide a transition design to help financial institutions develop capacity plans to handle the new operational changes.
According to experts, this directive is a remarkable law that demands knowledge of treasury and finance. “Currently, we don’t have treasury management knowledge,” they said.
Eshetu elaborated: “We were working on fund management and treasury operation only when we had foreign currency. But now customers will come with the concept of importing goods now through open credit or pre-shipment, selling them in the market, and later paying by buying foreign currency from the market.”
Fikadu Digafe, vice governor and chief economist at the NBE, disagreed that banks need a fundamentally different type of capacity.
“They only need risk management capacity for risky areas. Some banks have been established for a very long time and have better capacity and know-how than the regulatory body,” he said. “Our main target for issuing this directive is to cut bureaucracy and minimize unnecessary costs.”
He added that banks requiring stringent capacity will build it themselves; the latest development does not require NBE involvement to push banks to improve their capability.
He noted that the central bank regularly meets bank executives, providing a forum for concerns. “For instance, we met yesterday, but such concerns were not raised. However, if necessary, we will cover them,” he told Capital on May 29, 2026.
Some experts claim that international partners like the IMF and the World Bank are only working with the government to enhance internal capacity at regulatory bodies. Such support, they argue, should also be extended to local private players — especially financial institutions — since they are the core implementers of radical macroeconomic and financial sector reforms.
In an exclusive interview with Capital in April at his Washington, D.C., office, Alvaro Piris, IMF Assistant Director for the African Department and Mission Chief for Ethiopia, said: “We do not provide technical assistance directly to the private sector. That said, we can help indirectly: if the authorities wish to provide training or organize a seminar for a private sector audience, we can assist them in preparing for that. So we can help in that manner, but we do not provide direct assistance to private entities.”
Fikadu reiterated that the central bank’s goal is to develop the market further and place it on a formal footing.
“We are now working to lift restrictions, give confidence to the business community and minimize processing time. At the same time, banks are expected to modernize their processes, distribute foreign currency fairly, reduce bureaucracy and build trust in the formal sector. Our main target is to smash informal business activity.”
According to Kassahun Mamo, deputy secretary general for business development and advocacy at the Addis Ababa Chamber of Commerce and Sectoral Associations, Ethiopia’s heavy reliance on imported goods has led to a sharp rise in landed import prices.
“Businesses are struggling to absorb these costs, fueling broader inflation, with SMEs hit hardest due to limited financial buffers,” he said.
Kassahun, a former part-time lecturer in economics at Addis Ababa University, told Capital that such moves will support imports and economic activity in general.
“High exchange rate volatility makes it incredibly difficult for businesses to set stable retail prices, manage inventory or make long-term investments because replacement costs change so rapidly,” the deputy head of the private sector lobby group added.