Tuesday, September 29, 2026
Home Blog Page 212

Aqua for All urges Ethiopia to mobilize private sector in WASH Sector with robust policy framework

0

As Ethiopia races to close widening gaps in water, sanitation, and hygiene infrastructure, the international organization Aqua for All is calling on the government to establish a clear, strong policy framework that can unlock private‑sector participation in the WASH sector.

The Netherlands‑based nonprofit argues that traditional funding models, which rely heavily on government budgets and foreign aid, are no longer enough to meet Ethiopia’s 2030 development goals. To reach universal access to safe drinking water and basic sanitation, Aqua for All says the government must treat the private sector not as a side partner but as a central pillar of the WASH ecosystem.

Hzekiel Aynalem, Aqua for All’s WASH Finance Program Manager and Country Representative for Ethiopia, told reporters that while the country has made progress in expanding water coverage, current efforts move too slowly to achieve the ultimate target of 100 percent public access. “If we want to reach 100 percent community benefit at the required speed, the private sector must play its role,” he said.

Ethiopia, he noted, has seen rapid transformation in sectors such as telecoms, finance, and renewable energy, but the WASH sector has remained largely stagnant by comparison. He described it as an “untapped market” whose profitability is still under‑recognized due to the absence of clear incentives, coherent regulation, and visible success stories for investors.

“There have been gaps in showing the private sector what can be gained from this market,” Hzekiel said. “Our goal now is to bridge that gap and show that the water and sanitation sector can be a profitable and sustainable business environment.”

The financing challenge is substantial. Data indicate that Ethiopia faces an annual funding gap of about 1.14 billion US dollars to achieve Sustainable Development Goal 6 (SDG 6). Relying only on the traditional “3Ts” model—taxes, tariffs, and transfers—is widely seen as insufficient to keep pace with population growth and urbanization.

Aqua for All is pushing for “market‑led” solutions that can move away from the 40‑year legacy of donor‑driven, grant‑heavy projects where communities contribute little and sustainability is often in doubt. The organization argues that the government cannot fill the gap alone with its limited fiscal space.

Financial institutions, however, have long regarded WASH investments as high‑risk, in part because they are dealing with public services where revenues are unpredictable and governance standards vary. To counter that perception, Aqua for All is working to build investor confidence through innovative financing and risk‑sharing structures.

“We don’t just provide direction; we share the risk,” Hzekiel said. By combining grant capital, technical support, and innovative financial instruments, the organization aims to make the sector more attractive to commercial banks and microfinance institutions.

A flagship example is a 400 million birr loan facility established in partnership with Bunna Bank, which has become the first private bank in Ethiopia to launch a dedicated credit line for water and sanitation projects. Aqua for All contributed grant capital to cover part of the risk, allowing the bank to lend to microfinance institutions and WASH‑focused businesses. Those institutions, in turn, on‑lend to households and small entrepreneurs for water connections, sanitation upgrades, and small‑scale service delivery.

The facility, which is scheduled to operate until 2030, is expected to reach at least 134,000 people in its second phase alone, helping to expand access to clean water and basic sanitation in underserved urban and peri‑urban areas.

Despite such local successes, Aqua for All stresses that broader, systemic change will require a national policy mandate. The organization has worked with the Ministry of Finance and the Ministry of Water and Energy to develop a WASH Financing Strategy, but it says turning that strategy into enforceable policy and detailed implementation guidelines is now essential.

The upcoming One WASH National Program (Phase 3) is expected to place greater emphasis on private‑sector participation, including opportunities for public‑private partnerships and blended financing. Yet Aqua for All believes the government must go a step further by sending a clear, high‑level signal that the private sector is not only welcome but is central to the future of the WASH sector.

“We believe there needs to be a stronger and more specific direction from the government regarding the private sector,” Hzekiel urged. “When policies and strategies are supportive, the confidence of financial institutions to invest increases.”

Africa Puts Climate Delivery, Water Security At Center Of Development Push

0

Africa’s climate and development debate is shifting from promises to delivery, with leaders at the 12th African Regional Forum on Sustainable Development (ARFSD-12) calling for a stronger focus on implementation, financing, and accountability as the continent prepares for COP32.

At the heart of the discussions in Addis Ababa this week was a blunt message: Africa does not lack ambition. What it lacks is a global and domestic system capable of delivering climate and development commitments at the scale required. That concern ran through the 7th Africa Climate Talks, where Claver Gatete, Executive Secretary of the UN Economic Commission for Africa (ECA), said the world’s climate response is falling behind the urgency of the crisis and that trust is eroding because commitments are too often not matched by action.

Gatete said the global climate system is under strain just as climate impacts are intensifying faster than responses. Emissions cuts remain insufficient to keep the world on track for the 1.5 degrees Celsius target, while finance for vulnerable regions continues to lag far behind promises made in successive negotiations. For Africa, the stakes are especially high. The continent contributes less than 4 percent of global greenhouse gas emissions, yet it faces worsening droughts, floods, rising seas, and unpredictable weather that are already disrupting food production, water supply, infrastructure, and public finances.

The financing gap is one of the most glaring challenges. African countries need an estimated 277 billion US dollars a year through 2030 to implement their nationally determined contributions, yet the continent receives only about 11 percent of the funding required. Gatete argued that Africa should not be defined only by its vulnerability. The continent also holds some of the most important climate solutions, including abundant renewable energy resources, biodiversity for nature-based action, and a young population capable of driving innovation, green growth, and new forms of industrial development.

That broader vision is shaping Africa’s approach to COP32, which Ethiopia is preparing to host in 2027. Leaders in Addis Ababa said the conference must not become another stage for pledges without delivery. Instead, it should be an implementation-focused summit built around measurable outcomes, stronger finance tracking, and accountability systems that can close the gap between ambition and action. The call is for climate finance to move from commitment to deployment, with adaptation given far greater priority than it has received so far.

Adaptation is increasingly being framed not as a side issue, but as a core development priority for Africa. For countries facing climate shocks, investing in resilient agriculture, infrastructure, early warning systems, and water security is essential to protecting lives and sustaining growth. Yet adaptation remains underfunded, undertracked, and often excluded from the kind of predictable financing that could make a lasting difference. Gatete said even low-cost tools such as early warning systems are still not widely available across the continent.

Water emerged as one of the most powerful themes of the forum. In a high-level session on clean water and sanitation, Gatete said water must be treated not only as a basic human need but as critical economic infrastructure. He noted that water underpins health, food systems, energy production, cities, industry, and regional integration. That framing reflected growing concern that water insecurity is no longer an isolated challenge, but a systemic risk that can slow industrialization, strain public health systems, and deepen inequality.

The numbers show both progress and persistent gaps. Since 2015, nearly 300 million Africans have gained access to basic drinking water and close to 190 million to basic sanitation. But only 40 percent of Africans currently have access to safely managed drinking water, while just 30 percent have safely managed sanitation. In 2024, more than 200 million people still practiced open defecation, a situation that carries serious consequences for health, productivity, and dignity. Gatete said Africa’s industrial future depends on securing its water base, pointing out that hydropower, thermal energy, green hydrogen, agro-processing, mining, and manufacturing all rely on reliable water systems.

Climate change is making the problem worse. More frequent droughts, floods, and hydrological variability are intensifying stress on already fragile systems, while rapid urbanization is stretching services in many cities beyond capacity. Informal settlements remain especially vulnerable, with weak sanitation and poor water access compounding health and economic risks. The pressure is not only environmental but financial, and speakers at the forum said Africa needs about 64 billion US dollars annually to achieve water security and universal sanitation, far above current investment levels.

Across the forum, the financing debate remained central. Speakers said Africa’s development ambitions are being constrained not by a lack of ideas, but by the scale, cost, and structure of available finance. High borrowing costs, limited concessional resources, and a global financial architecture that often penalizes African countries are making it harder to invest in climate resilience, infrastructure, and social development. The region’s cost of capital remains too high, while domestic resource mobilization and public financial management systems continue to face serious constraints.

Panelists called for more blended finance, debt-for-climate swaps, risk-sharing mechanisms, and better project preparation so that African countries can build pipelines of bankable investments. They also pointed to the need for stronger public-private partnerships and more credible data systems to improve confidence and attract capital. Discussions highlighted examples from Rwanda, where climate resilience has been more tightly linked to national planning, as well as debt-for-development swap initiatives in Senegal, The Gambia, and Ghana. These were presented as examples of how innovative finance can help expand fiscal space and support long-term investments.

The private sector also featured prominently in the debate, with sessions at the forum emphasizing that public resources alone will not be enough to deliver the Sustainable Development Goals. Leaders said the private sector must be seen not only as a source of capital, but as a driver of jobs, technology, and industrial transformation. But to mobilize that capital at scale, Africa needs clear rules, stronger institutions, better pipelines, and partnerships that can turn promising ideas into investable projects.

As the forum drew to a close, the message was clear: Africa is ready to lead, but it needs a financial system and a climate regime that deliver at the same pace. With Ethiopia preparing to host COP32, the continent is positioning itself to push for a more credible climate agenda rooted in implementation, justice, and measurable results. For Africa, the test ahead is not whether it can make the case for action. It is whether the world will finally help turn that case into delivery.

Africa Air Cargo Beats Broader Downturn as Middle East Conflict Remakes Global Trade Flows

0

African airlines defied the global downturn in air cargo, recording the strongest growth of any region in March 2026 while the wider industry was dragged down by the Israel‑US‑Iran war reshaping Middle East transit corridors.

The International Air Transport Association (IATA) reported that global air cargo demand, measured in cargo tonne‑kilometers (CTK), fell 4.8 percent year‑on‑year in March, with international operations down 5.5 percent. Capacity also contracted, with available cargo tonne‑kilometers (ACTK) falling 4.7 percent globally. But within that picture, African carriers stood out: their freight demand rose 7.0 percent while capacity dipped 4.6 percent, lifting the cargo load factor by 5.4 percentage points to 49.6 percent—well above the global average of 47.9 percent.

Africa’s 7.0 percent surge made it the best‑performing region in global air cargo for March, according to IATA’s latest traffic data. The continent’s share of global cargo tonne‑kilometers remained relatively small at about 2.1 percent, but its growth rate contrasted sharply with the Middle East, where demand collapsed by 54.3 percent and capacity fell 52.4 percent.

IATA attributed the global decline largely to the severe disruption at major Gulf hubs such as Dubai, Doha, and Abu Dhabi, where airspace restrictions linked to the US‑Israel‑Iran conflict have forced airlines to cancel or reroute flights. The region normally acts as the main air bridge between Asia, Europe, and Africa, so the pullback hit transit‑dependent trade strongly, especially on routes that pass through the Gulf.

For African markets, this dislocation appears to be opening up new opportunities. The Africa–Asia trade lane, one of the busiest corridors for the continent, recorded year‑on‑year growth of 22.6 percent in March—the highest among all major lanes and the ninth consecutive month of expansion. Africa’s total share of global cargo tonne‑kilometers on this lane has risen to about 1.3 percent, reflecting stronger onward flows of manufactured goods, textiles, perishables, and raw materials.

As Middle East‑linked corridors staggered, Africa’s position at the edge of the main disruption zone has become strategically important. IATA’s lane‑level data show that while Europe–Middle East cargo fell 57.6 percent and Middle East–Asia dropped 58.6 percent, intra‑Asia trade and Asia–Europe traffic held up better, in part because of increased use of alternative routing.

Africa’s growing connectivity with Asia has benefited from this shift. With more freight being rerouted away from conflict‑affected airspace, some African‑linked lanes are seeing higher volumes and tighter capacity, which tends to push up freight rates. Data from logistics and rate‑tracking platforms confirm that several Europe–Africa lanes have recorded double‑digit rate increases as Middle East‑based capacity is withdrawn from the network.

For African exporters and importers, the situation is double‑edged. On the one hand, higher air‑freight costs are adding pressure to supply chains already exposed to volatile fuel and geopolitical risks. On the other, stronger demand for Africa‑linked routes signals that carriers are increasingly willing to use the continent as a connecting node or an end‑market, which could attract more direct services and investment over time.

Africa’s resilience is not limited to freight. Passenger traffic also showed robust growth, reinforcing the region’s role as one of the few bright spots in an otherwise strained global market. IATA’s March 2026 passenger data show that African airlines reported a 20.6 percent year‑on‑year increase in demand measured in revenue passenger kilometers (RPK), compared with global growth of just 2.1 percent.

Capacity on African routes grew 10.3 percent, pushing the passenger load factor up 6.5 percentage points to 76.2 percent—the largest relative improvement among regions. Within international markets, African carriers saw demand jump 19.2 percent even as Middle East carriers recorded a 60.8 percent slump linked directly to airspace closures and flight cancellations across the Gulf.

With jet fuel prices up 106.6 percent year‑on‑year in March and global refining margins surging, the cost of operating in the region will remain a key constraint. IATA’s Director General Willie Walsh warned that the abrupt withdrawal of Middle East‑linked capacity has tested the resilience of global supply chains, and that the industry’s ability to keep freight flowing will depend on how quickly networks can rebalance and how fuel‑supply disruptions evolve.

Three Countries Seek To Buy Ethiopian-Made Aluminum

0

As shipping routes through the Strait of Hormuz and the Red Sea remain volatile, regional demand for locally produced aluminum is rising, creating a new export opportunity for Ethiopia’s growing manufacturing sector.

Tekhaf Aluminum, a relatively new industrial player based near Mekelle, says it is transitioning into a strategic export phase after receiving strong purchase interest from South Sudan, Uganda, and Mozambique. The company, which began large‑scale production only nine months ago, is now positioning itself as a regional supplier of construction‑grade aluminum in a market that has become accustomed to long waits and high costs for imports from Asia.

The disruptions to traditional maritime corridors have altered how East African builders and contractors source materials. With shipments from China exposed to unpredictable delays and surging freight costs, neighboring countries are increasingly turning to nearby producers. Getahun Tilahun, Sales and Marketing Manager at Tekhaf, told Capital that the closure or repeated disruption of key trade routes such as the Strait of Hormuz has not only triggered global supply shocks but also driven aluminum prices higher and created shortages in African markets.

“Middle Eastern countries produce about 9 percent of the world’s aluminum,” Getahun explained. “When transit routes are blocked, both the export of finished metal products and the supply of raw materials like alumina are disrupted. That is creating a favorable environment for Ethiopia to emerge as a regional supply hub.”

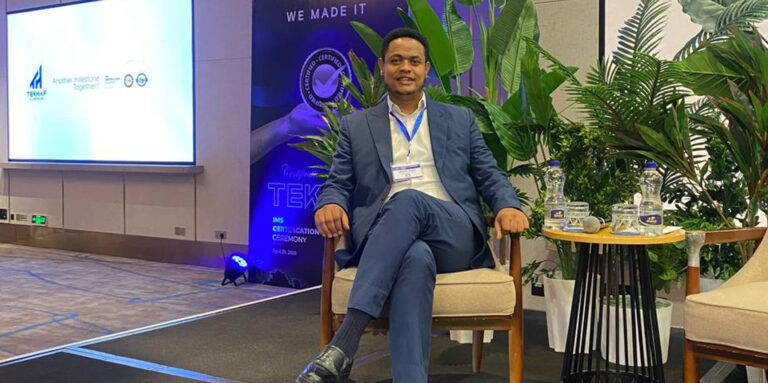
Near‑term demand has started to materialize. The company has received formal requests from South Sudan, Uganda, and Mozambique for standard aluminum sections, with buyers indicating they are ready to take delivery in high tonnage volumes. Before Tekhaf could engage regional partners seriously, it needed to pass international quality checks, most notably the ISO certification process. The company now reports that it has secured four major international standards: ISO 9001:2015 for quality management, ISO 14001:2015 for environmental management, ISO 45001:2018 for occupational health and safety, and accreditation from the Ethiopian Conformity Assessment Enterprise.

“In the international market, it is not enough to simply say your products are of high quality,” Getahun said. “You must be verified by an independent body. By going through the ISO process, we have moved beyond a ‘local shop’ mindset and are now approaching African buyers with the confidence that our products meet recognized international standards.”

Tekhaf’s 2026‑standard vertical powder‑coating facility gives the company an edge in surface finish and durability. With an annual production capacity of over 15,000 metric tons—more than 45 tons per day—the plant can manufacture aluminum sections up to 4.5 millimeters thick, suitable for large facade projects and high‑rise buildings such as the Commercial Bank of Ethiopia headquarters and Zemen Bank. Until recently, such sections were imported from China because no local firm met the technical specifications; Tekhaf now says it has filled that gap.

The manager also highlighted the company’s use of LPG gas in the manufacturing process, which helps maintain the straightness of the sections and prevents color fading—addressing common complaints about imported aluminum that can warp or discolor over time. The adoption of an integrated management system (IMS) further strengthens Tekhaf’s profile, linking raw‑material handling, quality control, and final product delivery under a single framework.

Despite these advances, the company faces structural constraints. The conflict in northern Ethiopia delayed the full start of operations, and the plant has only been running at about two‑thirds of its 45‑ton‑per‑day capacity. The main bottleneck is foreign exchange. Since aluminum billets and some key inputs come from China, shortages in hard currency have held back production. The company says it now employs more than 300 workers, most of whose salaries, raw‑material imports, and utility costs are foreign‑currency‑indexed.

“To be honest, the government has improved its foreign‑exchange‑allocation policy; without that support, we would not be able to keep our employees or stay in business,” Getahun acknowledged. “But to meet the kind of regional demand we are seeing, especially from Mozambique, South Sudan, and Uganda, we need a more stable and predictable supply of raw materials.”

To reduce dependence on foreign billets, Tekhaf is building an integrated smelting plant that will melt aluminum scrap and related metals into standardized billets. The facility is designed to insulate the company from global supply‑chain volatility and, in the longer term, position Ethiopia as a regional hub for finished and semi‑finished aluminum products. If the smelter comes online as planned, the firm could not only increase its internal capacity, but also begin supplying billets to other regional manufacturers.

For now, the convergence of geopolitical disruption, regional infrastructure needs, and Tekhaf’s new quality certifications is creating a window of opportunity. By turning regional trade bottlenecks into a business model, Ethiopia’s emerging aluminum sector is signaling that, even amid global supply shocks, a “Made in Ethiopia” label can now be a viable alternative in the African construction market.