Thursday, October 22, 2026
Home Blog Page 216

UNCTAD warns Africa could face a costly oil shock from Hormuz disruptions

0

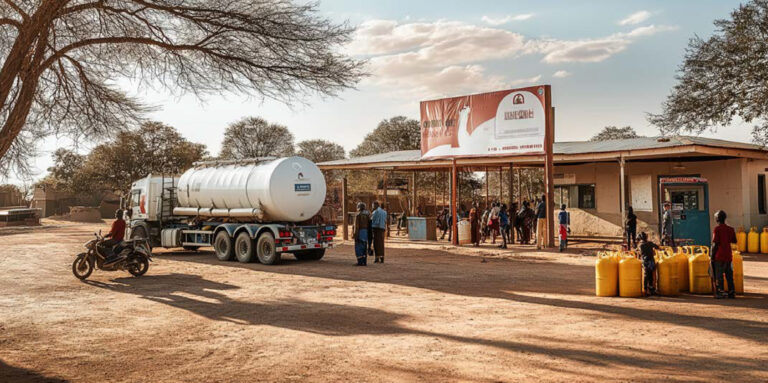
Africa is among the regions most exposed to the fallout from disruptions in the Strait of Hormuz, with the United Nations Conference on Trade and Development warning that higher oil prices could deepen inflation, strain budgets and hit vulnerable economies hard. The warning is especially relevant for African least developed countries and small island developing states that depend heavily on imported fuel.

UNCTAD said 65 of 75 vulnerable economies it examined are net importers of oil, and 983 million people live in those economies. More than 30 percent of them live below the extreme poverty line of 3 dollars a day, making any increase in fuel costs a direct threat to already fragile household budgets.

The report said vulnerable economies mainly import refined oil products rather than crude, because many lack sufficient refining capacity. In 2024, refined products accounted for 97.8 percent of net oil imports in the group of oil-importing vulnerable economies, leaving them highly exposed to price spikes.

UNCTAD warned that a 50 percent rise in oil prices could raise the annual oil import bill of vulnerable economies by 20.4 billion dollars, including 16.1 billion dollars for least developed countries and 4.3 billion dollars for small island developing states. For countries already struggling with debt, food insecurity and weak fiscal buffers, that bill would force hard trade-offs between fuel subsidies, public services and long-term investment.

Several African countries would be hit especially hard. UNCTAD’s table shows that among least developed countries, Mauritania could see an import bill increase equal to 7.3 percent of GDP, while Gambia would face 6.3 percent and Burkina Faso 5.0 percent. Liberia, Zambia, Lesotho and Mali also rank high on the list of economies with large import bill increases.

The report also flags African states that rely heavily on oil sourced from the Hormuz region. Uganda sources 61.5 percent of its oil imports from the area, Mauritius 58.3 percent, the United Republic of Tanzania 56.0 percent and Zambia 44.7 percent. Other African economies listed include Mauritania, Mozambique, Malawi, Senegal, Cabo Verde, Togo and Benin.

UNCTAD said the consequences would extend beyond higher fuel bills. Rising oil prices push up freight and transport costs, feed broader inflation and can weaken exchange rates and growth. For governments with limited fiscal room, the shock can also widen current account deficits and increase pressure on public finances.

The agency said the situation shows how geopolitical disruptions in one corridor can quickly become a development crisis for the world’s poorest economies. In its warning, UN Secretary-General António Guterres said that when the Strait of Hormuz is strangled, the world’s poorest and most vulnerable cannot breathe.
Africa sees risk and opportunity as global fragmentation deepens

0

Africa is set to play a central role in the next phase of global economic fragmentation, with new risks in trade, borrowing and regulation also opening the door to long-term growth if governments move quickly, according to a World Economic Forum report.

The report says emerging and developing economies are facing rising pressure from trade shocks, higher borrowing costs and diverging global rules, but argues that Africa’s demographics, natural resources and regional integration efforts give the continent a strong chance to benefit from the realignment of global supply chains.

African economies are especially exposed because many are small, open and heavily dependent on foreign capital, commodity exports and external trade. The report notes that recent global policy changes have already weakened development assistance, reduced investment flows, raised debt-service burdens and increased tariff pressure on the continent.

It also says African countries continue to pay more to borrow than similarly placed economies elsewhere, while weak market depth and limited data make sovereign risk appear higher than it may be in reality. That combination, the report warns, makes the continent more vulnerable to external shocks.

At the same time, the report highlights Africa’s structural advantages, including rapid population growth, urbanization, strategic minerals, renewable-energy potential and manufacturing prospects. It says the African Continental Free Trade Area could lift GDP by a cumulative $1.4 trillion between 2021 and 2045 if fully implemented.

The report also points to the Pan-African Payment and Settlement System as a key step toward reducing dependence on foreign currencies for regional trade. It says deeper regional integration, stronger capital markets and better data could help African economies capture more value from shifting global supply chains.

To turn that potential into results, the report recommends faster implementation of AfCFTA protocols, broader use of PAPSS, improved credit-rating data and greater African participation in global ratings agencies. It also calls for more investable projects, stronger infrastructure pipelines and deeper domestic capital markets to mobilize local savings.

For African policymakers, the message is clear: fragmentation carries real costs, but coordinated regional action can help the continent build resilience and position itself for growth.

IMF brings forward $200 million in support

0

The International Monetary Fund (IMF) has announced that it is rephasing the disbursement schedule for its ongoing support under the Extended Credit Facility (ECF). Originally set at 7.5 percent, the support will now increase to nearly 14 percent of the approved $3.4 billion, effective July 2024.

In its fifth review report, published midweek, the IMF disclosed that it has submitted $468 million for final approval by its Executive Board. These funds represent continued support for the macroeconomic reform program that Ethiopia initiated in the previous budget year.

During her latest press briefing, Julie Kozack, Director of the IMF’s Communications Department, explained that the rephasing of disbursements will bring forward $200 million under the program to help Ethiopia address the immediate economic impact of the war in the Middle East and the Persian Gulf. It is worth recalling that the IMF previously noted that the regional conflict has affected Ethiopia in key areas, including strategic commodity imports such as fuel, as well as significant volumes of exports and remittances.

In the fifth review, published on Wednesday, June 3, the IMF commended the economic reform program that the Ethiopian government has been implementing since last budget year. The IMF said the authorities continue to make progress in advancing their Homegrown Economic Reform Agenda, achieving favorable macroeconomic outcomes up until the onset of the Middle East conflict.

“Output indicators, exports, reserves, and government revenue all continued to improve through early 2026, alongside a decline in inflation. The war in the Middle East was a significant external shock that disrupted trade, causing temporary fuel shortages and sharp increases in the prices of imported fuel and fertilizer. Even so, economic activity appears robust, with only modest impacts so far on output growth and consumer price inflation,” said Álvaro Piris, who led the IMF team that stayed in Ethiopia from May 6 to 20.

However, the Fund appears to have adjusted its previous stance on lifting the credit cap. Piris noted that maintaining strong policy implementation will be essential to consolidate macroeconomic stability.

“A tight monetary policy stance remains warranted to anchor inflation expectations. Further efforts to enhance the functioning and transparency of the foreign exchange market will be important to support external adjustment,” he added.

United Capital makes history as Ethiopia’s first foreign investment bank

0

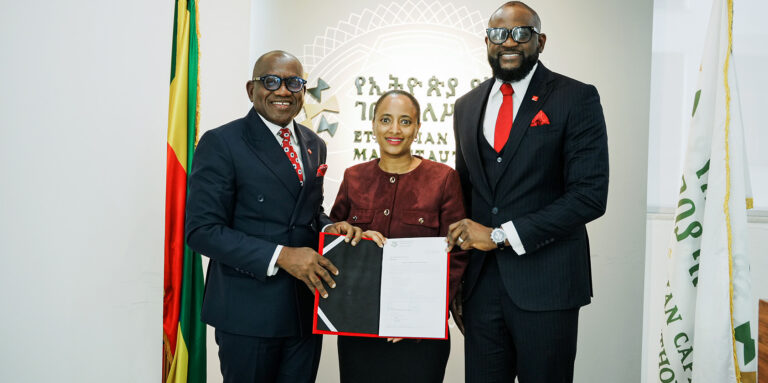
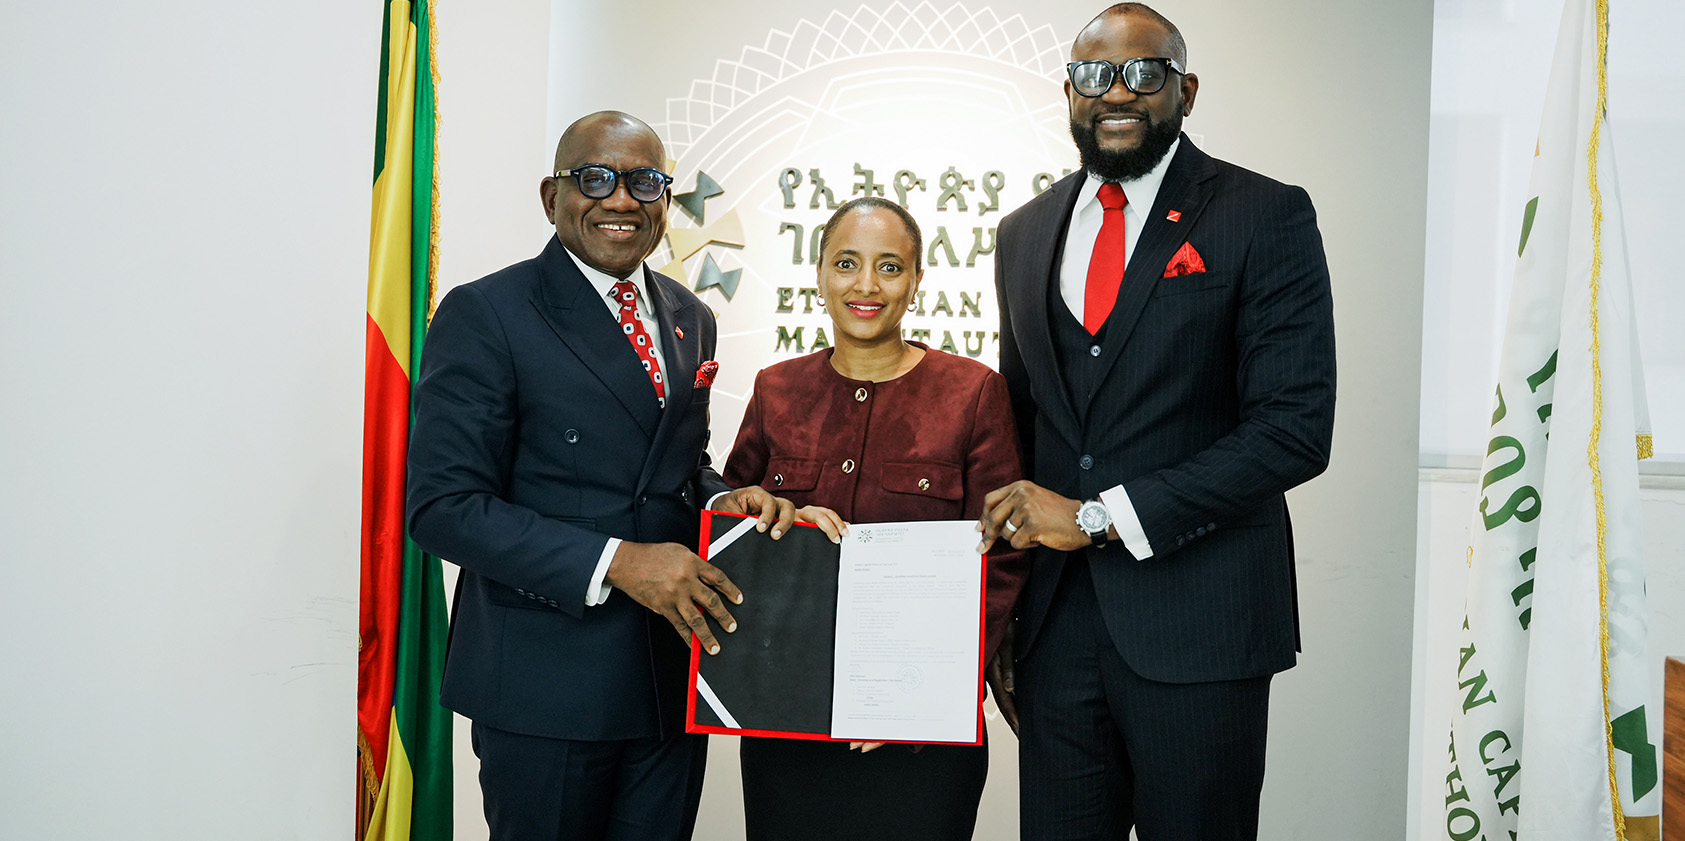
The Ethiopian Capital Market Authority has granted Nigeria’s United Capital Group the country’s first foreign investment banking licence, marking a historic milestone for Ethiopia’s emerging capital market.

The licence, issued on 5 June 2026, followed months of regulatory review and legal vetting involving the Capital Market Authority, the Ethiopian Investment Commission and other relevant government institutions, according to ECMA Director General Hana Tehelku, who spoke exclusively to Capital.

United Capital will operate through a wholly owned local subsidiary, United Capital Financial Services PLC, making it the first foreign investment bank licensed to establish a base in Addis Ababa. The company said it has brought in more than $1.5 million in capital to fund its investment banking operations in Ethiopia.

Hana said the licence reflects Ethiopia’s efforts to build a robust and globally competitive capital market while opening the door to foreign expertise and capital inflows. She said the regulator carried out extensive due diligence, including verification of the company’s regulatory standing with Nigerian authorities before approving the application.

According to the Authority, United Capital may eventually operate under up to four licence categories, including investment banking and collective investment scheme management.

The entry of the Nigerian firm is expected to signal confidence in Ethiopia’s nascent capital market and encourage other foreign institutions to consider entry. While D & T Management Consulting, a Deloitte subsidiary, was previously licensed as a securities investment adviser, United Capital is the first foreign institution to receive an investment banking licence.

United Capital Group CEO Peter Ashade praised the Ethiopian government and Prime Minister Abiy Ahmed for reforms aimed at opening and modernizing the financial services sector. He also said the company received strong support from the Ethiopian Capital Market Authority during the licensing process.

“We are honored to be the first foreign institution licensed to provide financial services in Ethiopia,” Ashade told Capital. He said the move was a milestone for both Nigeria and Ethiopia and reflected growing pan-African financial cooperation.

Ashade said United Capital intends to contribute to the growth of Ethiopia’s capital market by supporting human capital development, capacity building and the training of local professionals.

Hana said the greatest contribution expected from the company is not only financial capital, but also human capital and technical expertise. She said United Capital will be required to hire, train and empower Ethiopians so that its presence can help develop a broader pool of domestic investment bankers, analysts and compliance specialists.

United Capital’s Africa Director, Ejikeme Okoli, said the firm’s experience across Africa positions it to help accelerate the development of Ethiopia’s financial markets. He said the company sees Ethiopia as part of a broader pan-African strategy that already includes operations in several countries across the continent.

The Authority also said it is working with the Nigerian Securities and Exchange Commission on regulatory benchmarking and capacity-building initiatives.